Differences in car, bike and scooter sharing business models
February 25, 2020
min. read

The mobility industry is growing at a rapid rate, with innovations happening across cars, bikes and scooter sharing alike. This article explores the most recent advancements in the market and how industry leaders are finding new ways to compete. Learn about the different models for Mobility as a Service and what it means for the future of transportation.
According to research by the Internet of Things, the number of carsharing service users across the world is expected to grow from 50.4 million people in 2018 to 227.1 million in 2023. The number of cars used for car sharing services is also forecasted to increase from 332,000 at the end of 2018 to 1.2 million by 2023. The rising demand for these services has driven more companies towards developing methods of sharing that go beyond traditional single use cars.

Image source: Internet of Things
Free Floating
A new model of car sharing that has recently grown in popularity is free floating carsharing, which allows users to pick up a car in one location and return it anywhere within a predefined Home Zone. Challenging the idea of ownership, this service currently has 3 million users worldwide, with over 30 thousand vehicles available across more than 50 cities.
there are currently over 30 thousand vehicles equipped with this service across more than 50 cities worldwide
Dailmer and BMW became a leader in the free floating industry when they merged their two car sharing services, Car2Go and DriveNow, in February 2019 to form SHARE NOW. With over four million members, the free floating car rental service is available in 18 major cities across Europe with a fleet of 20,500 vehicles to choose from. Members register through a mobile app, gaining access to the services for the cost of $0.32 per minute. The company covers the fixed costs of car loans, car insurance and car maintenance so users are able to enjoy the freedom of driving without the responsibility of ownership.
The largest benefit of free float car sharing is the higher demand that can be met on average per ride and car each day. However, this model still includes a lot of operational day-to-day tasks such as maintenance, relocating, fueling/charging that can require a larger team.
Station Based
The traditional model of car sharing services is station based, where users can pick-up vehicles from a fixed rental station after filling out paperwork in person or through a mobile app. After signing an agreement, the renter is able to drive the car wherever they would like. The lease ends once the car is returned to a designated rental station that has been approved by the provider. This model does not provide the same flexibility to users that newer offerings have, however, it remains one of the best ways for providers to track the vehicles without developing complex systems.
Enterprise CarShare is an example of traditional station based car sharing services. Offering users three membership levels to choose from, the pricing varies based on hourly, daily and overnight rates as well as kilometers driven. Depending on the membership, hourly rates are around $8, daily rates $75 and overnight rates start at $29. The vehicles are available for pick-up at designated stations or lots and can be returned at the discretion of the user to any Enterprise location at the end of their trip.
Compared to free float services, station based car sharing has lower operational costs since only a few fixed stations need to be monitored and checked each day. Right now this model is most profitable in the market, once free float operators enter on a wider scale it will be harder to keep up with the high demand.
Peer-to-Peer
Peer-to-peer car sharing services have experienced large growth in the past few years. Research found that by 2017, more than 2.9 million people in North America were using these services renting over 131,336 vehicles. Peer-based car-sharing fleets expanded by 80 percent between 2016 and 2017 and memberships doubled.
The peer-to-peer car sharing model allows users to list their own vehicles on a sharing platform, connecting hosts to guests looking to rent. This style of sharing allows users to set their own rental rates, while giving members who are looking to rent a wider selection of vehicles to choose from.
Turo is a leader in the peer-to-peer sharing industry, serving as a marketplace where guests can book any car they want from hosts across the US, Canada, the UK and Germany. The guests are able to choose from a unique selection of cars within their area, while allowing the hosts an opportunity to earn extra money to offset the costs of ownership. The company currently has over 10 million users, with more than 350,000 vehicles listed for rent.

Image source: cnet
The rates for Turo are charged by the hour and are subject to adjustments made either by the company’s own algorithm or the specific daily rates charged by each host.
In this model, the operator acts as an aggregator without ownership over the vehicles, which makes it easier to scale the business without the need for huge capital investments. However, it becomes more difficult to control the quality of the experience since every car cannot be checked on a regular basis. It is important to establish a strong customer support team to help resolve any issues that occur.
Autonomous
The future of car sharing is focused on eliminating the driver all together. Autonomous vehicles are beginning to make their way into the marketplace, with the hope being that fleets of self-driving cars will be able to pick-up users at any given location and return to the designated charging area all on their own.
A leader in this next step of mobility is Waymo, a company that emerged from Google’s self-driving car project. The company launched their first commercial self-driving-car service in December 2018, in Phoenix. The self-driving cars operate in an approximately 100-square-mile radius, serving the towns of Chandler, Gilbert, Mesa and Tempe. Available to a select few pre-approved riders, the hope is that driverless vehicles will be a main part of transportation in the future. There are currently around 1,500 monthly active users helping with the testing program.
In theory, the economics of this model should be great as there is no driver costs or relocating costs, keeping operational requirements to a minimum. These vehicles will however be heavily regulated, with limited access in the near future.
The demand for accessible transportation in cities has expanded beyond traditional motor vehicles. Across the world, urban areas are beginning to adapt bike sharing programs that allow citizens to use both standard bicycles and e-bikes as a form of travel. The bikes are usually selected from one docking station, and later returned to another across the city. There is currently believed to be nearly 900 bike-sharing systems available globally, with continuous advancements being made each year.
The bike sharing market is expected to grow from a $2.7 billion dollar industry to $5 billion by 2025, according to a report by Research and Markets. That in mind, bike sharing companies across the world should approach expansion with caution to avoid over extending their services. In 2018, Chinese bike sharing start-up Ofo experienced financial decline due to their costly global expansion that was not supported by commercial success. The company was unable to maintain the accessibility of its competitors who partnered with mobile app providers, offering them a wider reach for their services. Without support from an investment partner, Ofo could no longer sustain the maintenance of its bike sharing fleets, let alone compete in the market.
We believe you can build a successful bike share company once you have the right strategy in place. It is important to be operationally efficient when starting out, initially launching a smaller fleet and growing organically with the demand. If you start by scaling wide without having the matching demand, your resources will be spread too thin. The most successful bike share programs work with the local municipalities and cities to determine revenue streams and find the best options to connect with riders.
Dockless Bike Sharing
The dockless bike sharing model offers users access to bicycles that do not require a docking station. Dockless systems allow the bikes to be located and unlocked through a mobile app then returned to a designated district at a bike rack or along the sidewalk. This model is designed for short term use, ideal when travelling or visiting somewhere as a tourist. Most dockless sharing services offer single rides for $1 or monthly fees for continuous use.
Lime was one of the first companies to offer dockless bike services. Users access the bikes at designated areas through the company’s mobile app, initially they are charged a fixed rate to unlock the vehicle and then per minute for the duration of their trip. The rates and promotions available vary based on location and time. Program packages are also offered for users who wish to make monthly payments or have the services available to their employees on a regular basis.
This model of bike sharing is ideal for users because it is easily accessible and convenient to employ every day. There are high operational costs that come with this type of service, as well as a larger risk for vandalism or damage to the bikes.
Station Based
Traditional bike share programs include docking stations where the bicycles are locked until a user purchases a ride. The user pays at a nearby pay station before unlocking the vehicle for a short term trip, later returning it to any available docking station when finished. There are typically two types of payment options available, a flat membership fee or pass that allows access to the bikes for a certain period of time and then a usage fee that charges for the amount of time you spend riding.
San Francisco is one of the first cities to create a regulatory and permitting framework around the trend of bike-sharing. In December 2019, 4,000 e-bikes were launched as part of the Bay Area bike sharing program, designed to make mobility easily accessible to citizens. The program provides rides with the option to purchase a single ride, starting at $2, through Lyft’s mobile ride-sharing app. There are over 300 docking stations available throughout the city, allowing users to travel across the Bay Area more efficiently.
The Capital Bikeshare, in Washington D.C. has a membership fee of $85 annually offering lower usage charges throughout the year. For the first 30 minutes a ride, members aren’t charged, they then receive a rate of $1.50 for the next 30, $3 for the third and finally an additional $6 for every other 30 minute period. For non-members, the first 30 minutes also has no charge but they experience higher fees for every 30 minutes after that. The higher usage fees are balanced out by lower costs at the start -- a daily Capital Bikeshare pass is only $8 and a monthly pass comes to $28.
Station based bike sharing can help bring a stable ROI for every bike since operational costs are low, and there is a minimal need for maintenance, relocation or charging. As dockless bikes continue to expand in the market, this model risks losing loyal users in the long-run.
Sponsored by Corporate
Some bike share programs operate in partnership with corporations who sponsor the vehicles. Operating like a standard bike share program, these vehicles operate in conjunction with the local municipalities.
In London, the city offers a public bicycle hire scheme funded by Santander UK. With more than 750 docking stations and 11,500 bikes available for hire around the city, users have easy access to the vehicles. The program operates 24 hours a day, year-round with an initial cost of 2 Euros for a daily trip, charging an additional 2 Euros per half hour after the first 30 minutes. Users have the option to hire a bike using their bank card at the docking station, or through the official mobile app.
This model is great for any operator that can find a reliable partner who is interested in establishing this type of deal, however, you still run the risk of losing that partner later on.
The fastest growing trend in mobility is the advent of e-scooters. They are inexpensive, accessible through mobile apps similar to bike sharing and available in over 100 cities worldwide. According to the US National Association of City Transportation Officials, riders took 38.5 million trips on shared electric scooters in 2018 compared to the 36.5 million trips on docked bikes. The Boston Consulting Group estimates that the global e-scooter market will grow to US$50 billion by 2025, with approximately 50% of the users being located in Europe and the USA. Micro-mobility is quickly becoming the preferred method for short term travel and companies have already begun to emerge as leaders in the market.

Image source: nacto.org
Station Based
Similar to station based bikes, some e-scooter providers offer docking stations where the scooters can be unlocked through a mobile app and then returned later to any available docking station.
DASH Scooters operates out of Nashville, TN, offering docked e-scooters styled like vespas that can be rented at set rates through their mobile app. Starting at $40 for two hours, the rates increase based on time travelled and day of the week. The brand launched after the emergence of other leaders such as Bird, Lime and Spin, who have set the bar for innovation in e-scooters. Their app allows users to locate nearby docking stations where the scooters can be returned to at the end of a trip.
The best way for operators to get a high return on their business is to have a combination of station based and dockless scooters. This will help maintain growth over time, while keeping up the high demand.
Dockless Scooters
Leaders in the mobility industry have begun to focus on the possibilities of dockless scooters. This model involves e-scooters that do not require a docking stations, but instead can be rented from a designated location and then returned anywhere in another.
Spin operates in 62 cities and 20 campuses across the United States, offering fleets of electric scooters for easy, short term travel. Users are able to unlock the scooters through their mobile app, once the ride is complete they can leave the scooter at any designated location and the cost will appear on the app. Charges vary depending on the length of the ride.
This model is currently experiencing high demand due to its convenience and ease of access for users. There are a large amount of maintenance and operational costs required, similar to other dockless mobility services, as well as increasing regulations across cities.
Hotel Services
While the future of e-scooters in cities is an on-going process, the services have begun to expand into the tourism sector. Hotels and resorts have begun to offer scooter sharing services to allow guests to easily travel throughout the location, or explore local surroundings. The options vary between station based and dockless scooters, with pricing packages being dependent on the destination.
Rentskoot is a start-up in Finland that offers small fleets of electric scooters to hotels. Guests are then able to rent the scooters from the hotel premises as a unique way to experience the local neighbourhoods. The company provides operational training to staff, free maintenance and the ability to advertise the hotel’s logo on the scooters. Travelling at a maximum speed of 25 km/h, the compact size and battery life makes this service ideal for short term use within cities.
By focusing on hotels, this model allows businesses to be more innovative with their designs while keeping a consistent demand amongst the growing market. An agreement will need to be made with the hotel in advance regarding guidelines for use and overall costs distribution.
What does this mean for the future of mobility?
The car sharing industry is projected to reach a 16.5 billion USD revenue by 2024, with an annual increase of 34.8% every year. A trend towards electric vehicles is also predicted as the demand for lithium-ion batteries has been predicted to increase by 380% by 2025. In addition, the bike and scooter rental market is expected to grow from USD $2.5 billion in 2019 to USD $10.1 billion by 2027, at a CAGR of 18.9 percent. Dockless systems will most likely continue to dominate the market, as their flexibility and ease has historically made them the more popular option for riders.
Every sector of MaaS has one thing in common: the desire to make transportation easier for riders. Ultimately each service compliments the other by providing different options for mobility that can each work together to get a user from point A to point B and back. If someone arrives in the city by train, they could then travel to work using an e-bike or e-scooter to avoid traffic. When returning home late at night a car sharing service could be used to get them there in one trip. The hope is that the future of mobility will consist of a connected network designed for safe, efficient and easily accessible travel.
With this quickly growing market on the rise, there hasn’t been a better time to become a leader in mobility. Start your journey in 20 days with ATOM!
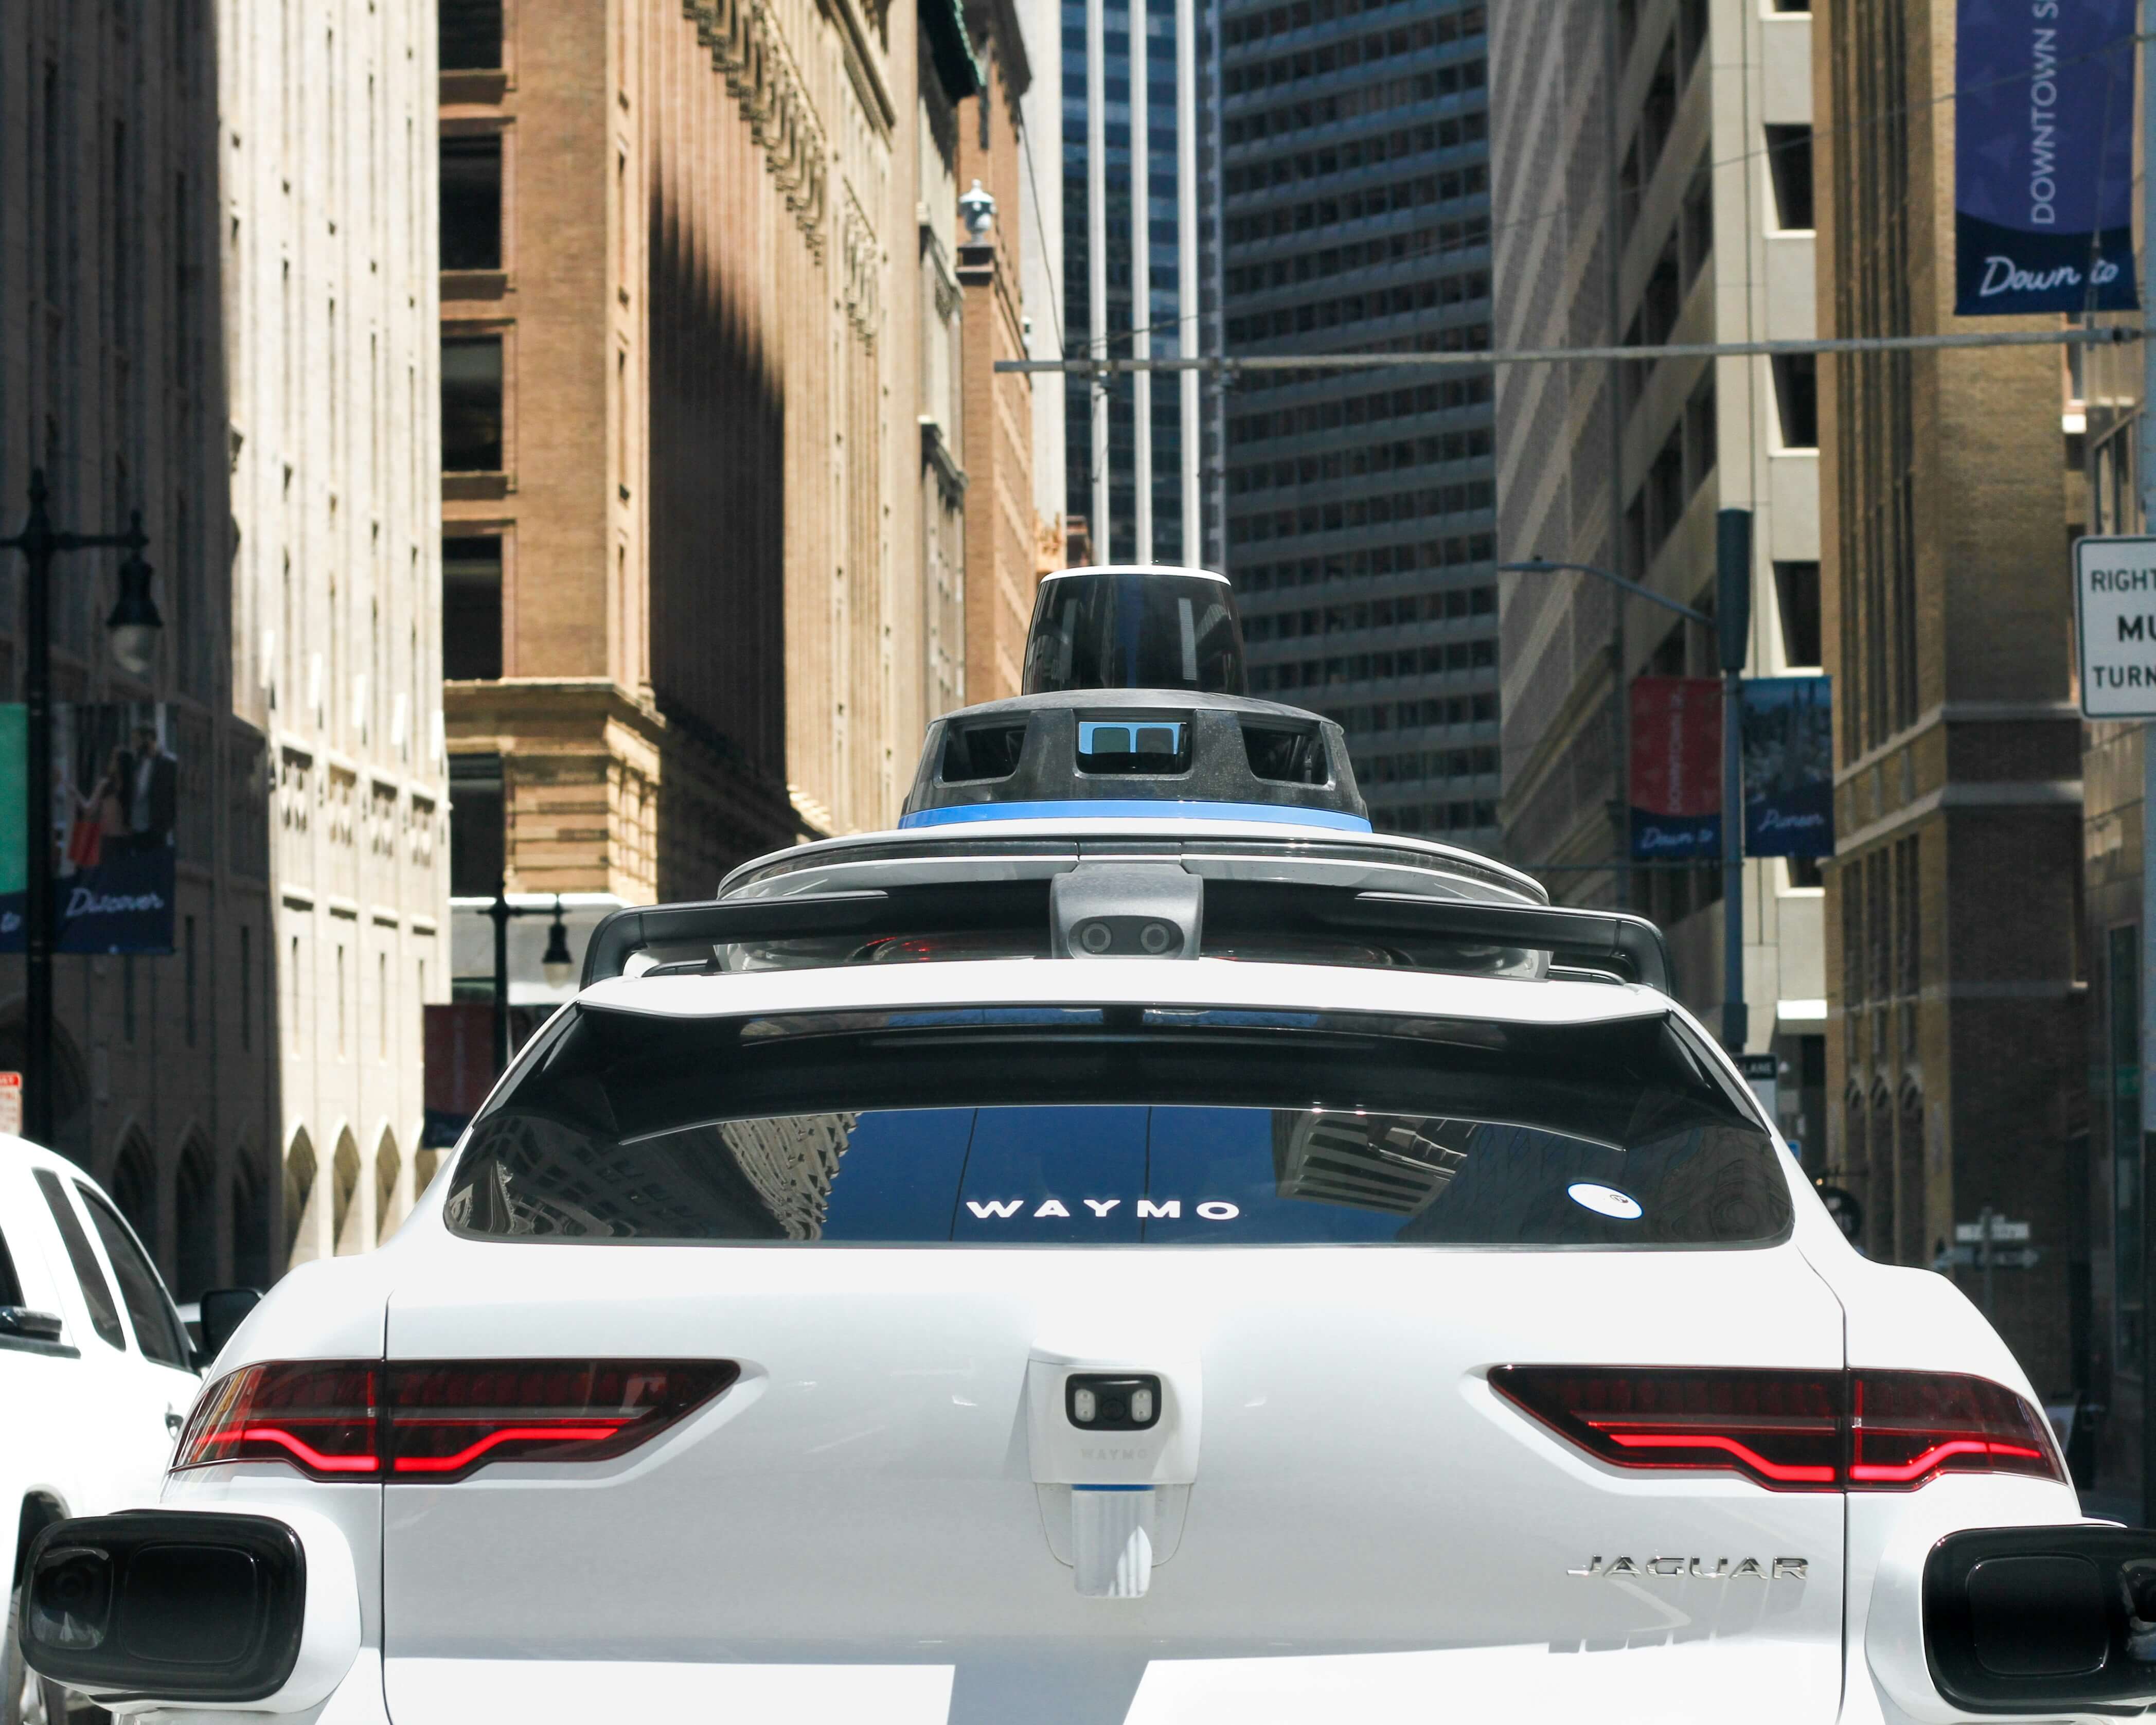
🤖 Who will actually operate Europe’s robotaxi fleets? Autonomous driving may remove the driver, but it doesn’t remove the work behind the car. Robotaxis still need charging, cleaning, maintenance, depots, customer support and someone managing the fleet every day. Early projects in Zagreb, Madrid and London illustrate different stages of deployment and how AV technology providers, fleet operators and booking platforms can work together. Taxi, rental and car-sharing companies already handle many of these tasks. What would it take to turn that experience into an autonomous fleet business?
For a taxi fleet owner, autonomous vehicles may seem to remove the most important part of the current business – the driver. But even without drivers, someone still needs to take care of the cars. They need to be owned or financed, charged, cleaned, inspected and repaired. Someone also needs to manage depots, deal with incidents, help customers and make sure enough cars are available.
The first robotaxi services and tests in Europe are already showing how this could work. The company that develops the autonomous driving technology does not always own or operate the cars. The app where customers book their rides may come from another company too. This could leave an important role for taxi, rental, car-sharing and other fleet companies that already know how to manage vehicles.
A taxi company today manages both cars and drivers. Drivers need to be recruited, scheduled, paid and supported. With a driverless fleet, these tasks would eventually disappear, but most of the work related to the cars would stay.
Autonomous cars still need charging or refuelling, cleaning, tyres, inspections, repairs and insurance. They also need somewhere to park when they are not working. If there is an accident or a technical problem, someone needs to deal with it and get the car back on the road. Customer support is still needed too when there are problems with bookings or payments, or when someone leaves something in the car.
Some of these tasks may even become more important. Robotaxis are expensive, and every hour a car spends charging, being cleaned or waiting for maintenance is an hour when it cannot take passengers. Moove, for example, already provides fleet ownership, depots, charging, maintenance and 24/7 operations for autonomous vehicles.
Drivers also do more than drive: they notice damage, report faults, help passengers and respond when something goes wrong. Without a driver, these responsibilities need clear processes and dedicated support. Existing fleet experience is an advantage, but operators will need to adapt it to vehicles running without someone behind the wheel.
There can be several companies behind one robotaxi ride. One provides autonomous driving technology, another may own the cars, and a local company can take care of the fleet. A platform such as Uber can then connect the cars with passengers. Sometimes one company may do several of these things, but this is not always the case.
Zagreb is one example. Pony.ai provides the autonomous driving system, Verne owns and operates the fleet, and Uber connects it with customers through its app. Autonomous rides became commercially available through Uber in August 2026 with a licensed operator onboard. On 10 September, Pony.ai and Verne also started fully driverless passenger test rides on a 22-kilometre route connecting parts of Zagreb with the airport. These are still limited test rides, not a fully driverless service across the whole city.
A similar model is being tested in Madrid. WeRide, Uber and AVOMO received permission in September 2026 to start testing and mapping under Spain’s ES-AV framework. The first 20 vehicles have an onboard specialist. WeRide provides the autonomous technology, Uber connects the cars with passengers, and AVOMO takes care of fleet operations. Commercial operations are planned for later in 2026, but the current permit is for testing and preparation rather than a general driverless taxi service.
In London, Wayve and Uber launched supervised autonomous passenger rides in September 2026. Customers can be matched with an autonomous vehicle through the Uber app, but there is still a licensed driver in the car.
The plans for the next few years are already much bigger. Pony.ai and Uber announced in August 2026 that they plan to deploy more than 2,000 robotaxis in Europe, starting with Zagreb and later expanding to four more European cities.
Bolt and Lucid announced another partnership in September, with Bolt aiming to deploy at least 25,000 autonomous Lucid vehicles across European cities. This is a future target, not 25,000 cars already operating today.
How these fleets are owned and operated may also be different from one city to another. Local regulations, available vehicles, charging and depot infrastructure and partnerships will all have an effect on how each service is set up.
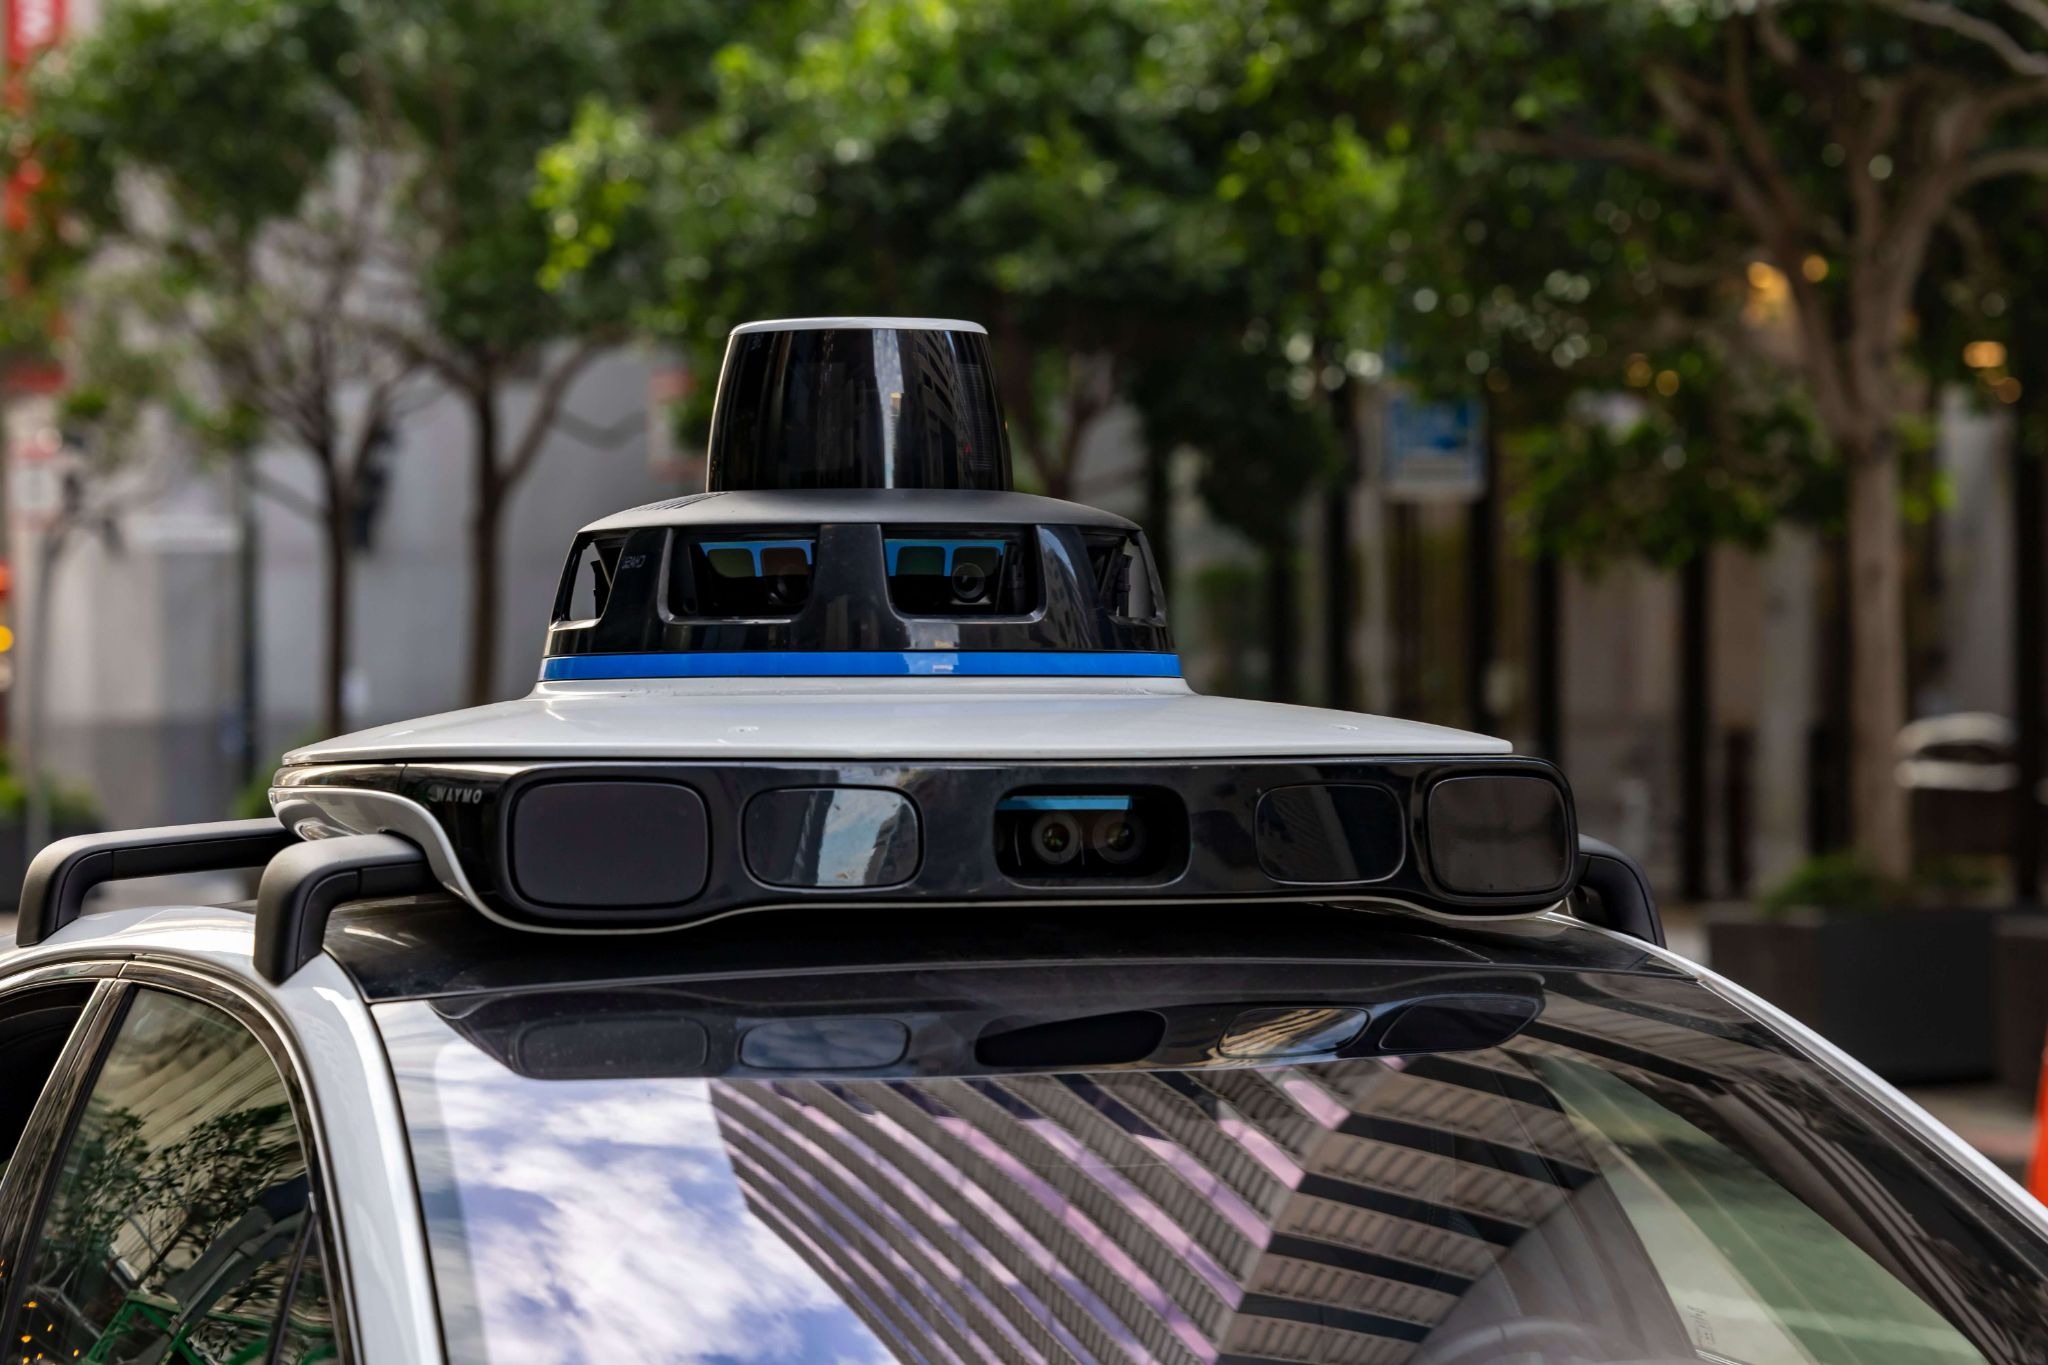
Taxi companies already do many of the things that would still be needed with an autonomous fleet. They maintain cars, deal with insurance and incidents, provide customer support and make sure enough vehicles are available. Some also already have their own depots, charging infrastructure or maintenance partners.
One possible model can already be seen in Zagreb. A local company owns and operates the autonomous fleet, while a larger ride-hailing platform brings customers. In the future, an existing taxi company could potentially have a similar role. Instead of managing cars and drivers, it could manage autonomous cars that receive bookings through a larger platform.
This does not mean platforms such as Uber will always rely on other companies to own the cars. Uber’s 2026 agreement with Rivian includes up to $1.25 billion in milestone-dependent investment and says that Uber or its fleet partners may purchase the autonomous vehicles. Uber is also developing infrastructure for autonomous fleets. Different ownership models are therefore possible.
Autonomous vehicles could also become interesting for rental and car-sharing companies, although this is probably further in the future. These businesses already manage vehicles, maintenance, cleaning, charging, bookings, customer accounts and payments, so much of the practical work is similar.
Autonomous driving could also change how rental and sharing cars are moved. Today, an employee may need to drive a car from one location to another. In the future, the vehicle could potentially do this itself within an area where autonomous driving is approved. It could even become possible for a rental car to drive itself to a customer’s pickup point.
Without drivers, it becomes especially important to understand how much time each vehicle is actually working. Every hour spent charging, being cleaned, waiting for maintenance or simply sitting unused means less time carrying paying passengers.
Some useful KPIs could be available hours per vehicle, paid trips per vehicle each day, revenue per available vehicle/day, empty kilometres, charging and maintenance downtime, cost per trip and incidents that need human help. These are most popular robotaxi industry KPIs of what a company could measure during a pilot.
For example, if cars spend too much time waiting to charge, the charging setup may need to change. A lot of empty kilometres could mean the cars are not in the right places, while too much maintenance downtime could make a vehicle more expensive to operate.
For either model, the business case depends on the partnership terms: who finances the vehicles, who carries the risk when demand is low, and how revenue and operating costs are shared. Operators should assess what remains after vehicle financing, insurance, charging, maintenance and partner fees. Depots, local service teams and reliable fleet availability could make an operator a valuable partner, but profitability still needs to be demonstrated.
One option for taxi fleets would be to work with an autonomous driving company and a larger ride-hailing platform. The local company could own or manage the cars and take care of the fleet, while customers book their rides through the larger platform.
Another option could be possible in cities where large ride-hailing platforms are not present or have limited coverage. A local company could work with an approved AV provider while using its own app, bookings, payments, customer support and fleet management.
In both cases, a company cannot simply buy autonomous cars and start offering rides. The technology needs to be approved, and local rules have to allow the service. These rules will also be different across Europe. Great Britain, for example, introduced its Automated Passenger Services permitting framework in 2026. Services similar to taxis or private hire vehicles need consent from the relevant local authority, while responsibility for the autonomous driving technology and the passenger service are treated separately.
A company does not need to have autonomous cars today to start preparing. A good first step is understanding the current fleet in detail – what each vehicle costs, how many hours it is available, how much time it spends charging or being repaired, and when cars are used the most.
Charging, cleaning, maintenance and depot processes are also worth looking at because all of these will still be needed with autonomous vehicles. A company interested in an AV pilot can then choose a location and use case, look at the local permit process and start talking to autonomous driving technology providers.
The software will also need some preparation. Customers still need to book and pay for rides, while the company needs fleet information, customer support, reporting and connections between its own systems and the AV technology. Starting with a small pilot makes it possible to test all of this before trying to build a larger service.
ATOM Mobility already provides many of the software functions used by taxi, ride-hailing, rental and sharing companies, including customer apps, bookings, payments, fleet management, maintenance tasks, analytics and APIs. Its ride-hailing software includes passenger and driver apps, dispatch, payments, fleet data, analytics and integrations. The ATOM Mobility API can also exchange data about vehicles, bookings, rides, payments, telemetry and maintenance tasks.
ATOM Mobility does not provide autonomous driving technology. This would come from a specialised AV company, and each project would have its own technical requirements and local approvals. For an AV pilot, ATOM Mobility could work with the fleet company and AV provider on the rider experience, integrations, fleet management and the data needed to measure how the pilot is working.
If you operate a taxi, rental or sharing fleet and want to explore an AV pilot, ATOM Mobility can help plan the booking and fleet-management setup, integrations and metrics you would need to test together with an AV technology partner.
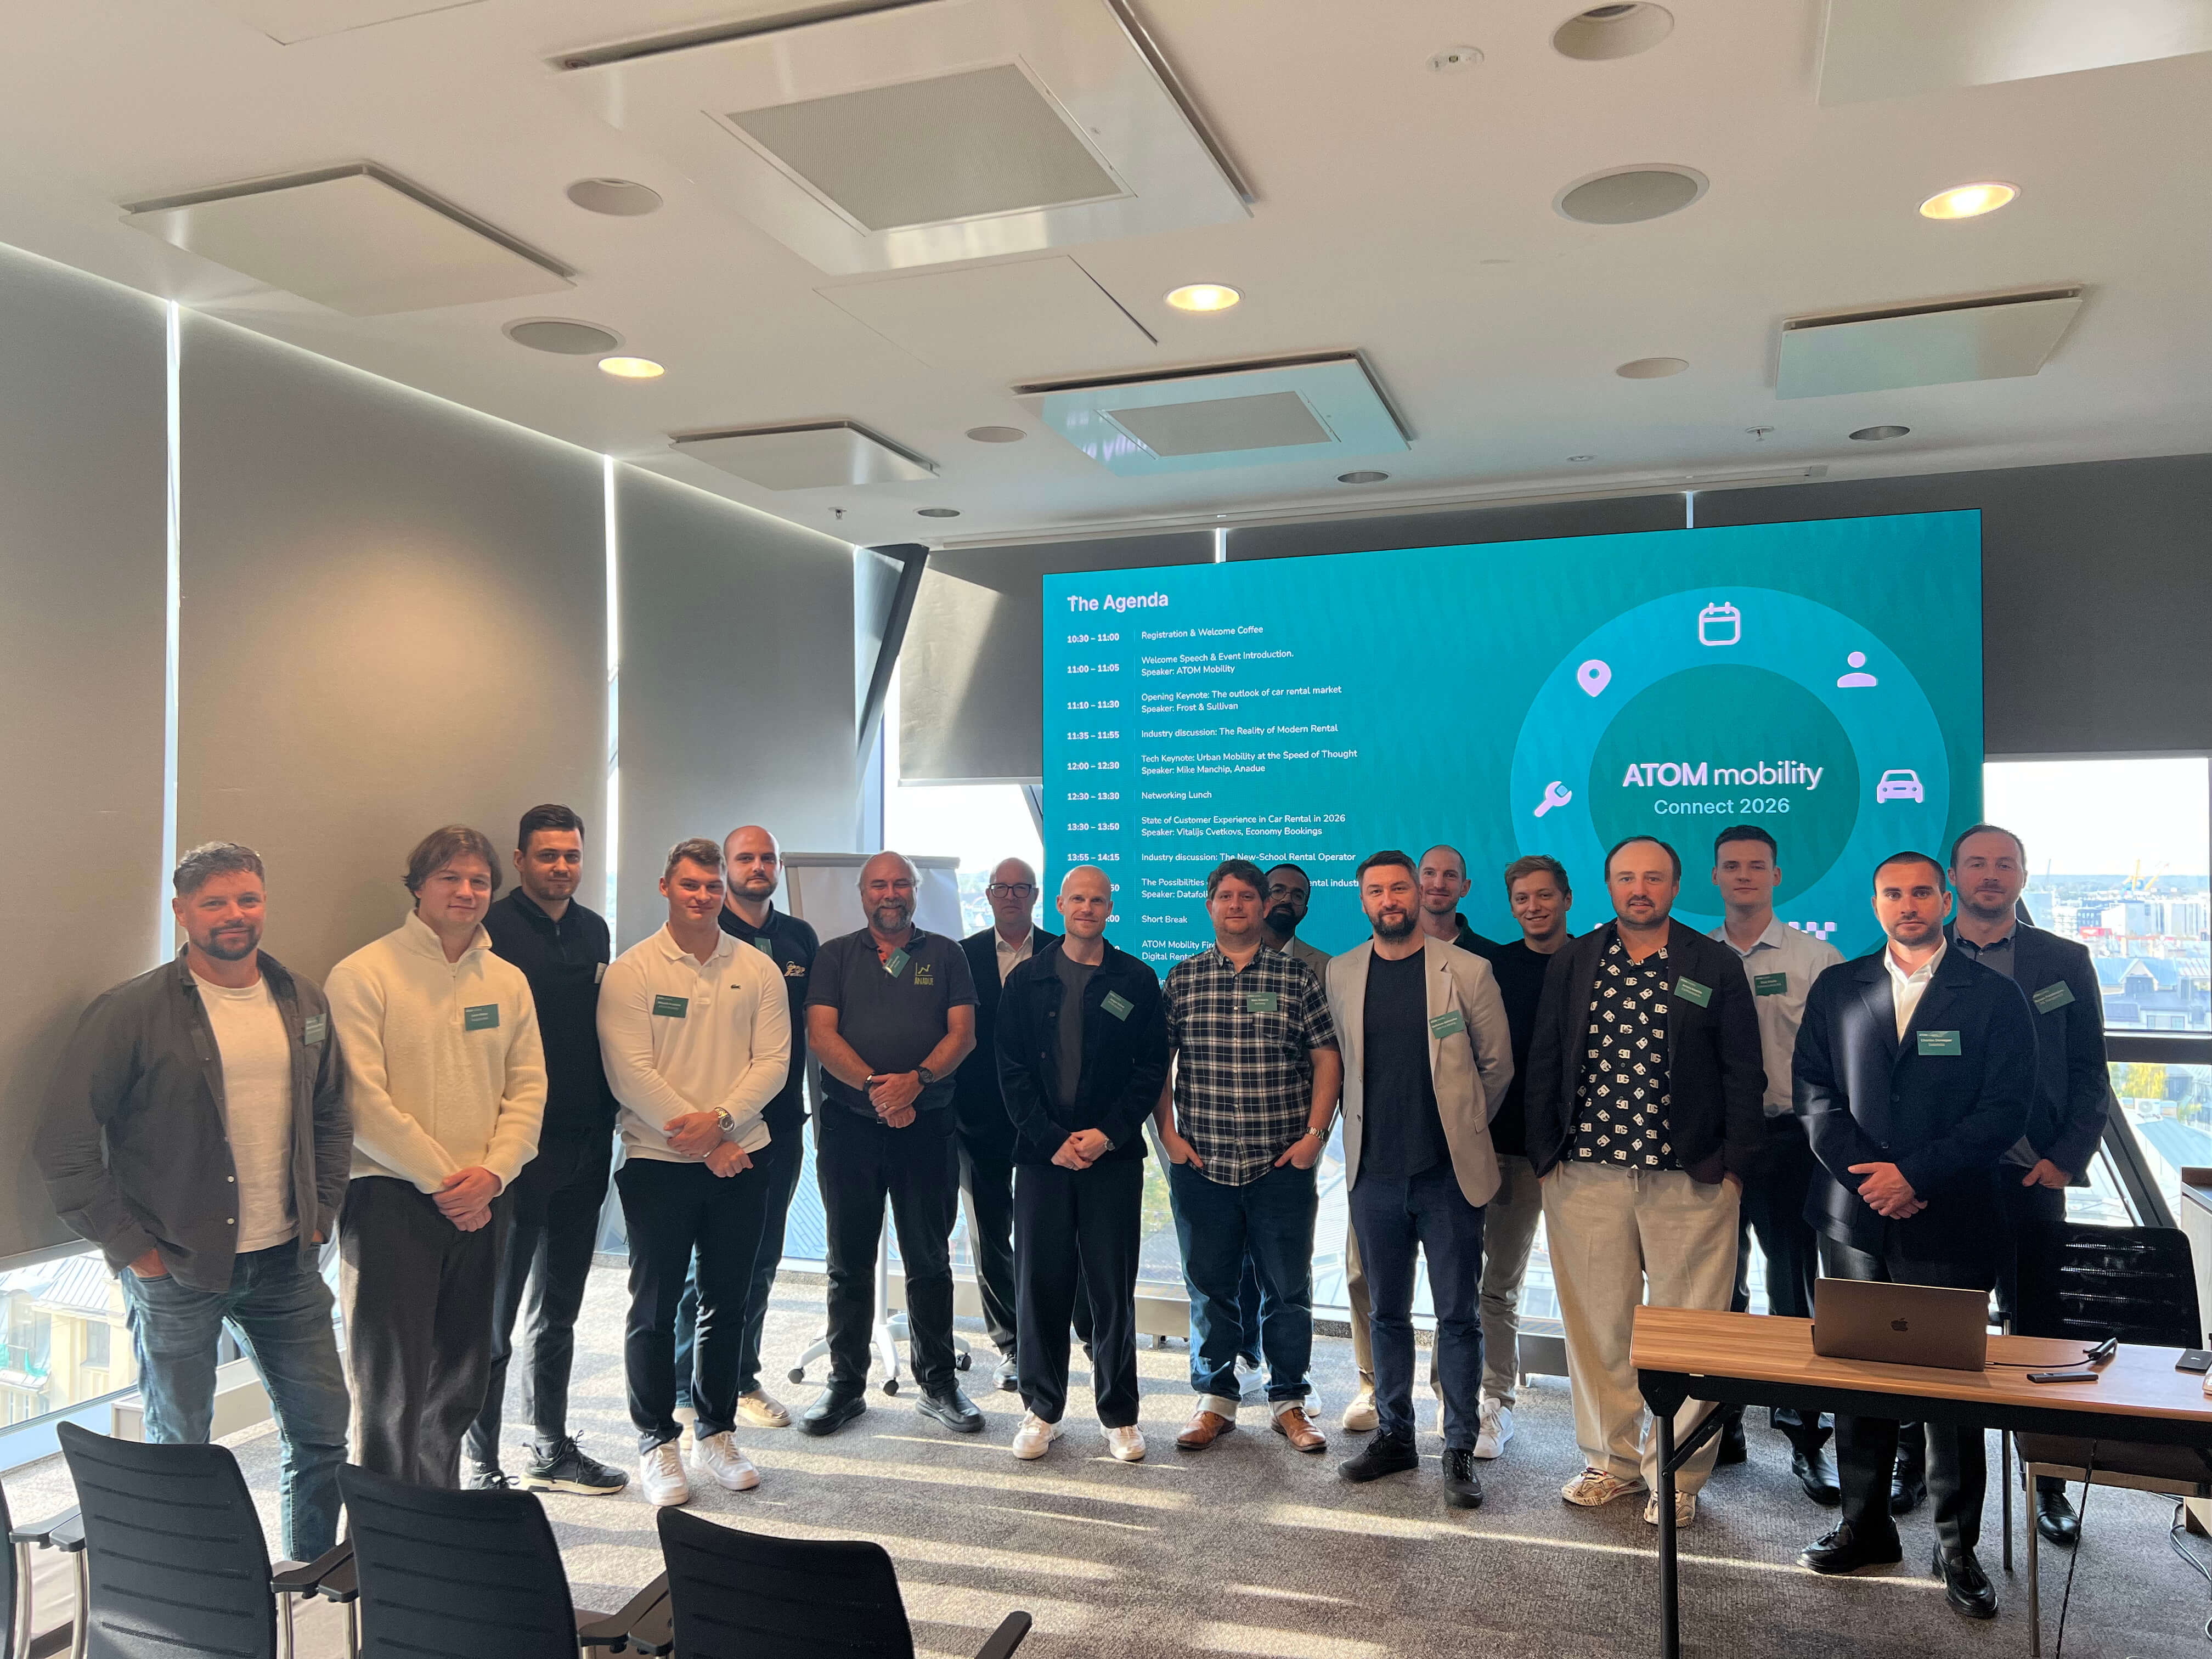
ATOM Connect Rental 2026 brought rental operators, aggregators, and technology partners together in Riga on October 8 to discuss the future of vehicle rental. Key topics included margin pressures, customer friction, data-driven fleet decisions, insurance, and keyless operations. The central takeaway: growth depends on improving customer experience and fleet efficiency, with practical steps operators can take today.
On October 8, 2026, we gathered on the panoramic top floor of the AC Hotel by Marriott in Riga for ATOM Connect Rental 2026.
Following the community-first approach of our past mobility summits, our goal for this edition was simple: avoid the noise, generic pitches, and sales booths of conventional trade shows. Instead, we brought together an intimate room of car rental operators, regional franchise managers, aggregators, and technology pioneers to have an open, unfiltered conversation about where vehicle rental is heading and what it actually takes to get there.
The day’s agenda reflected that intent. Rather than treating digitization as a buzzword, the sessions explored the operational realities of the industry: from global macroeconomic forces to the high-stakes friction points at the physical rental desk.
Here is a recap of the key discussions, industry data, and takeaways from the summit.
Opening the morning keynotes, Frost & Sullivan set the strategic foundation by examining how vehicle rental is shifting from an asset-heavy model to a digitally enabled, flexible mobility ecosystem.
Their analysis highlighted three forces currently reshaping the industry:
The main takeaway from their presentation was clear:
"The winners will not simply manage more vehicles - they will manage the customer, fleet, and ecosystem more intelligently."
Looking ahead, Frost & Sullivan stressed that future value will come from experience-led rental models (low-touch, personalized journeys), commercial and LCV subscriptions, and ecosystem partnerships that maximize revenue per vehicle, customer, and trip.
Following lunch, Vitalijs Cvetkovs, Head of Commerce at EconomyBookings.com, delivered a refreshingly candid, data-backed session on why car rental remains the most friction-heavy customer journey in travel.

While booking a flight or hotel is relatively straightforward, car rental forces the customer to decode dozens of brands, ACRISS vehicle codes ("or similar"), deposit rules, insurance tiers, and fuel policies. Drawing on data from over a million annual bookings, Vitalijs pinpointed the four friction points where the industry loses customers:
Vitalijs concluded with a crucial commercial insight: In the era of AI and instant review summaries, poor customer experiences are instantly visible. Customer experience is the only sustainable retention driver, and aggregators and operators must work together to absorb friction rather than pass it on to the traveler.
Beyond macro trends and customer journeys, the technical sessions focused on practical tools operators can deploy today:
Closing out the afternoon, ATOM Mobility hosted a fireside session with INVERS to discuss the nuts and bolts of deploying "digital rental-ready" fleets.
The session focused on practical execution. Using real-world examples, the discussion highlighted how telematics, CAN-bus hardware, and remote immobilizers enable traditional operators to launch virtual stations, service off-airport locations, and automate replacement vehicle workflows without increasing staff overhead.
The key takeaway: modernizing a fleet does not require an immediate, risky transition away from the counter. Hybrid operations allow established rental businesses to introduce 24/7 keyless handovers alongside their standard operations.
The Value of the Closed Room
As presentations concluded and conversations moved into the evening networking mixer overlooking Riga, the feedback mirrored what made previous ATOM Connect events special: the value is entirely in the room.
By capping attendance and curating an audience of active industry operators, conversations went deeper than high-level presentations. A sincere thank you to all our speakers, partners, and guests who joined us in Riga. The vehicle rental sector is evolving quickly, and we are proud to provide the space where the industry comes together to map out what comes next.
Stay tuned for our next ATOM Connect events by following us on LinkedIn!
Use test credentials to log in - Phone number: +1 123123123, Code: 777777
Driver App demo credentials - Email: test@atom.com, Password: driver