How to find profitability in the e-scooter sharing industry – a conversation with Bullride
September 8, 2022
min. read

When it comes to the future of e-scooter sharing, there are some pretty conflicting opinions out there. Some say it's the future of micromobility, others are less optimistic.
Ultimately, the success of scooter operators all depends on their ability to find profitability.
Let's be honest – this industry has higher-than-average overhead costs. The hardware itself is a major investment, and profits are further seeped by the maintenance workforce, storage, relocation costs, and new regulatory requirements that are regularly introduced.
But profitability is possible.
We spoke to Heiko Hildebrandt, co-founder of Bullride, which helps mobility companies offload their assets from their balance sheet to keep them in the black.
The economy is just starting to stabilize as we exit the Covid slump and enter the new normal. How did Covid affect the micromobility sphere?
A study published in Bloomberg found that monthly ridership fell drastically in 2021, but made a comeback in 2022 when people returned to office.

Source: Bloomberg
Now, that's using US-based brands as a model.
Heiko Hildebrandt shares that the scooter operators he's worked with have experienced a similar effect:
“Corona was the greatest fuel you could pour onto the micromobility fire. During Corona times, people hardly used public transport, and most people switched to scooters. We saw two of the biggest micromobility brands in Europe, Bolt and Tier, raise record-setting VC investment at the end of 2021 – totaling 1.4B EUR – a clear sign of traction. And since Covid has ended, we've seen a 30%-40% slump in demand. So was Covid bad for business? Not according to my perspective.”
However, according to Heiko, the real challenge is to make the unit economics work. Because the question is not about whether the product is in demand. The question is does it make sense from a business perspective.
The scooter industry, while in demand, must face challenges that directly impact their unit economics. For some businesses, it pushes them over the edge and drives them into insolvency.
By knowing what those challenges are, scooter businesses can better set up their business models to protect their profitability.
In order for a scooter's lifetime to be profitable, it has to be in use for at least 2 seasons – some even say, for 4 years. That means that the scooter has to be durable, easily maintained, with cost-efficient replacement parts.
“Scooters are usually imported from abroad (mostly China), and shipping costs are now 8x higher than they were two years ago. The costs of electronics components are ever increasing.”
Jürgen Sahtel, Manager of the ATOM Vehicle Marketplace, agrees that the prices have gone up over the past two years.
“For example, hardware prices for the new Segway models have increased more than 40% over the last 16 months. And this trend is across all manufacturers – new scooters could be obtained starting from 650EUR and up, while more advanced models readily available in EU are priced at around 1000EUR per unit.”
The hardware is one of the biggest up-front investments that a scooter operator faces. But it's also critical to balance cost with quality, as you need to be so resilient that it can withstand public use over the course of 2-4 years.
When the e-scooter sharing industry took off, the industry was so fresh that there wasn't any regulation in place to keep it in check. It was the wild west, and operators were able to take advantage of the regulatory grey area.
Now, municipalities are starting to crack down on the industry and putting laws into place. Regulation, overall, is a good thing. However, the way it's done now shows a lack of understanding about the unit economics and its regulation that is being enacted.
“Most municipalities are limiting the size of a fleet that one scooter competitor can have. Their goal is to reduce the amount of scooter clutter on the streets. But that number is often too low to ensure what we call “natural floating” – the process of humans moving the scooters around the city. This puts a larger strain on relocation and charging teams.”
Other burdens placed on scooter brands is the stricter demarcation of allowable parking zones. This is a factor that impacts relocation teams – those responsible for bringing scooters from less popular zones back to city centers and transport hubs. Additionally, mandatory tenders with the municipality are usually offered only for one year, making planning rather difficult.
A new trend that Heiko mentions seeing from a regulatory perspective is the emergence of mandatory insurance.
“Scooters used to be classified as bikes, and thus, similarly regulated. Now, they're being reclassified as motored vehicles, which have different regulatory requirements, including mandatory insurance.”
This further skews the unit economics of each ride.
On the other hand, regulation can also play an enabling factor. Heiko shares that if tenders could be extended for, say, 3 years, it could provide scooter brands with planning stability. If municipalities limited only 2 competitors in a city, this would ensure enough demand to make the unit economics work.
Heiko believes that the future lies in the shared economy. He's among the 4 co-founders of Bullride, an investment platform that shoulders the burden of the hardware investment and splits the scooter rent with the operating brand.
How does it work?
The idea works for a number of reasons.
The operating brand then may use a leading vehicle-sharing platform ATOM Mobility, to fast-track their time to market. ATOM takes profitability even further with its unique pricing model. Instead of the common model of cost-per-vehicle, ATOM uses a cost-per-ride model. That means that if you have less demand (and as a result, less income) in a certain month, then you pay less for use of the ATOM platform.
But scooter sharing is just the beginning. This same model, Heiko believes, can be applied to e-bikes, e-scooters, carsharing, even wind turbines and major investments like that. Why shouldn't a community be able to jointly invest in and co-own the infrastructure that they need to live?
This is a unique model that hasn't been commonly seen elsewhere. It's more than just scooters – Bullride believes that at the heart of it, what they're doing is democratizing asset ownership.
If you're looking to launch or scale your own vehicle-sharing business, contact the ATOM Mobility team to learn more abut this opportunity.
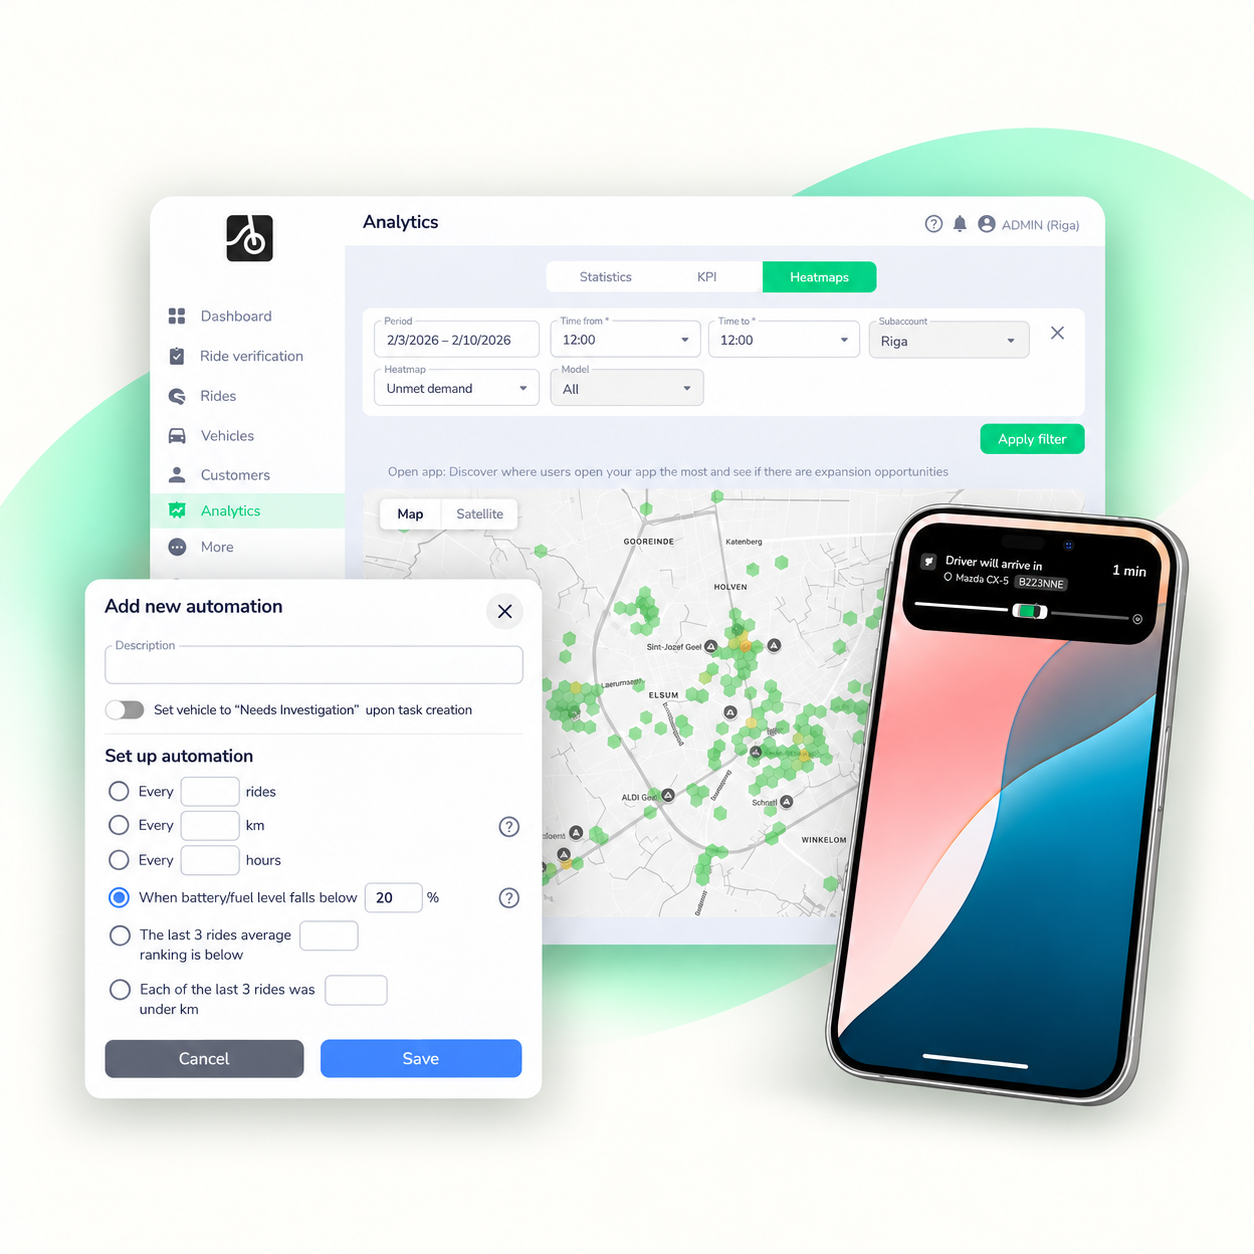
🚀 ATOM Mobility ships 7-15 new features every month, alongside smaller improvements and fixes. Explore five recent highlights: unmet demand heatmaps, automated fleet tasks, field-team performance tracking, new subscription types, and lock-screen ride updates - helping operators run more efficient fleets and improve the rider experience.
Knowing where customers need vehicles, keeping field teams productive, and giving riders reasons to return are everyday priorities for mobility operators. Every month, ATOM Mobility ships 7-15 new features, alongside smaller improvements and fixes. Here are five highlights from our recent releases - and how they can help operators improve fleet performance and the customer experience.
A customer opens your app, finds no vehicle nearby, and leaves. Your ride history alone won’t show you that missed opportunity.
The Unmet Demand heatmap highlights areas where users open the app but cannot find an available scooter, bike, or car within 1000 metres radius. Beyond colour-coded hexagons, on zoomed in view it shows the number of unique users who searched for a vehicle in each area without finding one nearby.
Use these insights to identify gaps in fleet coverage, prioritise rebalancing, and assess potential parking locations. Alongside seeing where rides happen, you can now understand where potential demand goes unmet.

Keeping a fleet ready for customers means staying on top of maintenance, charging, refuelling, and service quality. As your fleet grows into hundreds of vehicles, manually tracking when each vehicle needs attention becomes increasingly time-consuming.
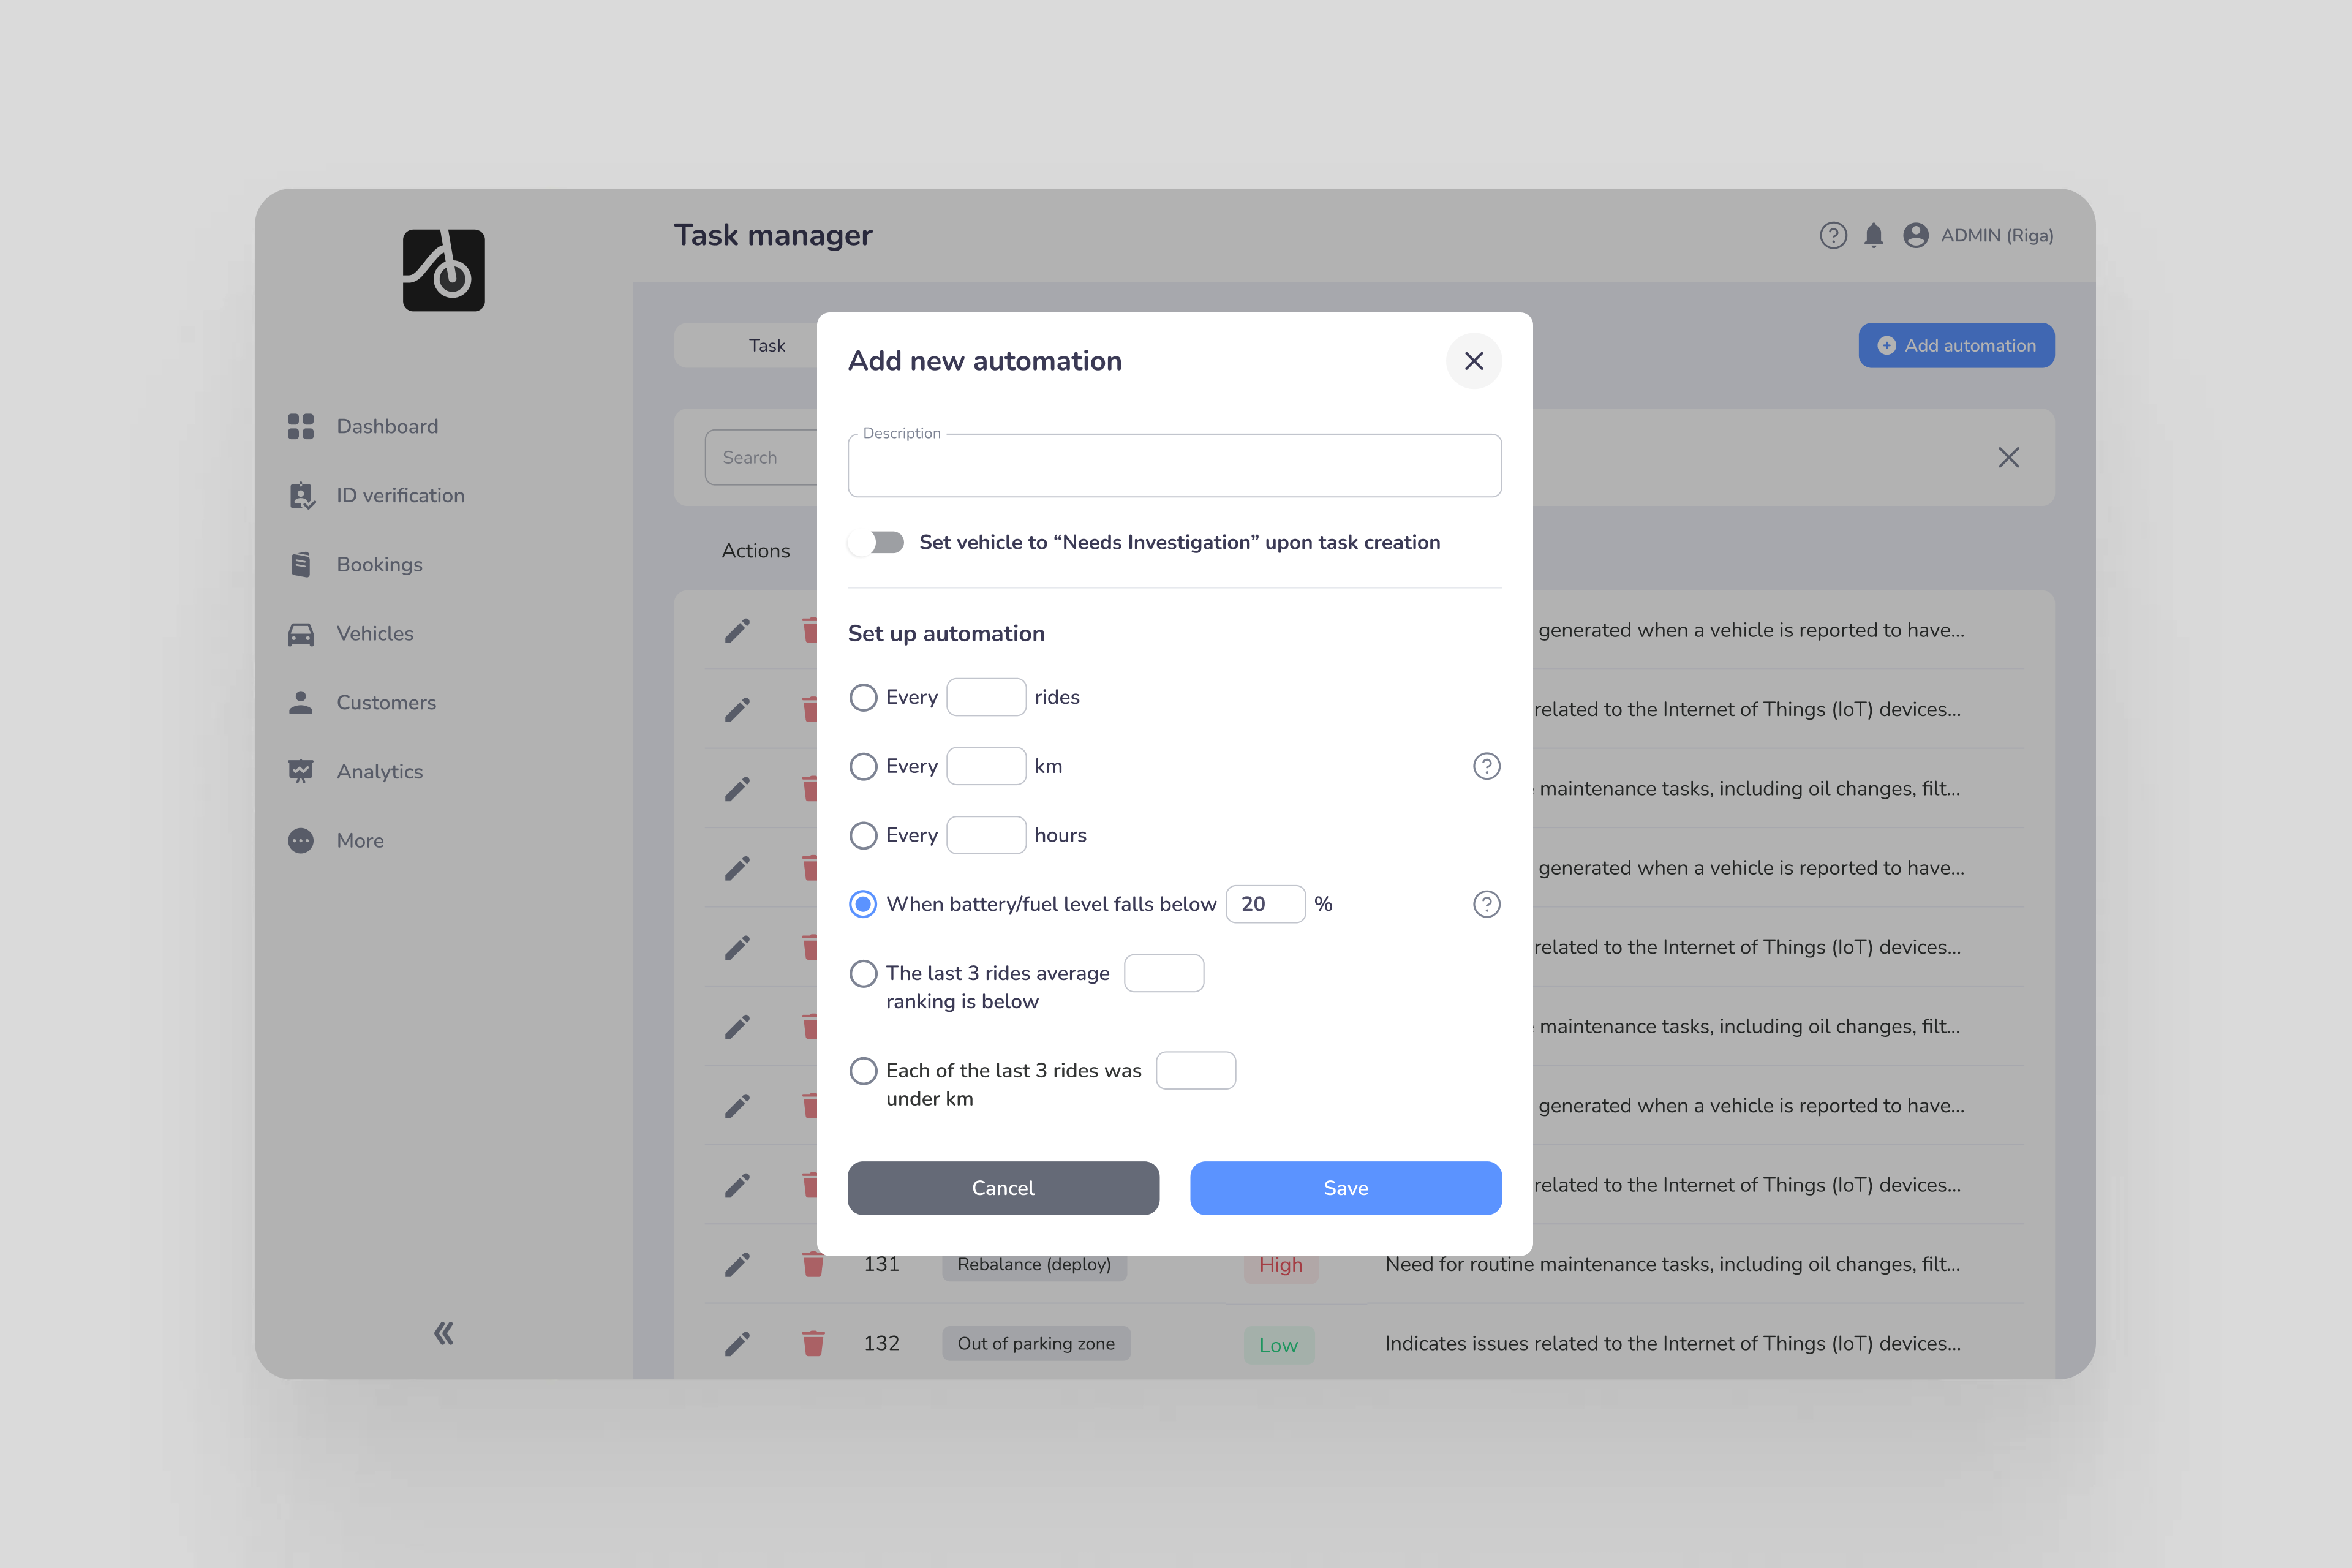
Task Manager automations turn vehicle usage, condition, and ride feedback into actionable tasks. Operators can configure tasks to be created:
These rules can support routine maintenance, trigger charging or refuelling tasks, and flag vehicles for inspection after low ratings or unusually short rides. For rebalancing tasks, if a customer uses the vehicle before collection, the task is automatically removed. This reduces manual monitoring and helps your team respond to vehicles that need attention.
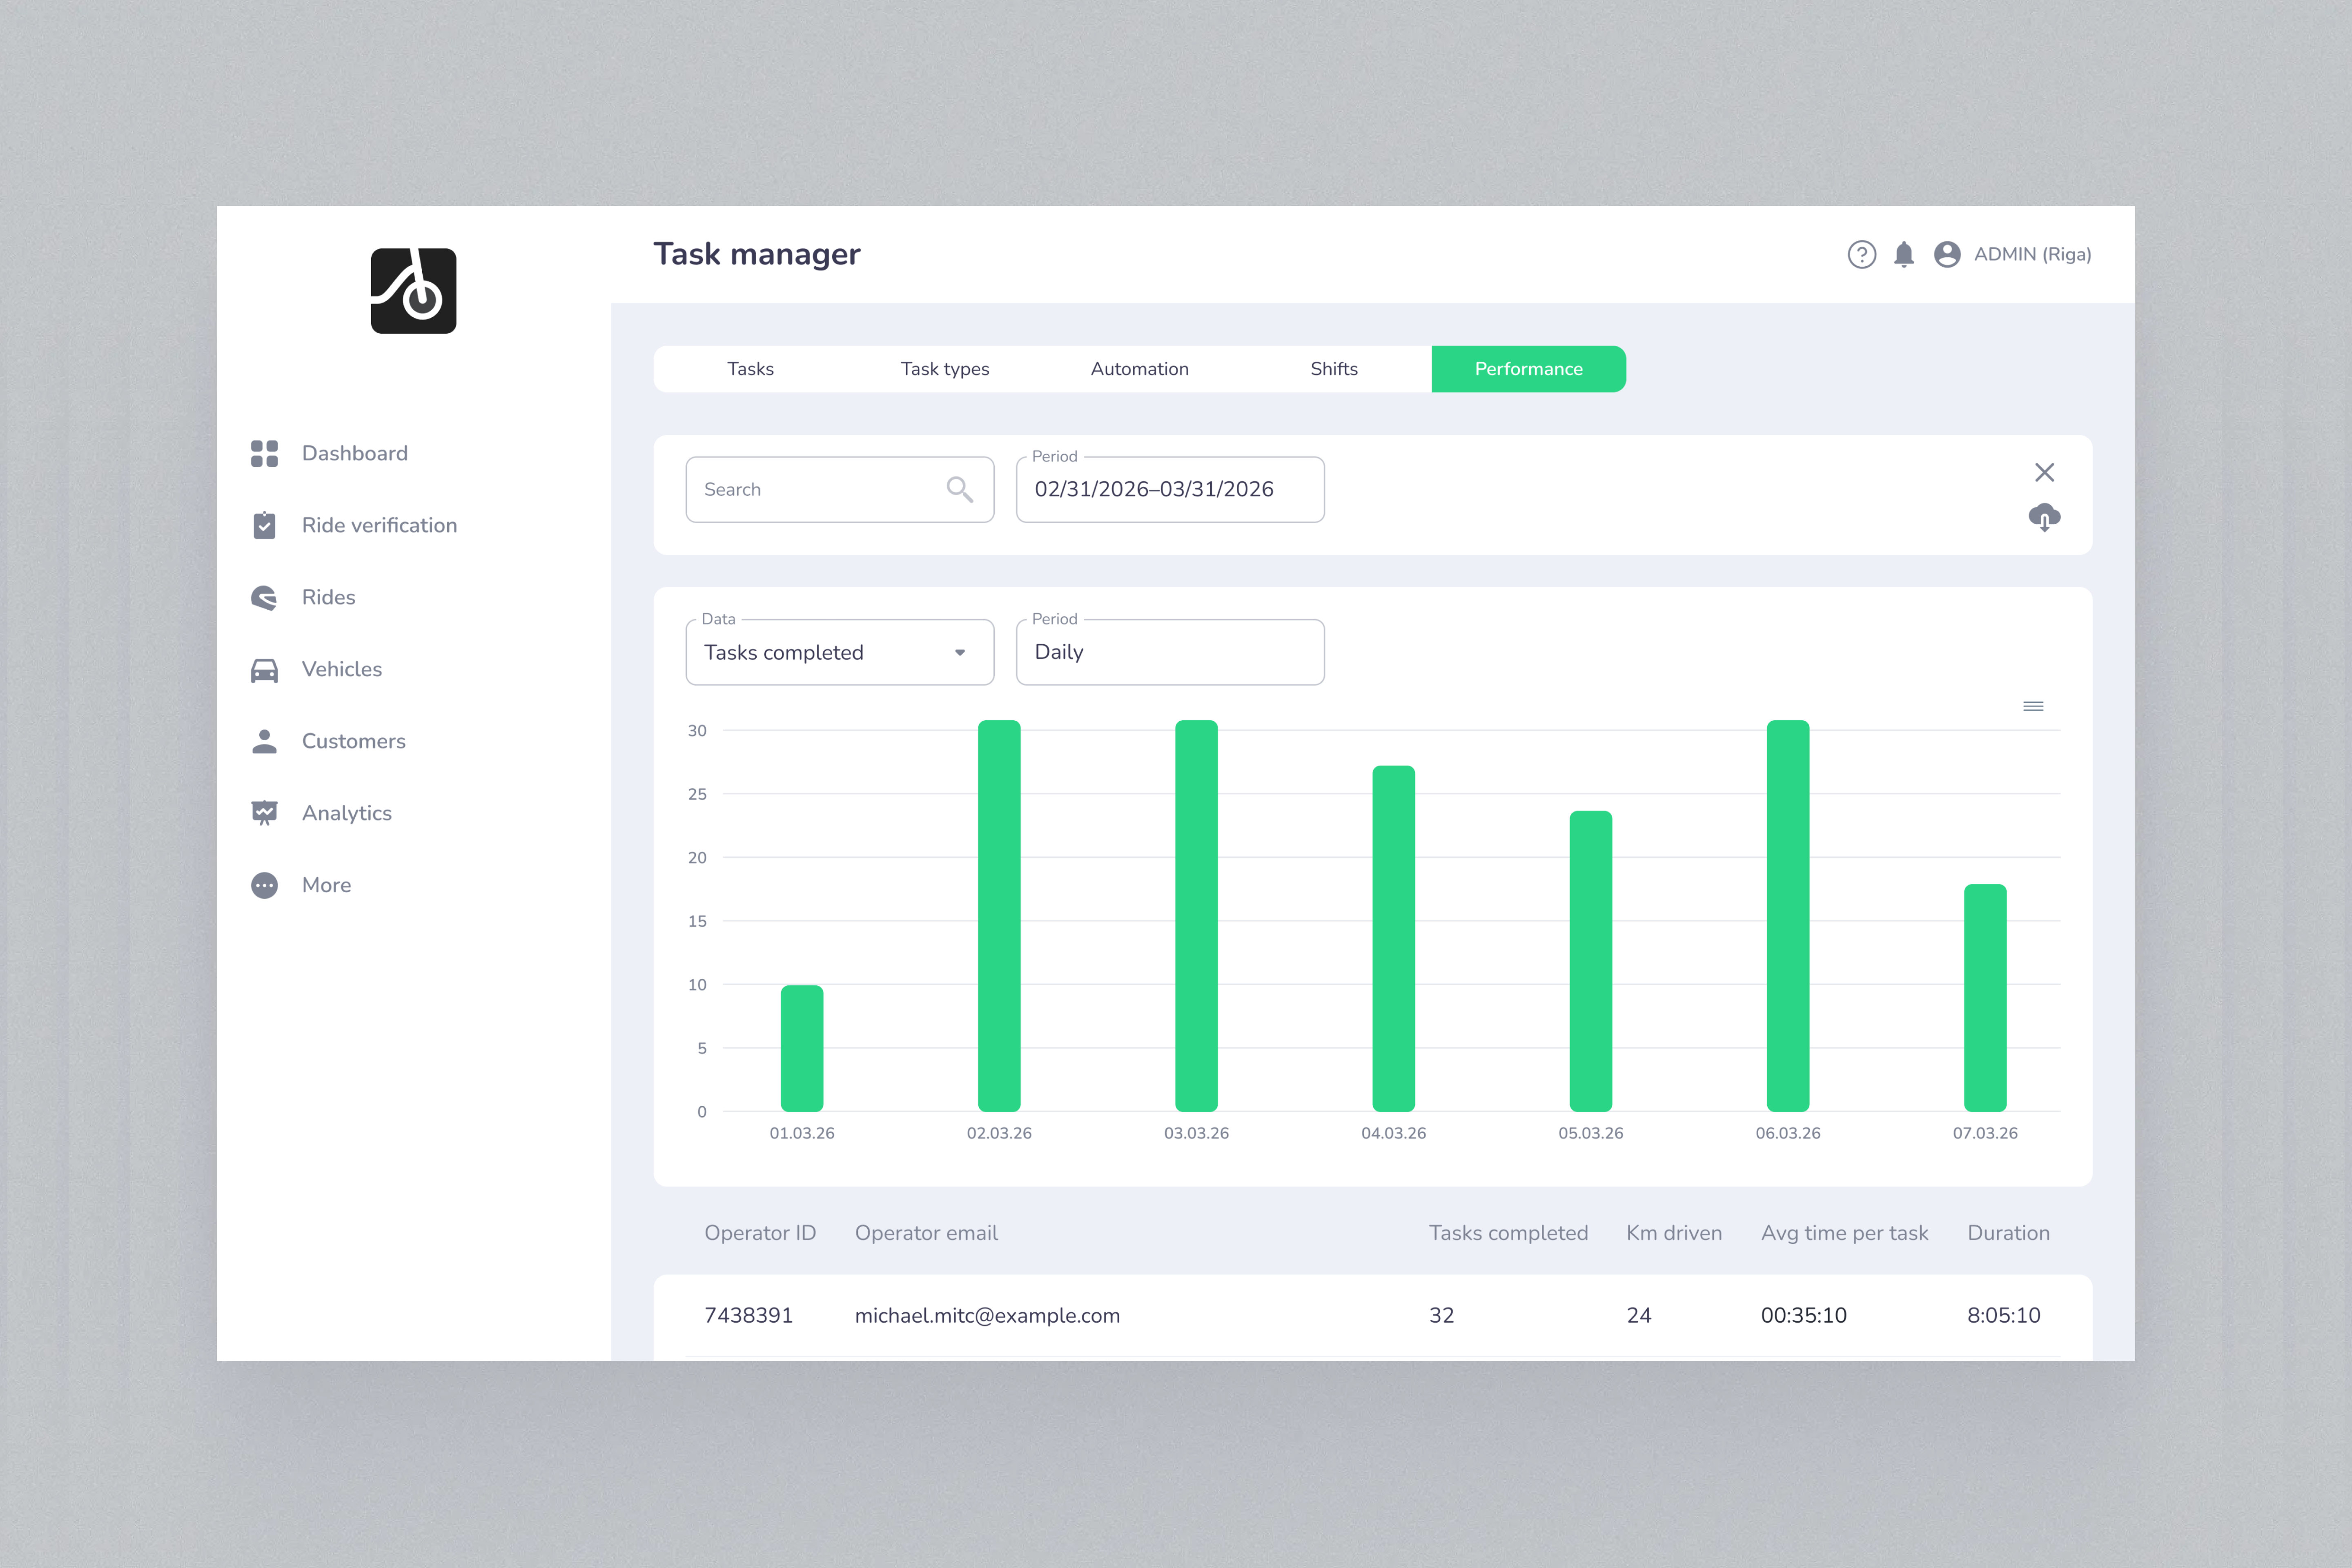
How long do tasks take? Where does your team spend its time? Which operational bottlenecks need attention?
New Shifts and Operator Performance views give vehicle sharing and digital rental operators visibility into shift status and duration, distance driven, completed tasks, and average time per task.
Managers can use these insights to investigate delays, improve routes, and identify training needs. For example, longer task completion times could prompt a closer look at travel distances, workload, or the processes used at each location. Comparing results alongside task types and working conditions helps turn performance data into practical operational improvements.
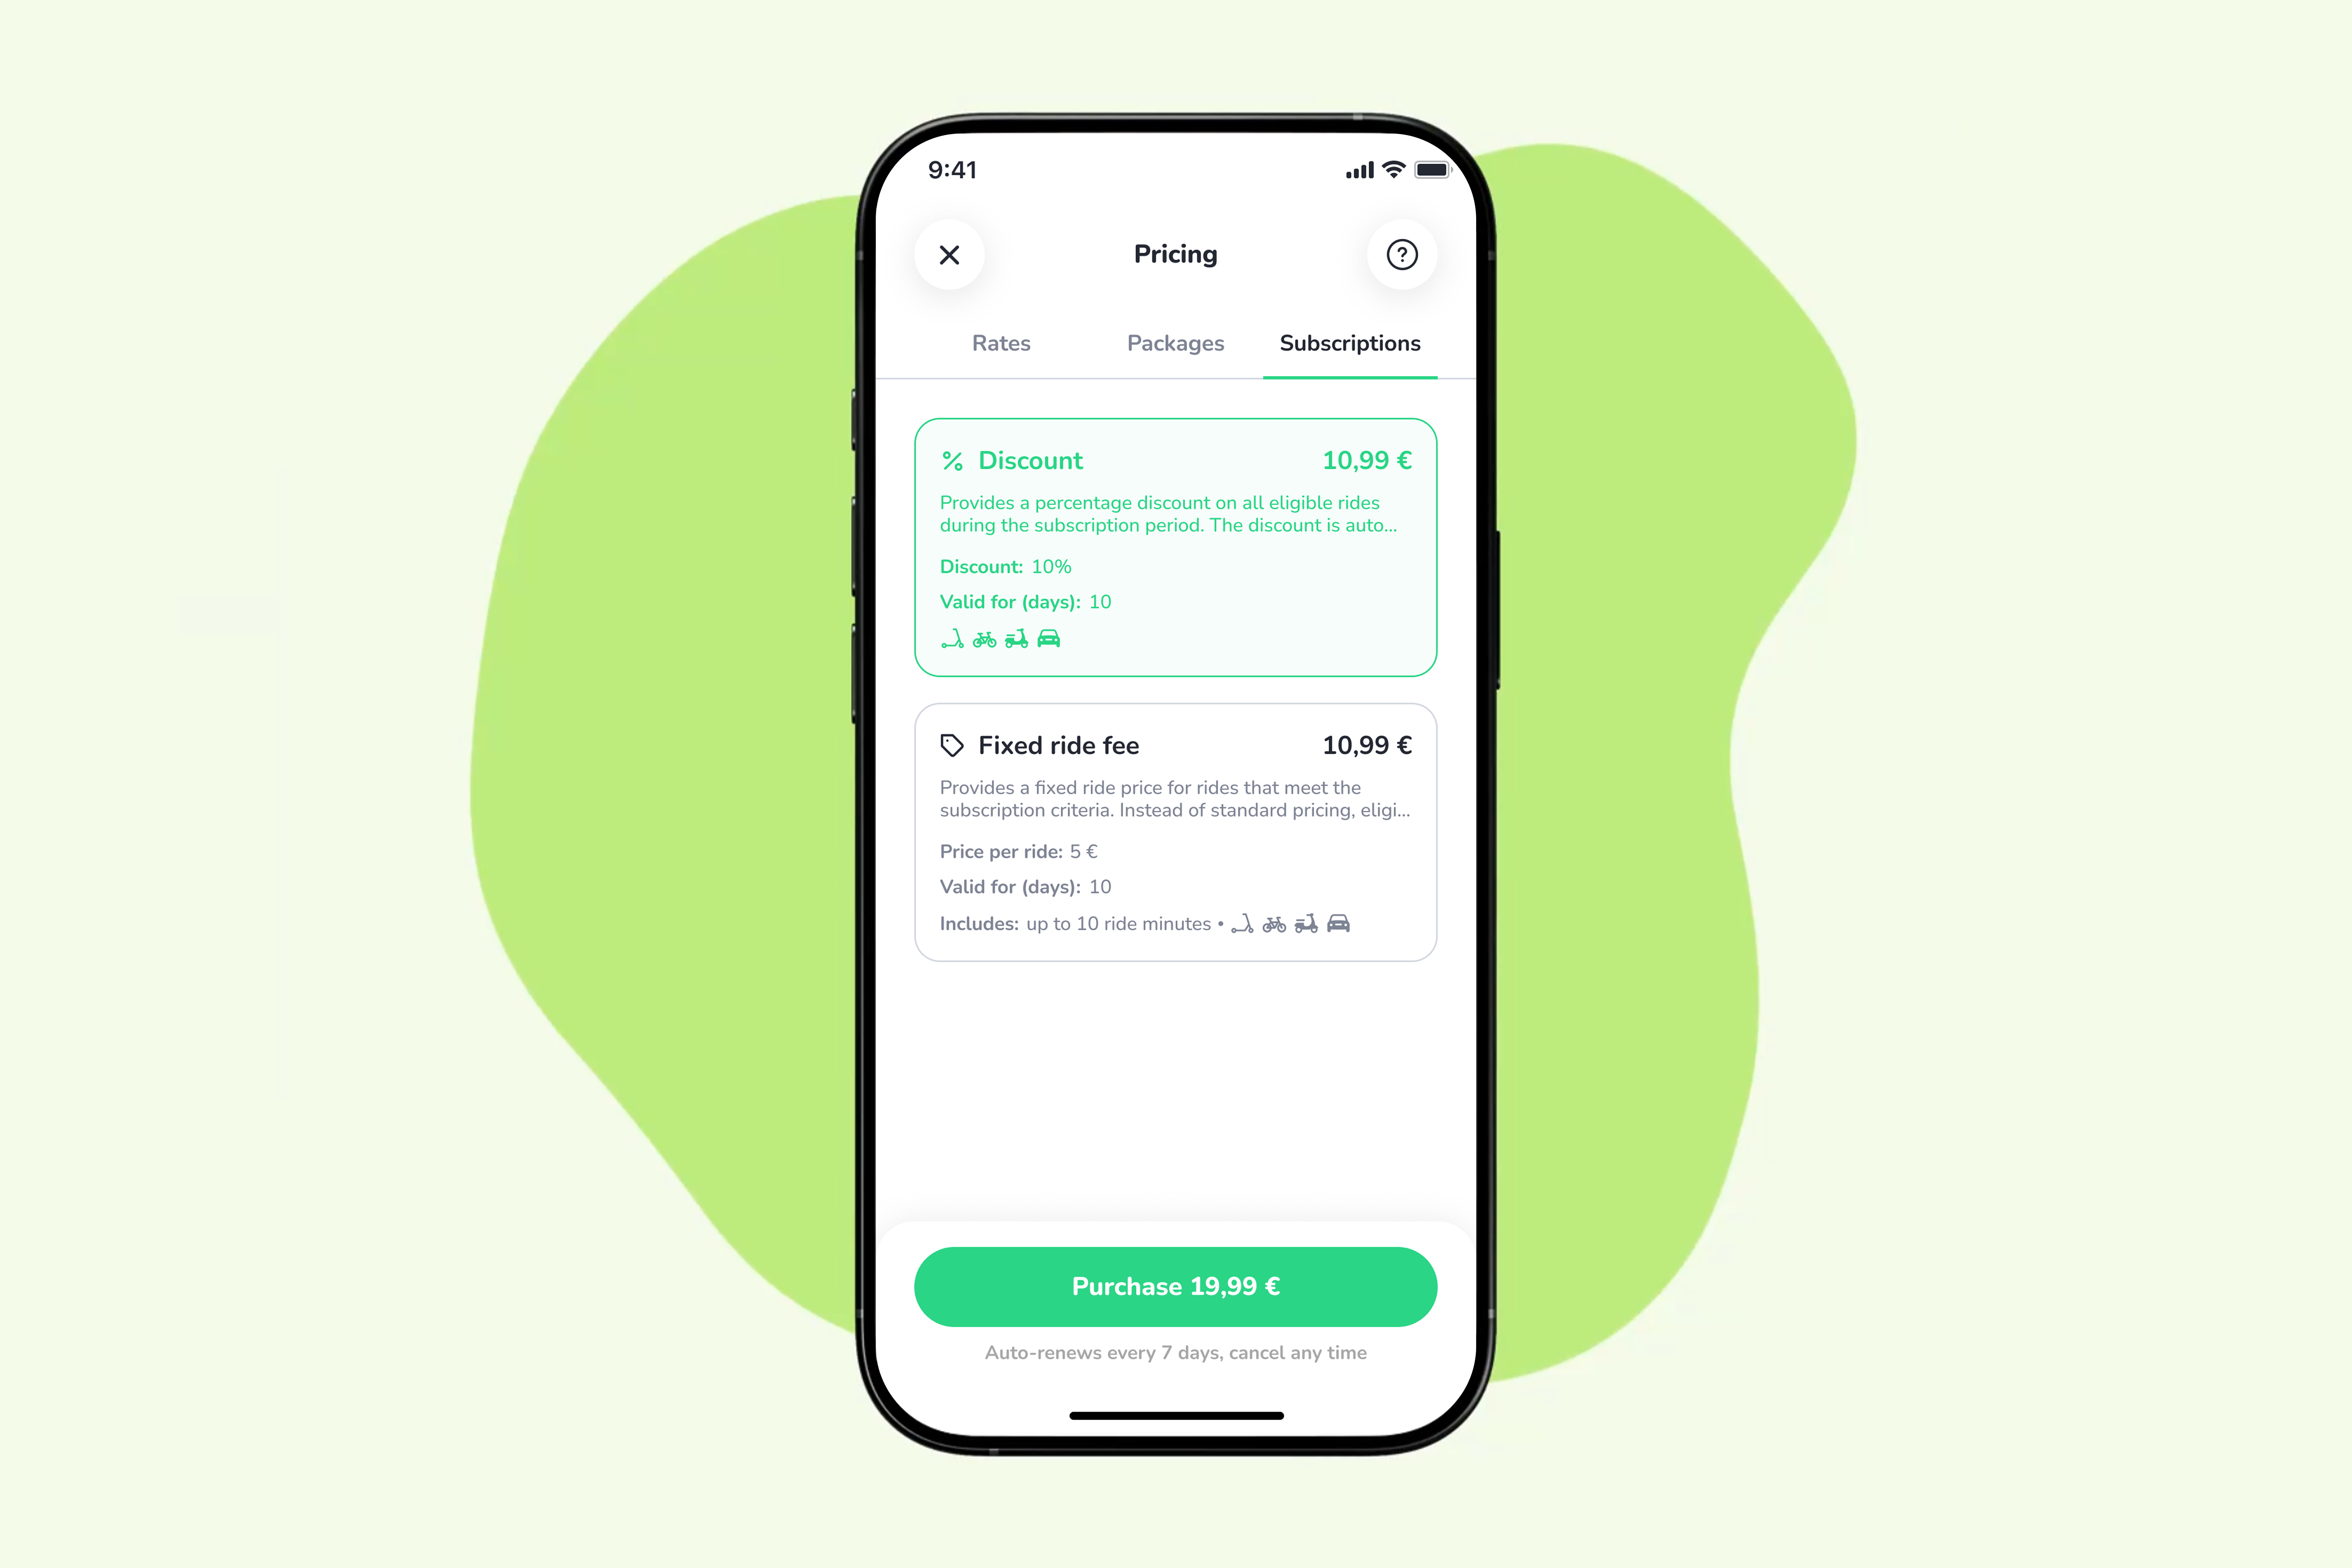
Different customers have different riding habits. Your subscriptions should reflect that.
ATOM Mobility now supports two additional subscription types:
These options let operators design offers around frequent riders and short-distance commuters. For example, you could offer subscribers a percentage discount on eligible rides or a predictable flat fee for qualifying short trips. Operators gain more flexibility to test offers that encourage repeat usage while fitting their pricing strategy.
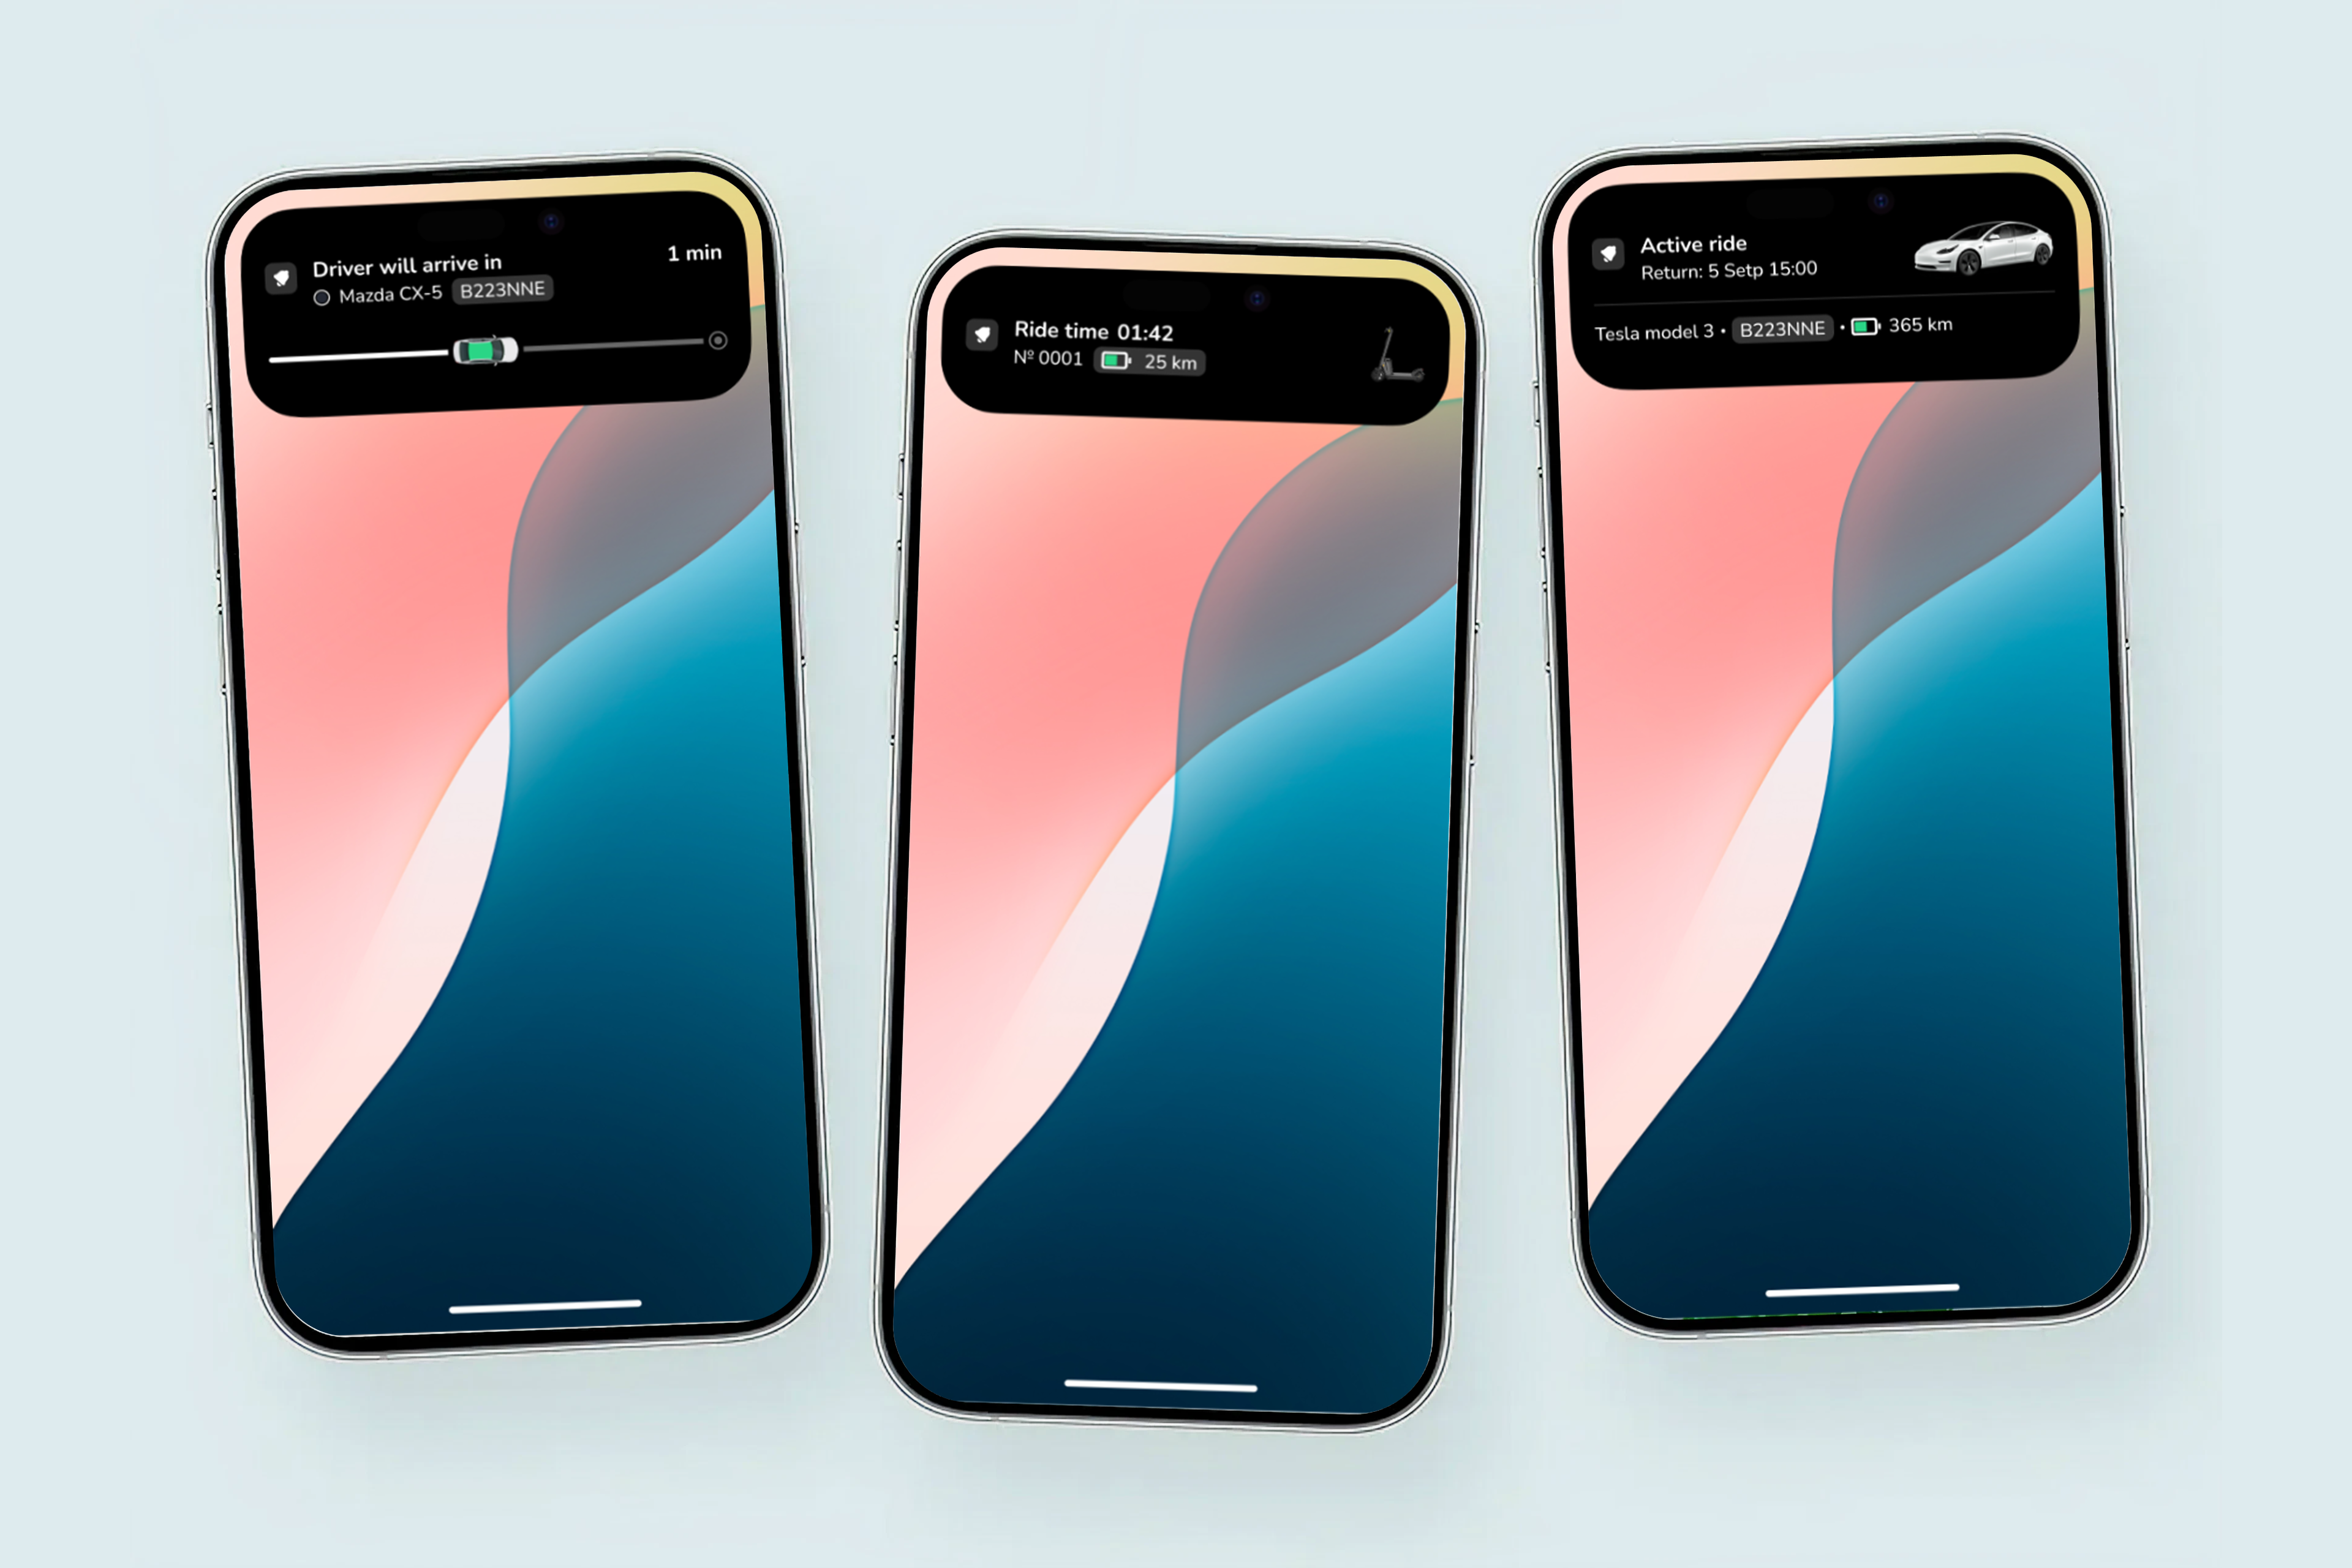
Checking an active trip should be simple.
Live Activity lets customers view key ride information directly on their phone lock screen without repeatedly opening the app. Depending on the service, this can help them follow an active ride or a driver’s arrival.
Making this information readily accessible gives customers a more convenient way to stay informed throughout their journey.
These five releases are part of ATOM Mobility’s ongoing product development, helping operators identify unmet demand, automate routine coordination, understand field-team performance, and improve the customer experience.
Exploring software for your mobility business? Book a demo to see how ATOM Mobility can support your fleet, team, and customers.
Explore more product updates at https://www.atommobility.com/atomupdates
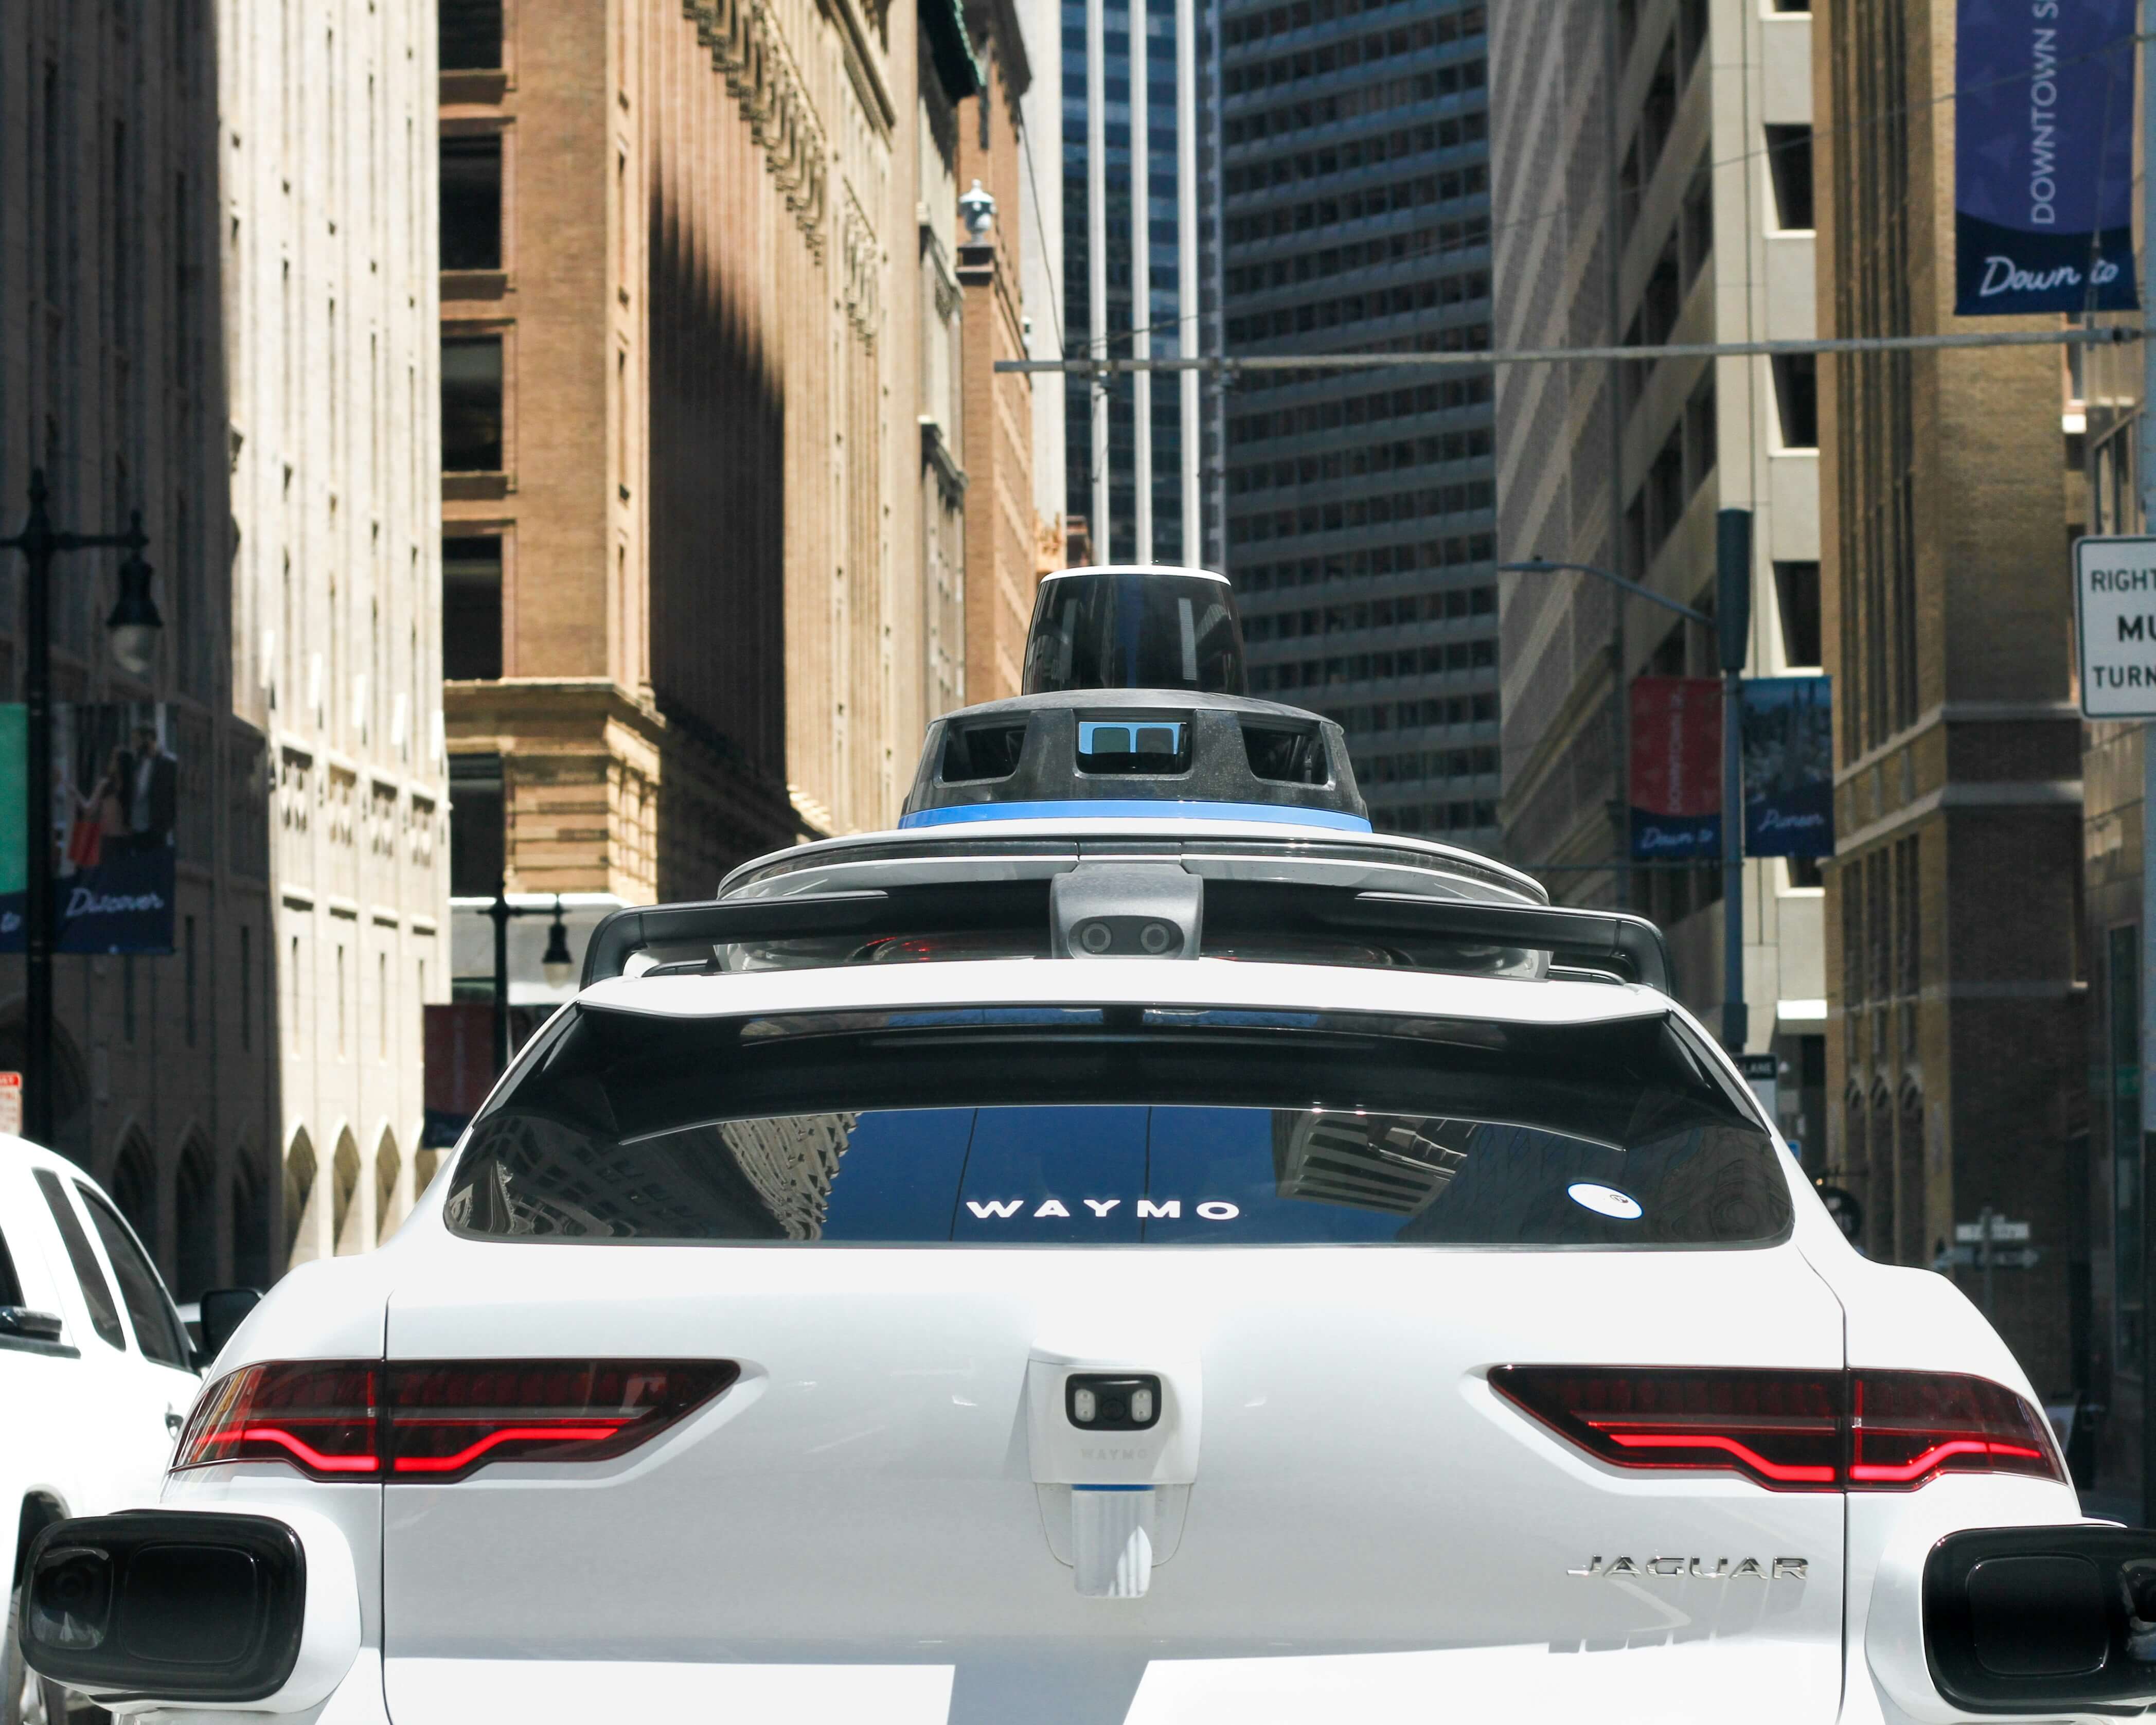
🤖 Who will actually operate Europe’s robotaxi fleets? Autonomous driving may remove the driver, but it doesn’t remove the work behind the car. Robotaxis still need charging, cleaning, maintenance, depots, customer support and someone managing the fleet every day. Early projects in Zagreb, Madrid and London illustrate different stages of deployment and how AV technology providers, fleet operators and booking platforms can work together. Taxi, rental and car-sharing companies already handle many of these tasks. What would it take to turn that experience into an autonomous fleet business?
For a taxi fleet owner, autonomous vehicles may seem to remove the most important part of the current business – the driver. But even without drivers, someone still needs to take care of the cars. They need to be owned or financed, charged, cleaned, inspected and repaired. Someone also needs to manage depots, deal with incidents, help customers and make sure enough cars are available.
The first robotaxi services and tests in Europe are already showing how this could work. The company that develops the autonomous driving technology does not always own or operate the cars. The app where customers book their rides may come from another company too. This could leave an important role for taxi, rental, car-sharing and other fleet companies that already know how to manage vehicles.
A taxi company today manages both cars and drivers. Drivers need to be recruited, scheduled, paid and supported. With a driverless fleet, these tasks would eventually disappear, but most of the work related to the cars would stay.
Autonomous cars still need charging or refuelling, cleaning, tyres, inspections, repairs and insurance. They also need somewhere to park when they are not working. If there is an accident or a technical problem, someone needs to deal with it and get the car back on the road. Customer support is still needed too when there are problems with bookings or payments, or when someone leaves something in the car.
Some of these tasks may even become more important. Robotaxis are expensive, and every hour a car spends charging, being cleaned or waiting for maintenance is an hour when it cannot take passengers. Moove, for example, already provides fleet ownership, depots, charging, maintenance and 24/7 operations for autonomous vehicles.
Drivers also do more than drive: they notice damage, report faults, help passengers and respond when something goes wrong. Without a driver, these responsibilities need clear processes and dedicated support. Existing fleet experience is an advantage, but operators will need to adapt it to vehicles running without someone behind the wheel.
There can be several companies behind one robotaxi ride. One provides autonomous driving technology, another may own the cars, and a local company can take care of the fleet. A platform such as Uber can then connect the cars with passengers. Sometimes one company may do several of these things, but this is not always the case.
Zagreb is one example. Pony.ai provides the autonomous driving system, Verne owns and operates the fleet, and Uber connects it with customers through its app. Autonomous rides became commercially available through Uber in August 2026 with a licensed operator onboard. On 10 September, Pony.ai and Verne also started fully driverless passenger test rides on a 22-kilometre route connecting parts of Zagreb with the airport. These are still limited test rides, not a fully driverless service across the whole city.
A similar model is being tested in Madrid. WeRide, Uber and AVOMO received permission in September 2026 to start testing and mapping under Spain’s ES-AV framework. The first 20 vehicles have an onboard specialist. WeRide provides the autonomous technology, Uber connects the cars with passengers, and AVOMO takes care of fleet operations. Commercial operations are planned for later in 2026, but the current permit is for testing and preparation rather than a general driverless taxi service.
In London, Wayve and Uber launched supervised autonomous passenger rides in September 2026. Customers can be matched with an autonomous vehicle through the Uber app, but there is still a licensed driver in the car.
The plans for the next few years are already much bigger. Pony.ai and Uber announced in August 2026 that they plan to deploy more than 2,000 robotaxis in Europe, starting with Zagreb and later expanding to four more European cities.
Bolt and Lucid announced another partnership in September, with Bolt aiming to deploy at least 25,000 autonomous Lucid vehicles across European cities. This is a future target, not 25,000 cars already operating today.
How these fleets are owned and operated may also be different from one city to another. Local regulations, available vehicles, charging and depot infrastructure and partnerships will all have an effect on how each service is set up.
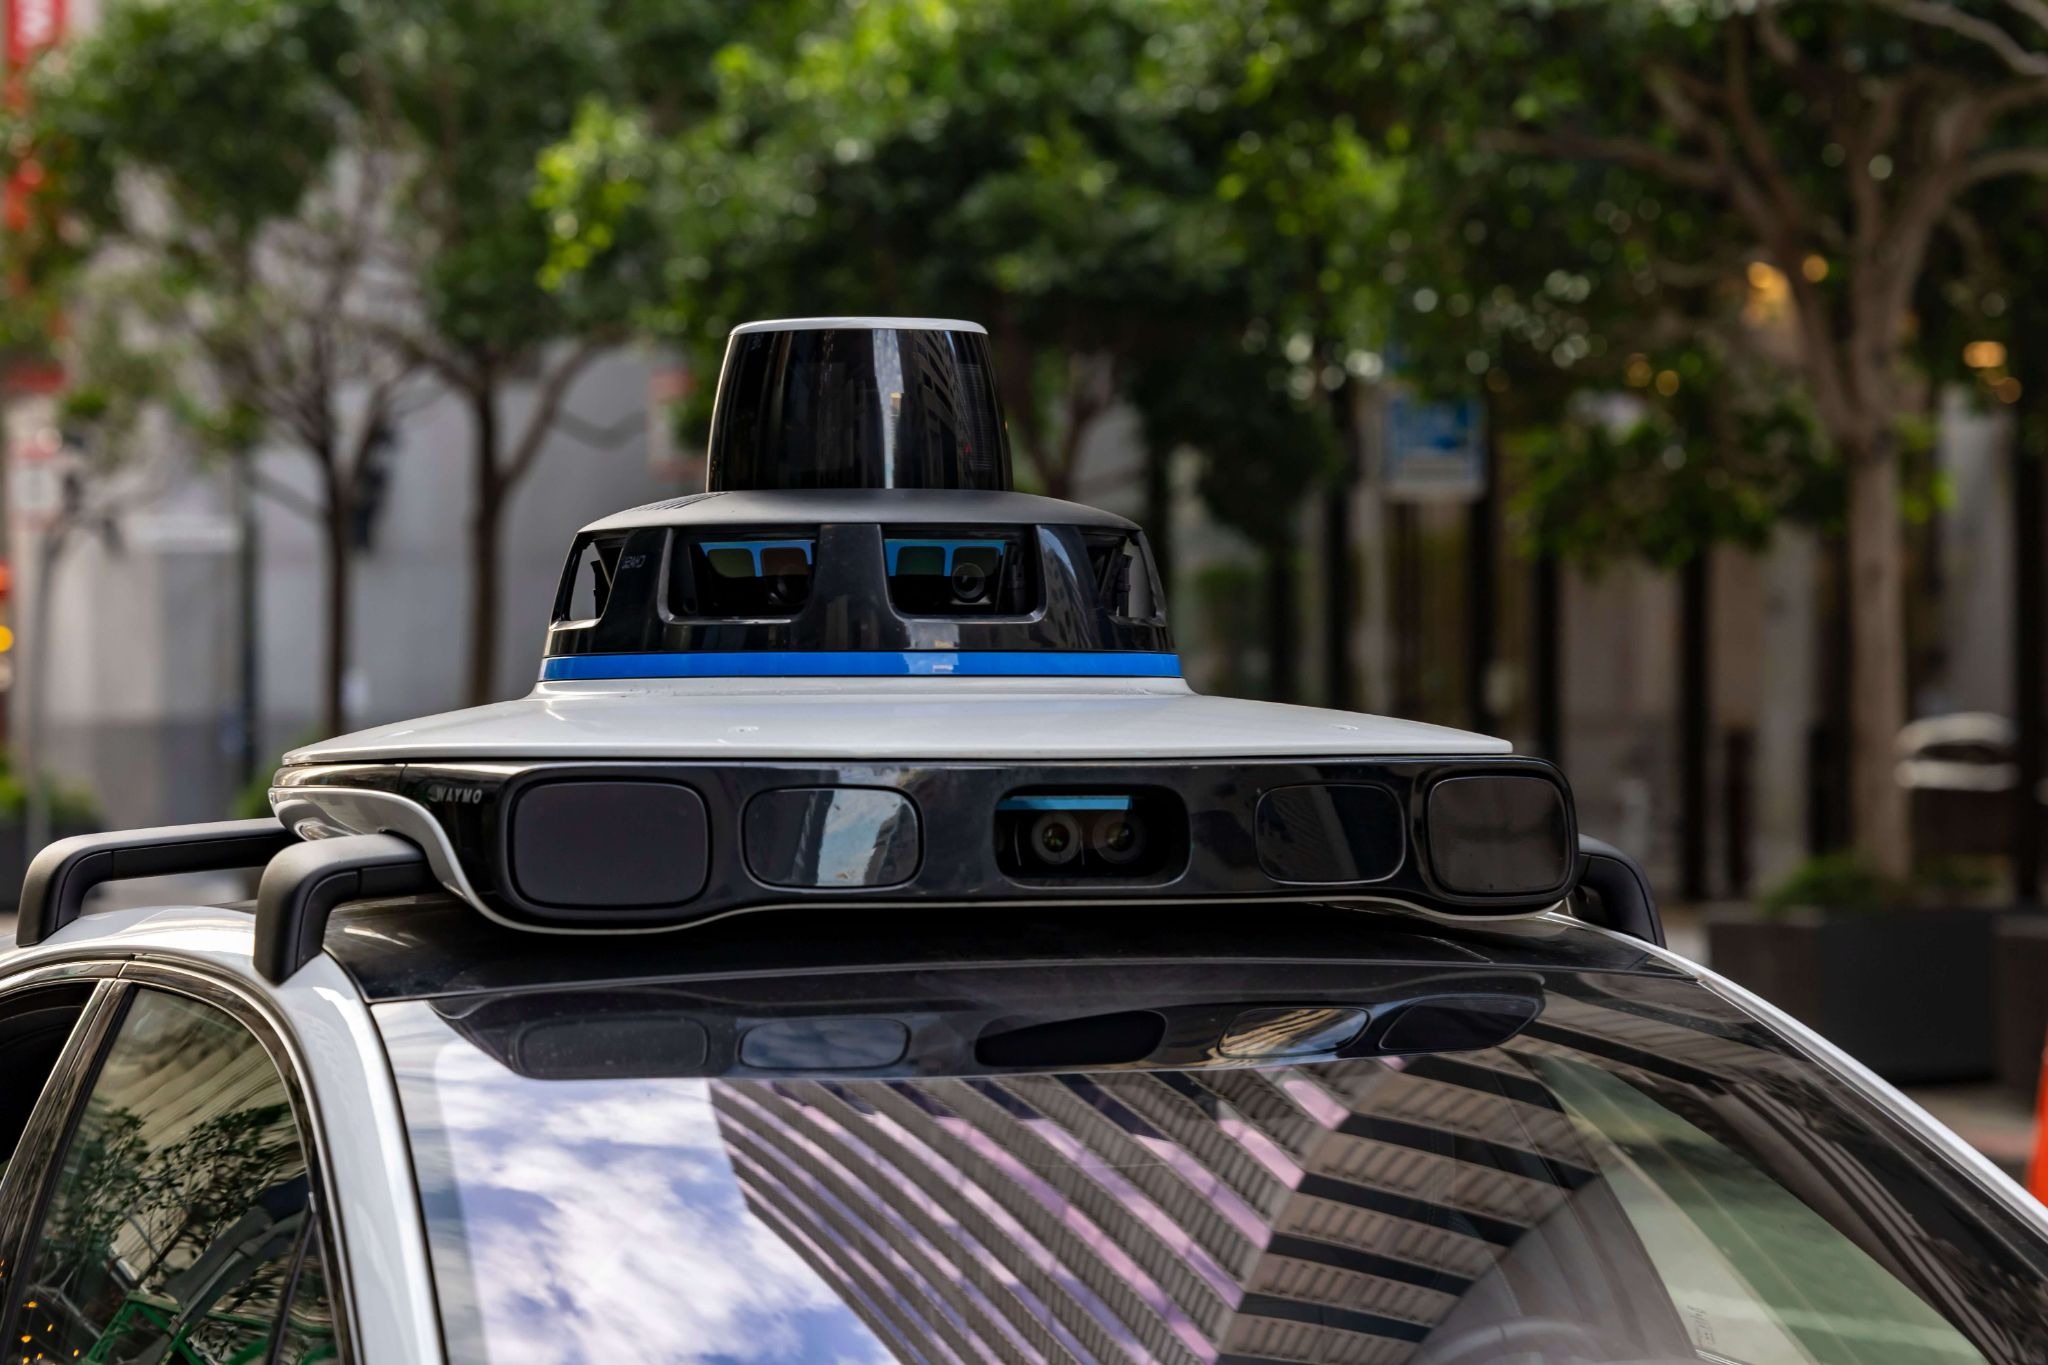
Taxi companies already do many of the things that would still be needed with an autonomous fleet. They maintain cars, deal with insurance and incidents, provide customer support and make sure enough vehicles are available. Some also already have their own depots, charging infrastructure or maintenance partners.
One possible model can already be seen in Zagreb. A local company owns and operates the autonomous fleet, while a larger ride-hailing platform brings customers. In the future, an existing taxi company could potentially have a similar role. Instead of managing cars and drivers, it could manage autonomous cars that receive bookings through a larger platform.
This does not mean platforms such as Uber will always rely on other companies to own the cars. Uber’s 2026 agreement with Rivian includes up to $1.25 billion in milestone-dependent investment and says that Uber or its fleet partners may purchase the autonomous vehicles. Uber is also developing infrastructure for autonomous fleets. Different ownership models are therefore possible.
Autonomous vehicles could also become interesting for rental and car-sharing companies, although this is probably further in the future. These businesses already manage vehicles, maintenance, cleaning, charging, bookings, customer accounts and payments, so much of the practical work is similar.
Autonomous driving could also change how rental and sharing cars are moved. Today, an employee may need to drive a car from one location to another. In the future, the vehicle could potentially do this itself within an area where autonomous driving is approved. It could even become possible for a rental car to drive itself to a customer’s pickup point.
Without drivers, it becomes especially important to understand how much time each vehicle is actually working. Every hour spent charging, being cleaned, waiting for maintenance or simply sitting unused means less time carrying paying passengers.
Some useful KPIs could be available hours per vehicle, paid trips per vehicle each day, revenue per available vehicle/day, empty kilometres, charging and maintenance downtime, cost per trip and incidents that need human help. These are most popular robotaxi industry KPIs of what a company could measure during a pilot.
For example, if cars spend too much time waiting to charge, the charging setup may need to change. A lot of empty kilometres could mean the cars are not in the right places, while too much maintenance downtime could make a vehicle more expensive to operate.
For either model, the business case depends on the partnership terms: who finances the vehicles, who carries the risk when demand is low, and how revenue and operating costs are shared. Operators should assess what remains after vehicle financing, insurance, charging, maintenance and partner fees. Depots, local service teams and reliable fleet availability could make an operator a valuable partner, but profitability still needs to be demonstrated.
One option for taxi fleets would be to work with an autonomous driving company and a larger ride-hailing platform. The local company could own or manage the cars and take care of the fleet, while customers book their rides through the larger platform.
Another option could be possible in cities where large ride-hailing platforms are not present or have limited coverage. A local company could work with an approved AV provider while using its own app, bookings, payments, customer support and fleet management.
In both cases, a company cannot simply buy autonomous cars and start offering rides. The technology needs to be approved, and local rules have to allow the service. These rules will also be different across Europe. Great Britain, for example, introduced its Automated Passenger Services permitting framework in 2026. Services similar to taxis or private hire vehicles need consent from the relevant local authority, while responsibility for the autonomous driving technology and the passenger service are treated separately.
A company does not need to have autonomous cars today to start preparing. A good first step is understanding the current fleet in detail – what each vehicle costs, how many hours it is available, how much time it spends charging or being repaired, and when cars are used the most.
Charging, cleaning, maintenance and depot processes are also worth looking at because all of these will still be needed with autonomous vehicles. A company interested in an AV pilot can then choose a location and use case, look at the local permit process and start talking to autonomous driving technology providers.
The software will also need some preparation. Customers still need to book and pay for rides, while the company needs fleet information, customer support, reporting and connections between its own systems and the AV technology. Starting with a small pilot makes it possible to test all of this before trying to build a larger service.
ATOM Mobility already provides many of the software functions used by taxi, ride-hailing, rental and sharing companies, including customer apps, bookings, payments, fleet management, maintenance tasks, analytics and APIs. Its ride-hailing software includes passenger and driver apps, dispatch, payments, fleet data, analytics and integrations. The ATOM Mobility API can also exchange data about vehicles, bookings, rides, payments, telemetry and maintenance tasks.
ATOM Mobility does not provide autonomous driving technology. This would come from a specialised AV company, and each project would have its own technical requirements and local approvals. For an AV pilot, ATOM Mobility could work with the fleet company and AV provider on the rider experience, integrations, fleet management and the data needed to measure how the pilot is working.
If you operate a taxi, rental or sharing fleet and want to explore an AV pilot, ATOM Mobility can help plan the booking and fleet-management setup, integrations and metrics you would need to test together with an AV technology partner.
Use test credentials to log in - Phone number: +1 123123123, Code: 777777


Driver App demo credentials - Email: test@atom.com, Password: driver