How technology is shaping the future of mobility
February 3, 2020
min. read

Technology is helping transform the future of urban transportation by influencing what mobility will look like, and how it will impact the modern city-scape. A recent article by Forbes Technology Council explained that there is a shared consensus around the four key features of future mobility: shared, hybrid, autonomous and electric. The next question becomes, what will mobility services will be available in the coming years? We have done some research to help breakdown the different perspectives on shared mobility as a mode of transportation in the future.
Why electric?

By 2040, electric cars will outsell gasoline-powered cars
Recently consumers have shifted their interest towards electric vehicles as a more sustainable and environmentally conscious option for long-distance travel. Predictions expect electric vehicles to surpass traditional combustion cars within the next 20 years, with 57% of passenger vehicles and more than 30% of global passenger vehicle fleet sales being electric by 2040. With this growth also comes a need for additional charging infrastructure to allow the vehicles to travel further over long distances. Currently there are about 13,000 electric vehicle fast charging stations across the US, compared to roughly 332,000 gas stations. Companies such as Volkswagon, GM and Tesla, have announced they are working on creating charging that will help drive sales in the future. Successful expansion into the market will require cities to develop smart plans that accommodate the needs of electric mobility.
Why shared?
Shared mobility has grown extensively since Uber (2009) and Lyft (2012) first entered the market. More and more operators continue to emerge worldwide, offering at least one ridesharing service to people in over 700 cities. These services are expected to expand even further in the future as a result of increased urbanization, as well as growing concerns around sustainability, economic stability and emissions. A report by the Internet of Things’ analyst firm, Berg Insights, found the number of car-sharing service users will grow from 50.4 million people in 2018 to 227.1 million people in 2023. Offering mobility as a service is helping reduce the number of single-use vehicles on the road, lending itself to a more functional form of travel.
Why autonomous?
A major challenge facing urban drivers is the issue of congestion and traffic jams. In some metropolitan cities, such as London, the problem lead to the enforcement of congestion charges in their most heavily populated neighbourhoods. In effect since 2003, these charges have helped reduce traffic by 30%, will simultaneously generating funds for the city. But is that enough? Autonomous vehicles are believed to be the next step in reducing congestion. A study conducted by researchers at the University of Cambridge found that when a fleet of autonomous vehicles are effectively communicating, keeping traffic moving smoothly, congestion rates could be reduced by 35%.
Why hybrid?
Micro-mobility is the use of small mobility devices, designed to carry one or two people, or ‘last-mile’ deliveries. This goes hand-in-hand with the rising interest in e-scooters and e-bikes that have seen exceptional sales growth in recent years. The combination of electric with single-use, lightweight vehicles is expected to surpass traditional modes of transportation. In their annual technology, media and telecommunications predictions, Deloitte predicted more than 130 million e-bikes will be sold between 2020 and 2023. Compared to the 1.8 million sold in Europe and 185,000 in the US during 2013, this significant increase suggests that e-bikes and other technology like it are the future of mobility.
How are city’s supporting?
Cities across the world have begun adapting strategies to assist with the future of urban mobility. Being the leader in reducing traffic, Singapore introduced Area licencing Scheme in 1975, enforcing a daily toll charge of $3 or $60 monthly for cars entering a central zone area during peak hours. The city experienced success resulting in fewer cars entering the zone during peak hours, a 35 percent increase in carpools and a minimum of $500 million saved by the city that could be used towards infrastructure improvements. The system has since been updated to an Electrical Road Pricing system in order to match the changing demands of the city’s core.
San Francisco has yet to enforce congestion pricing for its traffic heavy neighbourhoods, however, research is being conducted to determine the best solutions for the city. The Emerging Mobility Evaluation Report by the San Francisco Transportation Authority found 90 percent of all motor vehicle collisions are caused by human error, with approximately 80 percent involving some level of inattention. This has lead to a shift towards alternative modes of mobility and potential pilot projects within the city core. San Francisco has become known for its low income bike share programs. Launching in 2013 the Bay Area Bike Share Pilot requires at least 20% of stations be located in low-income communities, with an estimated 320 stations and 4,500 in 2017. Data collected by the Bike-sharing Blog estimates there are twice as many bike-sharing programs in the world as there were in 2014, with nearly 20 times more bikes available for public use.
The doors have opened for industry leaders to start making innovations within auto-mobility, influencing the modern city-scape. In addition to placing restrictions on heavily congested areas, the city of Helsinki has focused its efforts on improving the existing infrastructure and transportation options to encourage people to utilize other modes of mobility. A leader in mobility-as-a-service (MaaS) platforms, the city plans to replace 2.3 billion urban private car journeys annually by 2023. One of the ways it’s begun to accomplish this is through the app Whim. An app developed specifically for Helsinki, Whim provides access to all of the city’s mobility options through a monthly subscription. The future of mobility is at people’s fingertips.
What’s next?
Cities around the world are beginning to explore the possibilities of e-scooters as a means to travel short distances too far to comfortably walk, as well as a potential solution towards reducing the reliance on cars. The city of Tallahassee launched a pilot program in partnership with five major e-scooter companies: Bird, Lime, VeoRide, Spin and Gotch. The purpose is to determine solutions for the major problems being faced, but to also help develop good ridership habits. The companies deployed 200 e-scooters, each capable of travelling 15 mph, under new legislation that allows them to be treated the same as bicycles. With the success of programs such as this, and companies making pledging to maintain social responsibility for user safety, e-scooters as a primary mode of mobility are on the rise.
Nuro, a self-driving start-up, is one of the few companies to currently have a fleet of fully driverless vehicles operating on public roads. In February 2019, the company secured roughly $1 billion in additional funding from SoftBank allowing them to partner with the grocery-store chain Kroeger’s for a pilot project. The pilot service has been delivering groceries in Houston, Texas since March 2019, with expansions to include other goods like Domino's Pizza and Walmart products. As of right now the fleet stands at about 75 vehicles, with plans to go public in 2020. By introducing fully automated vehicles into the market, the number of people on the road will be reduced, optimizing efficiency and offering greater protection from potential collisions or incidents.

Nuro self-driving vehicle
In addition to reducing traffic in major cities, mobility companies are also focusing their resources on addressing concerns of energy consumption and emissions. The smart scooter mobility company, Gogoro, aims to leverage the power of technology in order to change the way technology is consumed and transform how cities operate to improve sustainability. Their first fleet of smart scooters launched in 2015, delivering a high performance electric riding experience to uses in Taiwan. The company also established a network known as the Gogoro Energy Network in Taipei offers more than 1,581 battery swap stations and supports over 199,478 battery exchanges every day. In Europe, a fleet of 3,500 emissionless smart scooters were released across three major countries in 2018, helping reduce CO2 emissions by 123,655 tons and displacing more than 58,731,863 liters of gasoline. By leveraging technological progress and innovations in modern infrastructure, Gogoro is becoming a leader in transportation solutions.

Electric scooter Gogoro with swappable batteries
Companies, like Tortoise, are looking to expand the capabilities of scooters even further by introducing fleets that can move autonomously across a city and reposition themselves, without a rider. The goal is to tackle the biggest challenge currently facing operators: relocating scooters. Tortoise plans to use autonomous technology combined with teleoperation to reposition and rebalance dockless, shared e-scooters in cities. The initial deployment will include between 50 to 100 scooters per operator in each market with the intention to equip every fleet with the ability to autonomously reposition themselves. Autonomous micro-mobility like e-scooters and e-bikes are believed to be the start for creating smarter, more technologically advanced cities.
How can we help?
As both industry leaders and cities around the world are finding new ways to support the rising trend of micro-mobility, we at ATOM Mobility want to help entrepreneurs looking to enter the market. We believe that shared mobility is the future of transportation, offering assistance with integrating industry-leading vehicles ready for shared mobility, including kick scooters, scooters, bikes, mopeds, cars and more. Our customers have an excellent grasp on the current needs of local markets, and we allow them to focus on marketing and operations, while taking care of the technology.
Sources:
https://www.bbc.com/news/technology-33183031
https://www.corporateknights.com/channels/transportation/sharing-road-canadian-cities-driving-progress-shared-mobility-15593076/
https://www.forbes.com/sites/forbestechcouncil/2019/11/22/four-keys-to-future-mobility-shared-hybrid-integrated-and-electric/#3feea979339d
https://edition.cnn.com/2019/07/18/cars/electric-car-market-sales/index.html
https://about.bnef.com/electric-vehicle-outlook/
https://www.businessinsider.com/ubers-history#june-2016-kalanick-proclaims-that-uber-was-profitable-in-hundreds-of-cities-globally-but-that-the-money-was-being-reinvested-in-its-war-against-chinese-rival-didi-the-company-said-at-the-time-that-it-was-losing-1-billion-each-year-in-its-fight-against-didi-34
https://www.cnbc.com/2019/11/08/top-ride-sharing-apps-in-europe-asia-south-america-africa-and-usa.html
https://iotbusinessnews.com/2019/11/14/60333-the-public-carsharing-fleet-reached-332000-vehicles-worldwide-in-2018/
https://www.bbc.com/news/world-us-canada-47874725
https://www.sciencedaily.com/releases/2019/05/190519191641.htm
https://assets.publishing.service.gov.uk/government/uploads/system/uploads/attachment_data/file/846593/future-of-mobility-strategy.pdf
https://www2.deloitte.com/content/dam/insights/us/articles/722835_tmt-predictions-2020/DI_TMT-Prediction-2020.pdf
https://eresources.nlb.gov.sg/infopedia/articles/SIP_777_2004-12-13.html
https://eresources.nlb.gov.sg/infopedia/articles/SIP_832__2009-01-05.html
http://sfcta.org/sites/default/files/2019-03/Emerging%20Mobility%20Studies_11.pdf
https://www.sfmta.com/getting-around/bike/bike-share
https://www.businessinsider.com/bike-sharing-programs-doubled-since-2014-public-bikes-charts-2018-7?IR=T
https://www.smartcitiesworld.net/news/news/helsinki-leads-in-mobility-as-a-service-3308
https://whimapp.com/
https://eu.tallahassee.com/story/news/2019/07/15/electric-scooters-tallahassee-florida-bird-scooters-rental-gotcha-lime-spin-veoride-escooters/1708270001/
https://www.wctv.tv/content/news/Five-companies-launch-e-scooters-in-Tallahassee-during-pilot-program-512748851.html
https://nuro.ai/product
https://www.wired.com/story/softbank-nuro-self-driving-investment/
https://qz.com/1644476/nuro-will-deliver-dominos-pizza-with-its-robots-in-houston/
https://www.theverge.com/2019/12/10/21004678/nuros-driverless-delivery-robots-walmart-houston
https://medium.com/nuro/new-rules-of-the-road-for-california-and-autonomous-vehicles-2fa26a1159cb
https://www.gogoro.com/about/
https://www.tortoise.dev/
https://www.theverge.com/2019/10/15/20910083/tortoise-autonomous-electric-scooters-self-driving-robotics
https://www.fastcompany.com/90417611/it-was-inevitable-the-scooters-are-now-driving-themselves
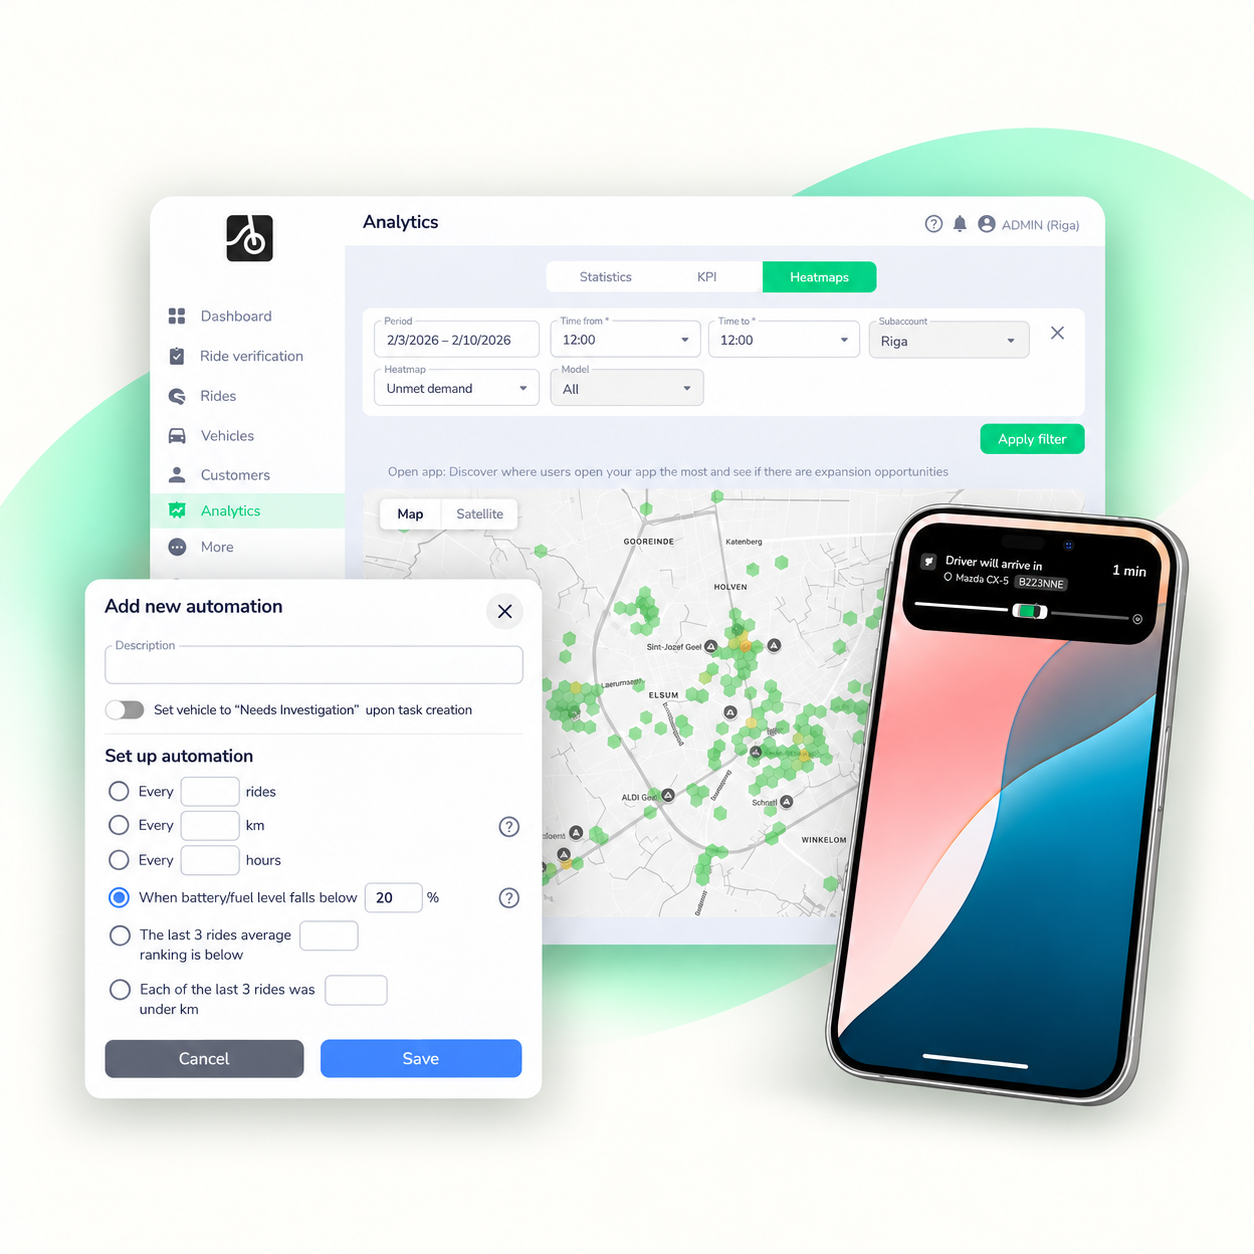
🚀 ATOM Mobility ships 7-15 new features every month, alongside smaller improvements and fixes. Explore five recent highlights: unmet demand heatmaps, automated fleet tasks, field-team performance tracking, new subscription types, and lock-screen ride updates - helping operators run more efficient fleets and improve the rider experience.
Knowing where customers need vehicles, keeping field teams productive, and giving riders reasons to return are everyday priorities for mobility operators. Every month, ATOM Mobility ships 7-15 new features, alongside smaller improvements and fixes. Here are five highlights from our recent releases - and how they can help operators improve fleet performance and the customer experience.
A customer opens your app, finds no vehicle nearby, and leaves. Your ride history alone won’t show you that missed opportunity.
The Unmet Demand heatmap highlights areas where users open the app but cannot find an available scooter, bike, or car within 1000 metres radius. Beyond colour-coded hexagons, on zoomed in view it shows the number of unique users who searched for a vehicle in each area without finding one nearby.
Use these insights to identify gaps in fleet coverage, prioritise rebalancing, and assess potential parking locations. Alongside seeing where rides happen, you can now understand where potential demand goes unmet.

Keeping a fleet ready for customers means staying on top of maintenance, charging, refuelling, and service quality. As your fleet grows into hundreds of vehicles, manually tracking when each vehicle needs attention becomes increasingly time-consuming.
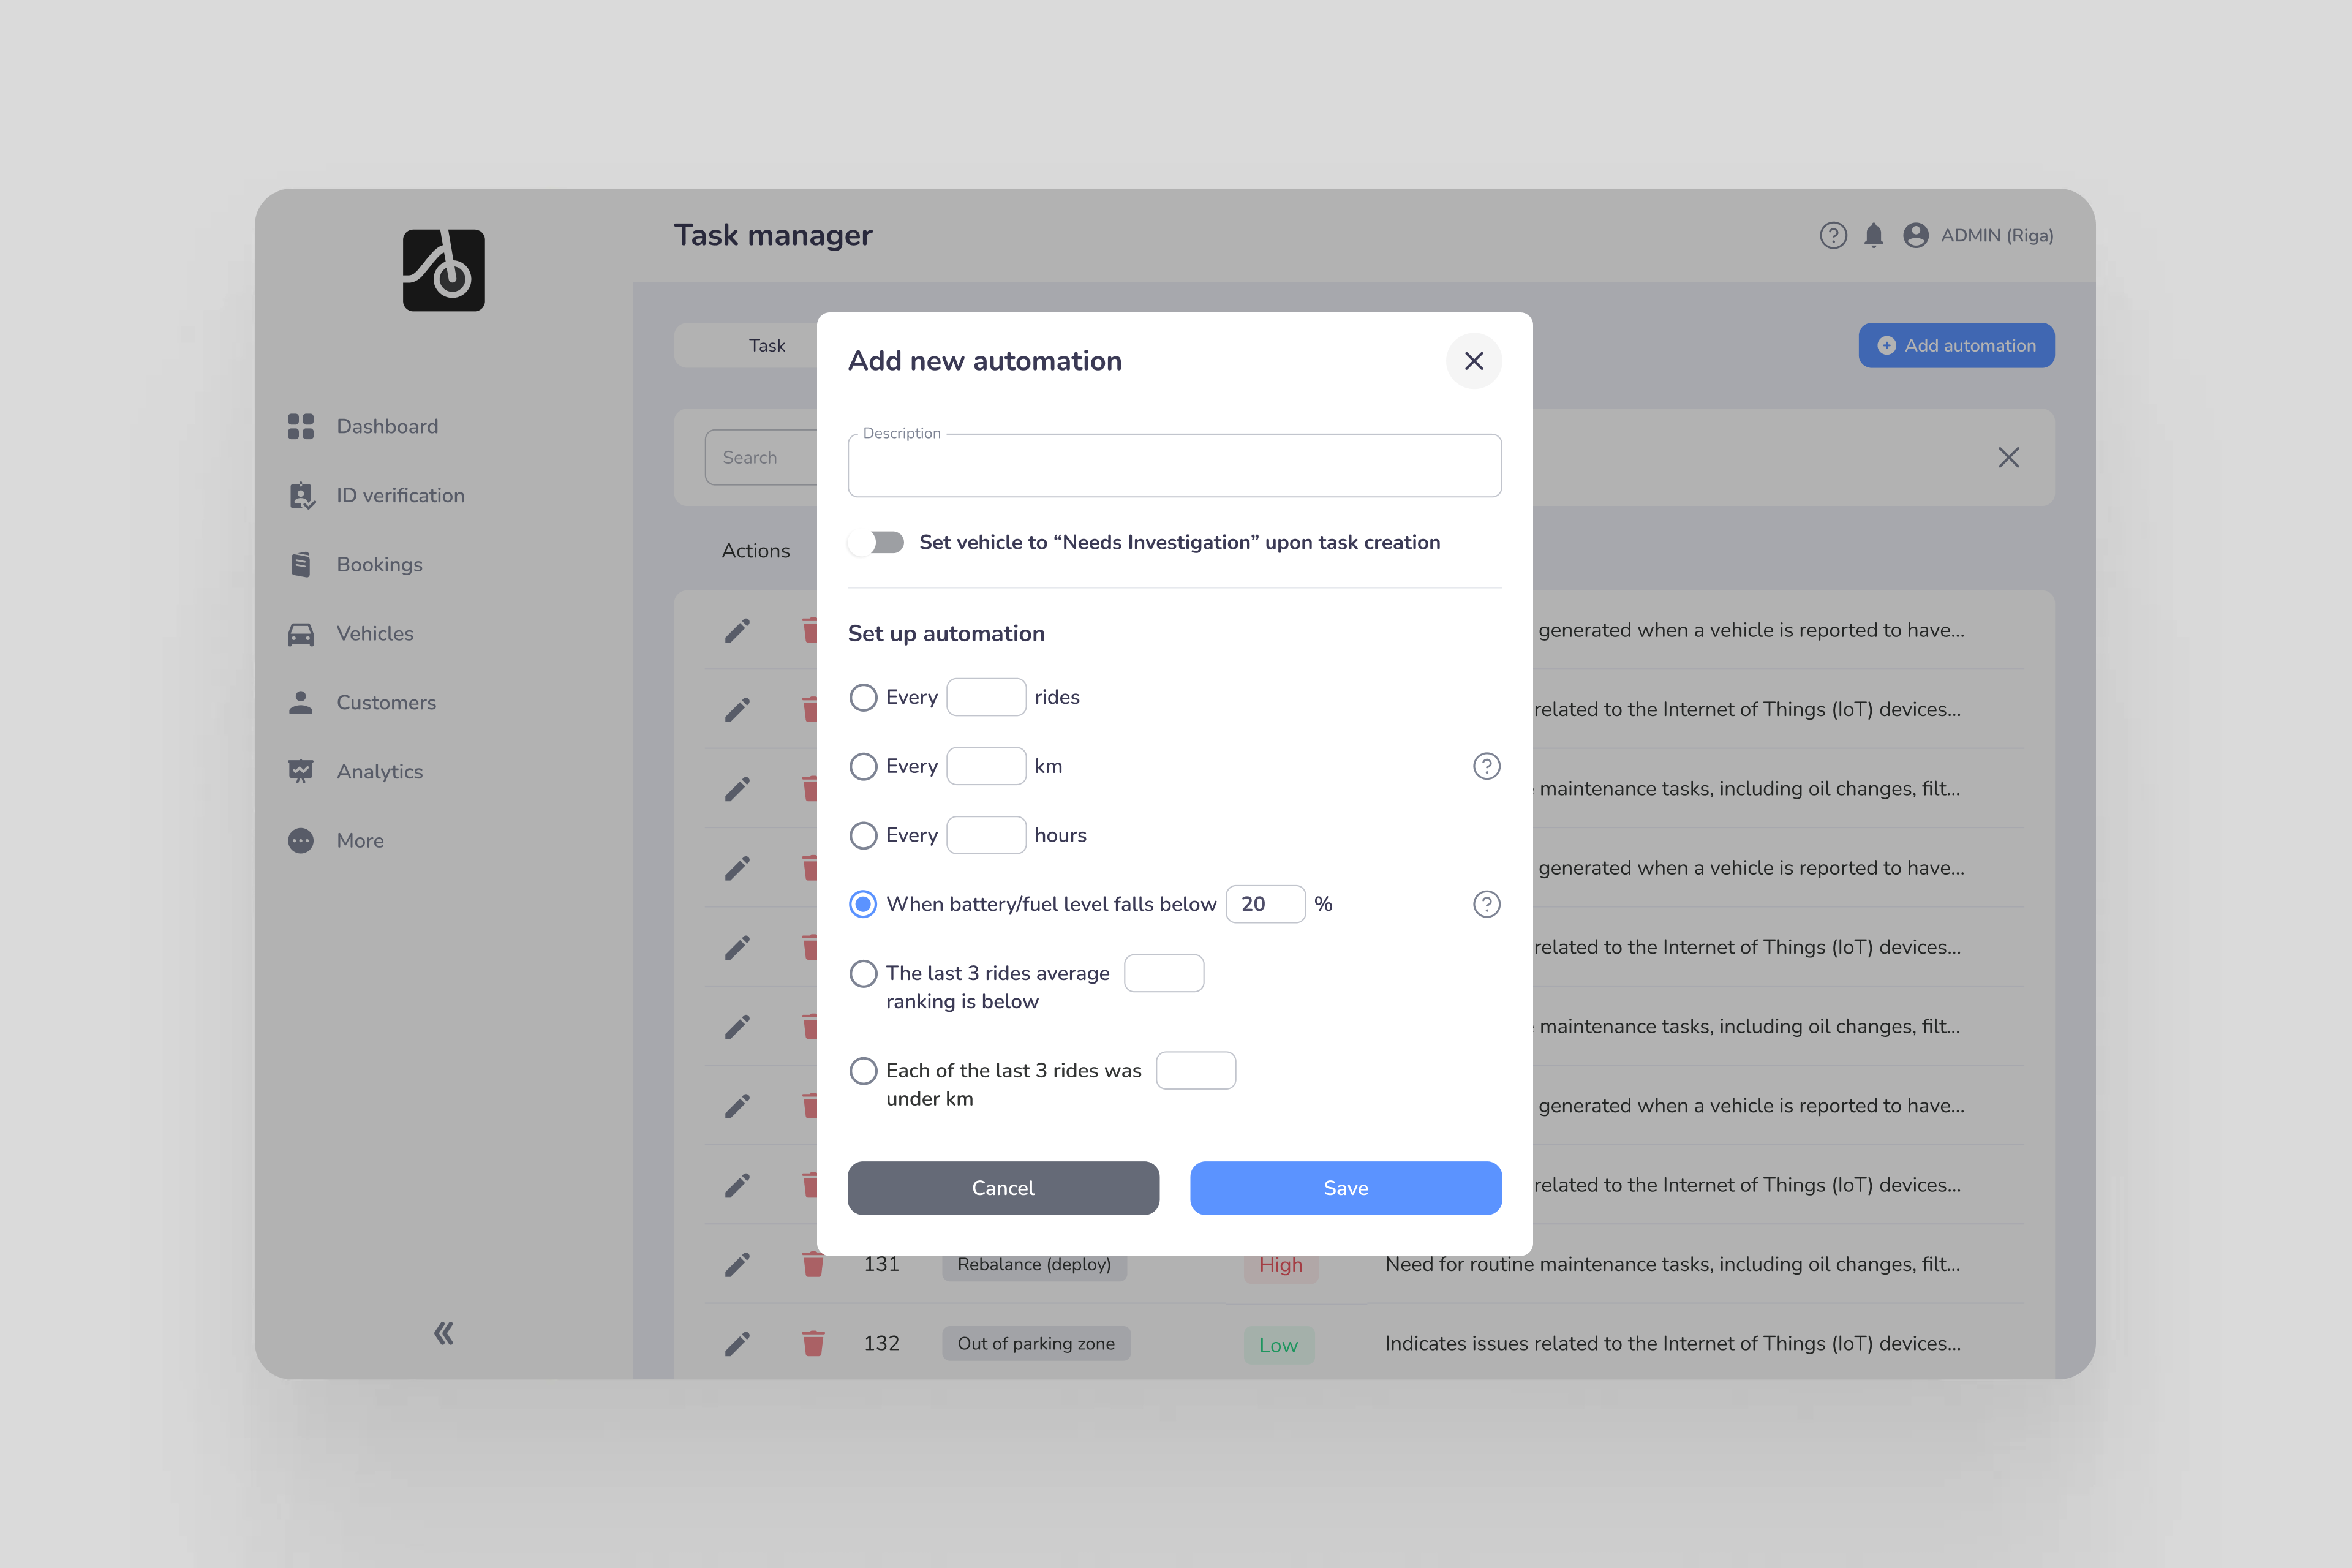
Task Manager automations turn vehicle usage, condition, and ride feedback into actionable tasks. Operators can configure tasks to be created:
These rules can support routine maintenance, trigger charging or refuelling tasks, and flag vehicles for inspection after low ratings or unusually short rides. For rebalancing tasks, if a customer uses the vehicle before collection, the task is automatically removed. This reduces manual monitoring and helps your team respond to vehicles that need attention.
How long do tasks take? Where does your team spend its time? Which operational bottlenecks need attention?
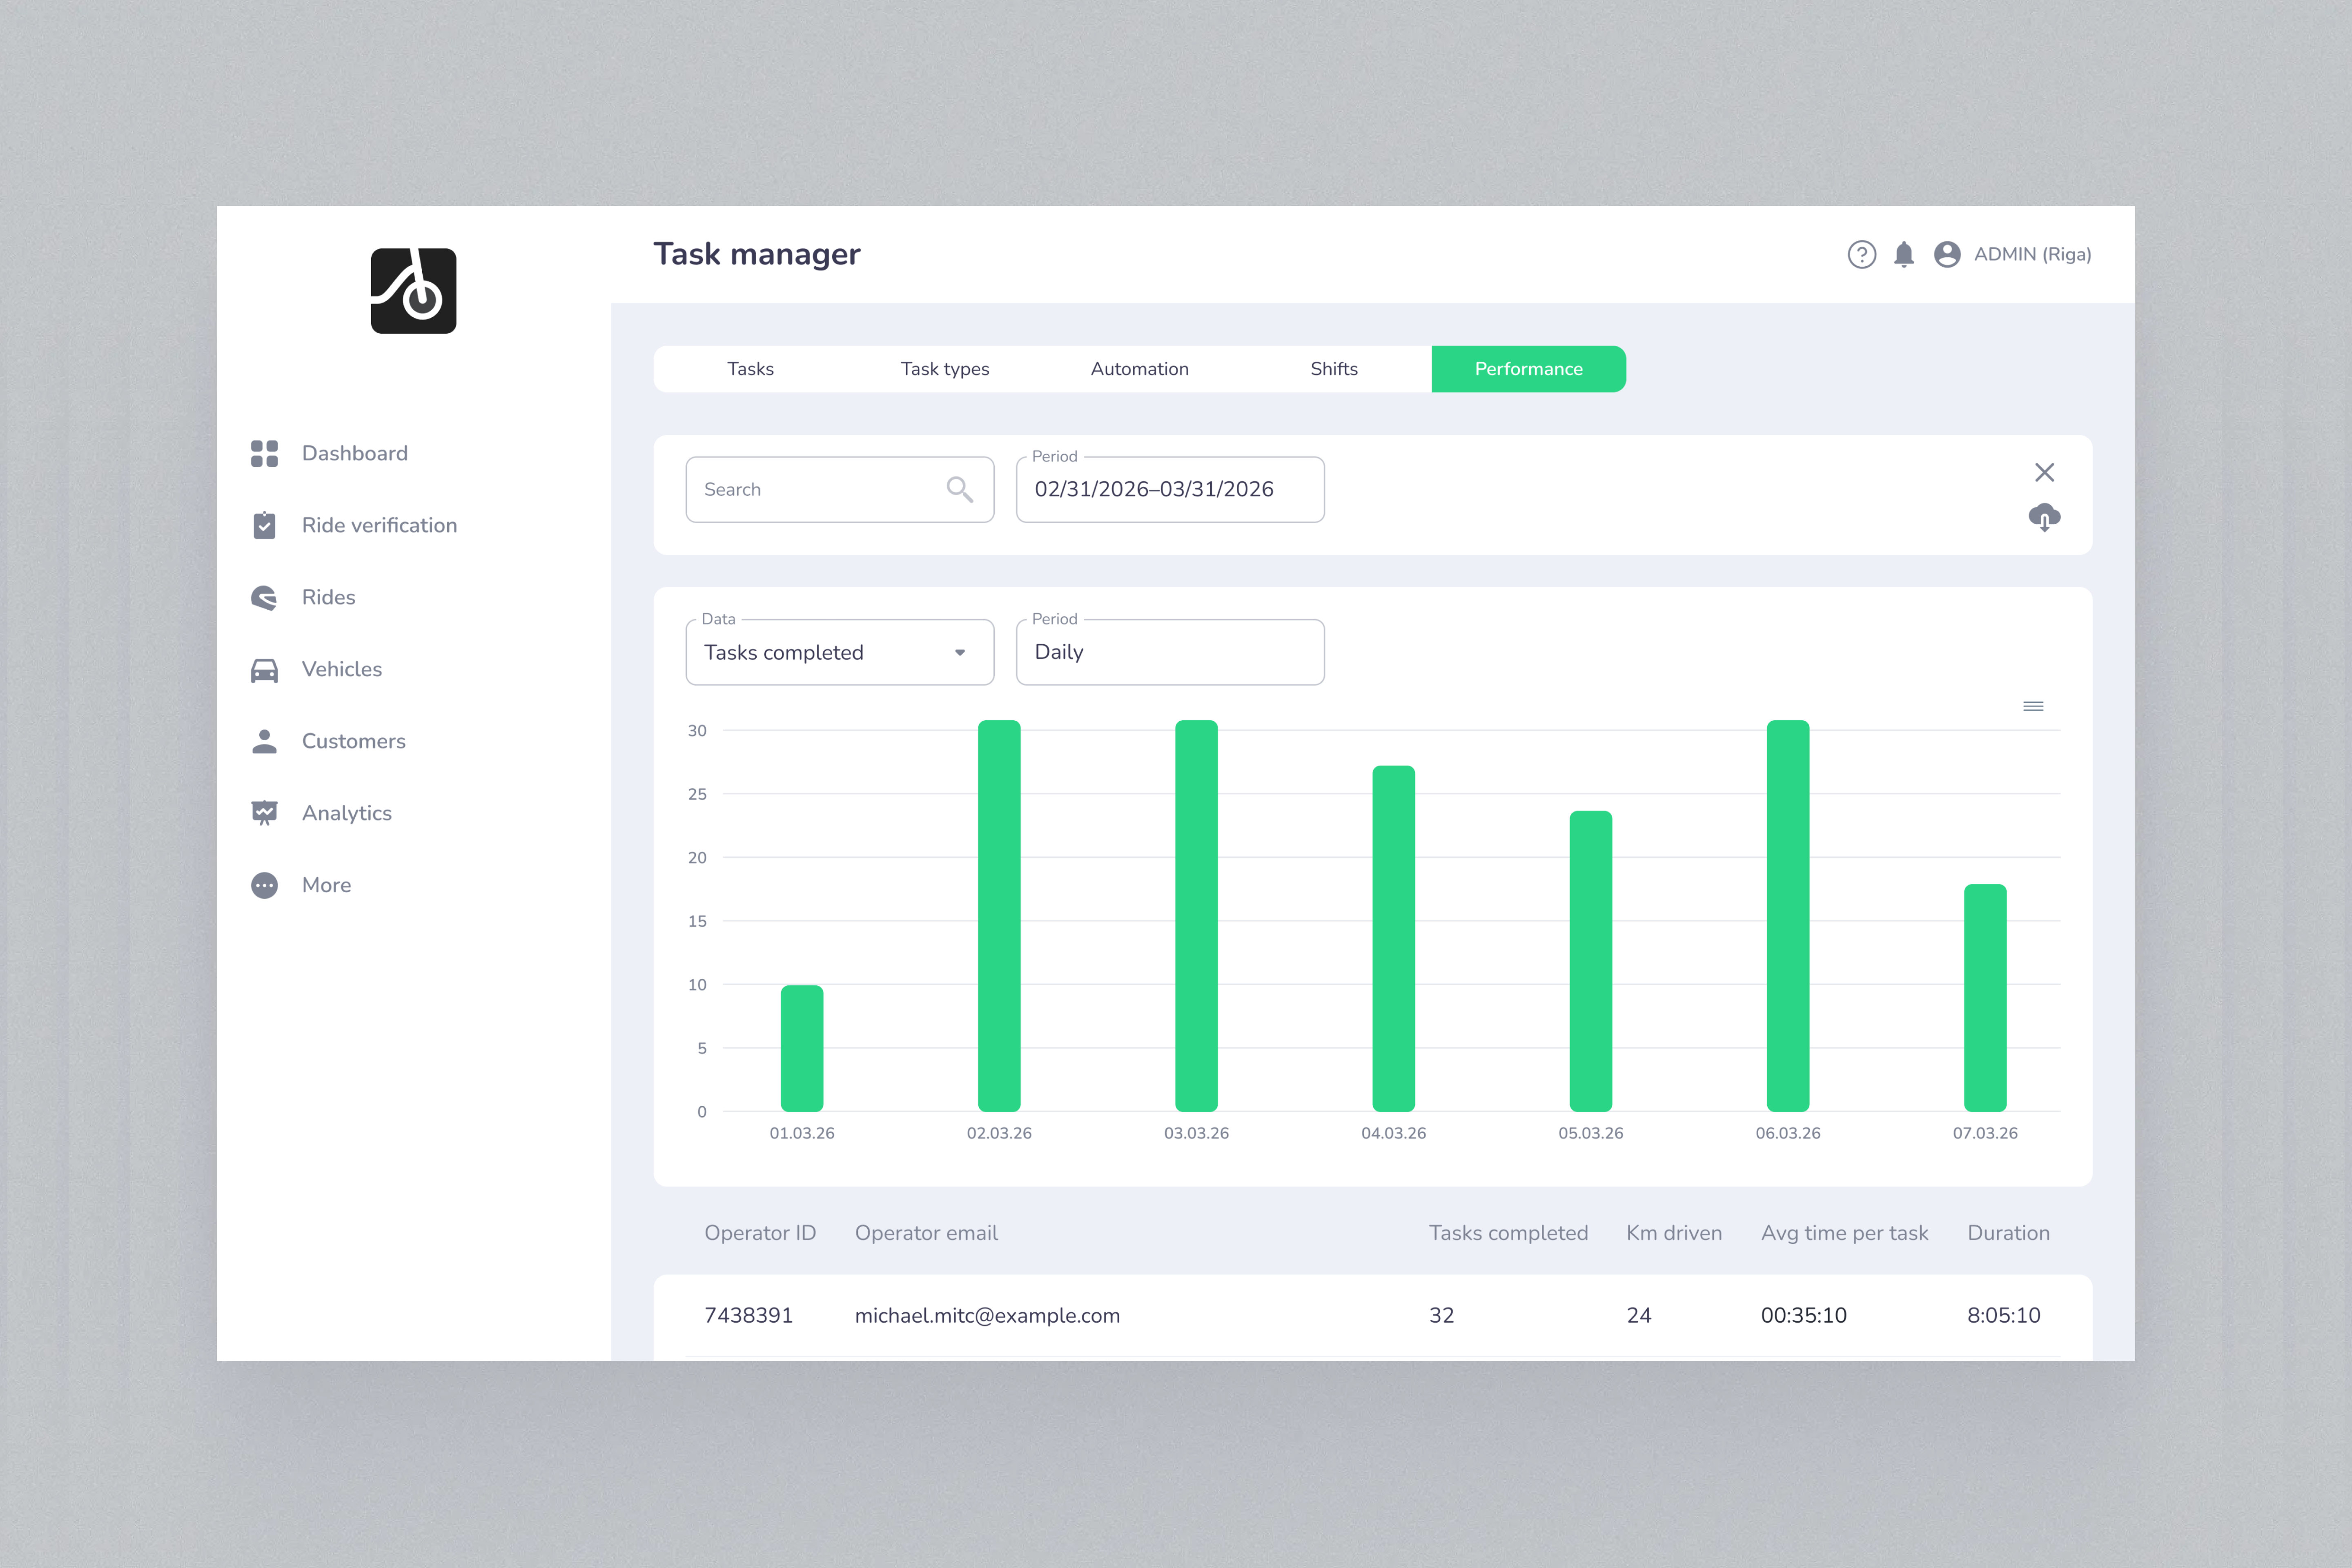
New Shifts and Operator Performance views give vehicle sharing and digital rental operators visibility into shift status and duration, distance driven, completed tasks, and average time per task.
Managers can use these insights to investigate delays, improve routes, and identify training needs. For example, longer task completion times could prompt a closer look at travel distances, workload, or the processes used at each location. Comparing results alongside task types and working conditions helps turn performance data into practical operational improvements.
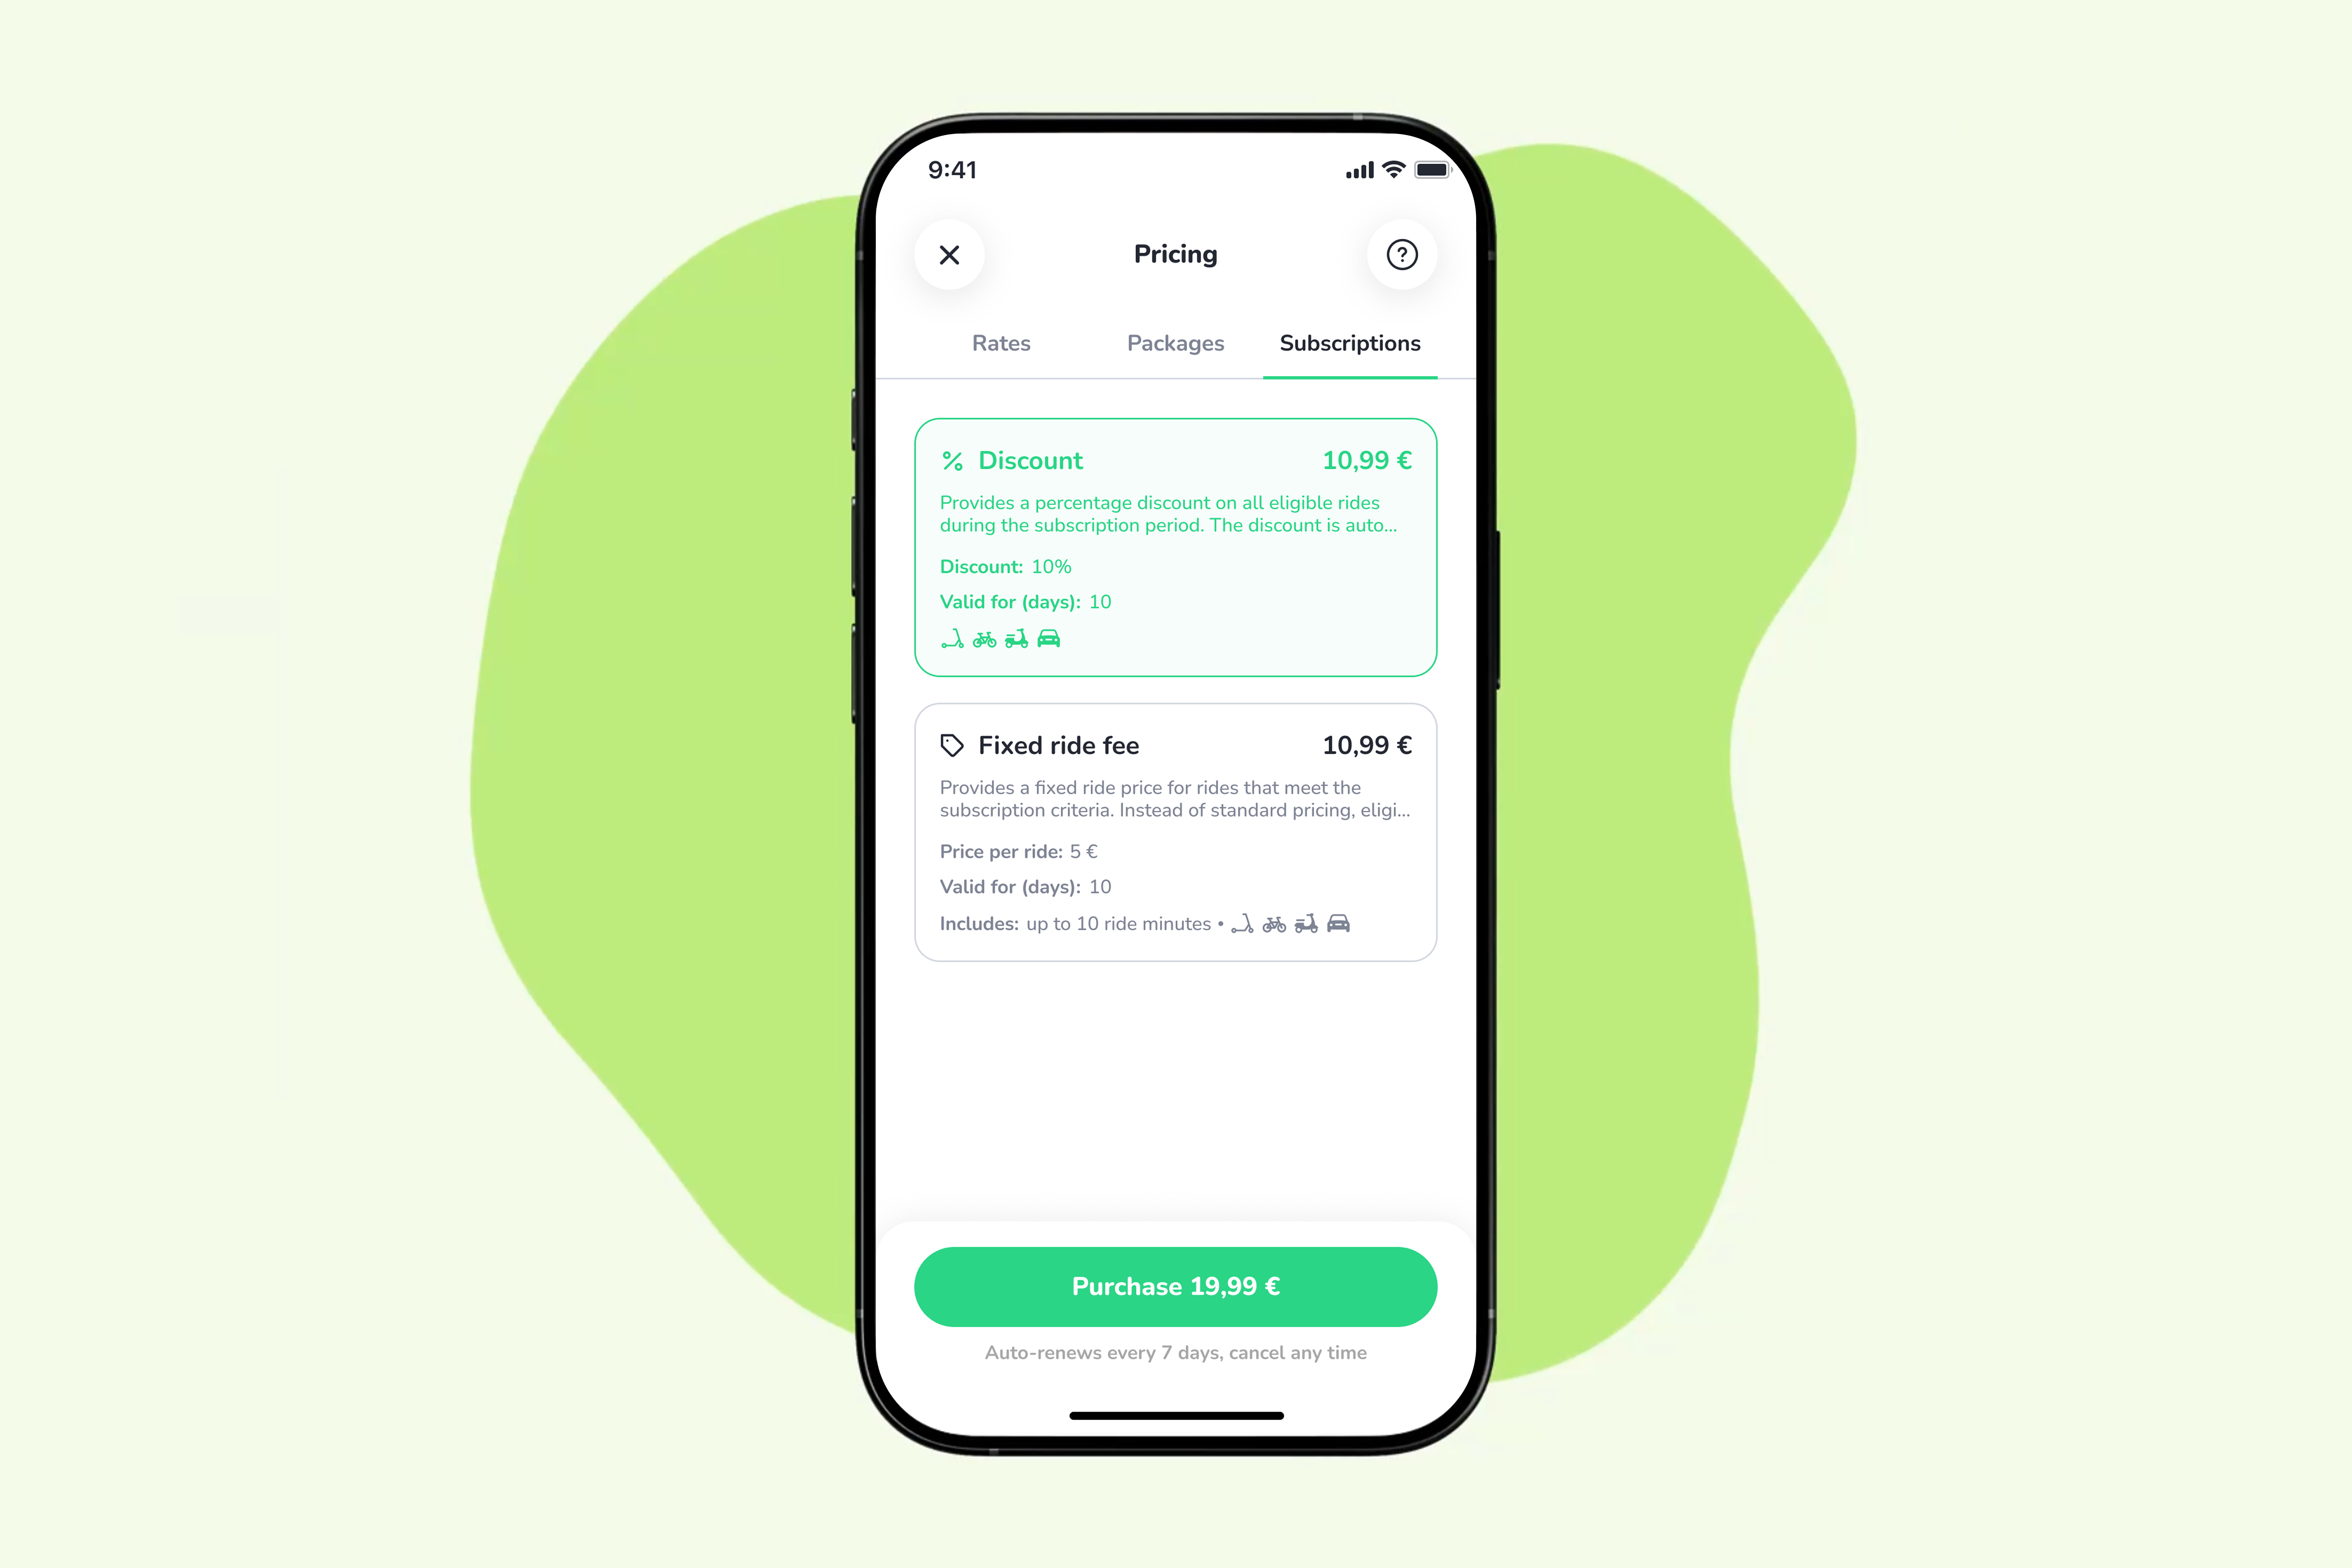
Different customers have different riding habits. Your subscriptions should reflect that.
ATOM Mobility now supports two additional subscription types:
These options let operators design offers around frequent riders and short-distance commuters. For example, you could offer subscribers a percentage discount on eligible rides or a predictable flat fee for qualifying short trips. Operators gain more flexibility to test offers that encourage repeat usage while fitting their pricing strategy.
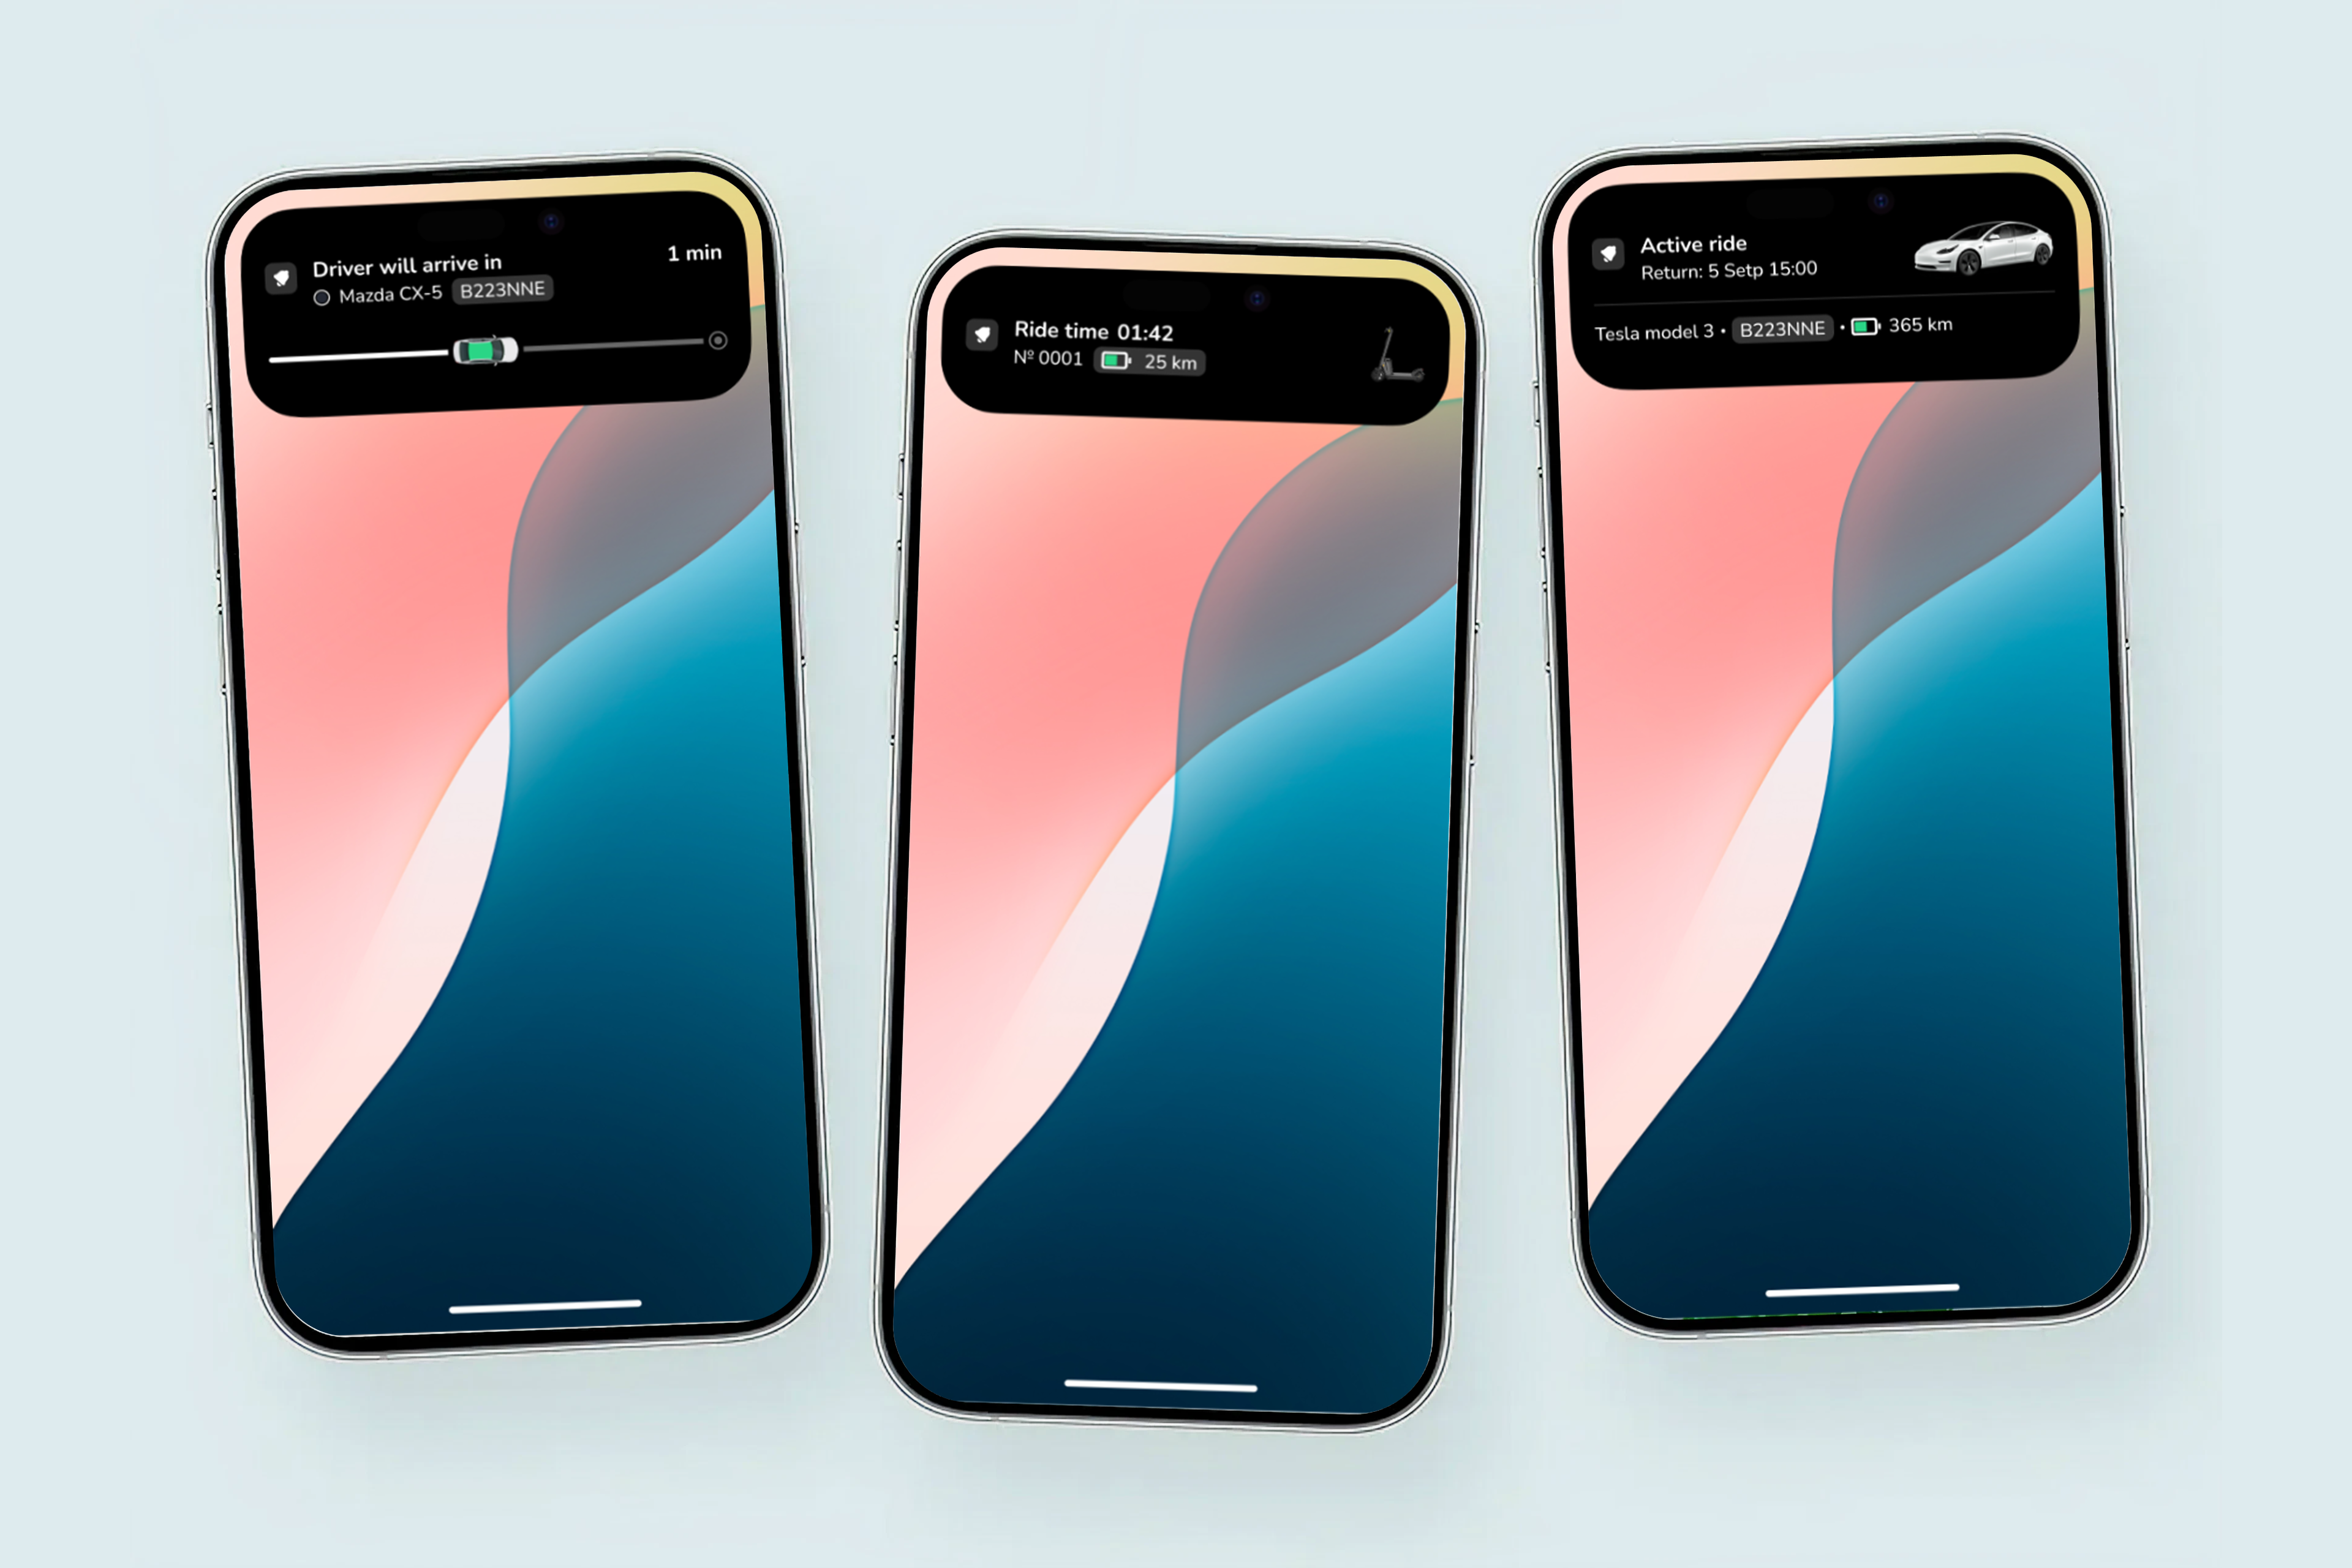
Checking an active trip should be simple.
Live Activity lets customers view key ride information directly on their phone lock screen without repeatedly opening the app. Depending on the service, this can help them follow an active ride or a driver’s arrival.
Making this information readily accessible gives customers a more convenient way to stay informed throughout their journey.
These five releases are part of ATOM Mobility’s ongoing product development, helping operators identify unmet demand, automate routine coordination, understand field-team performance, and improve the customer experience.
Exploring software for your mobility business? Book a demo to see how ATOM Mobility can support your fleet, team, and customers.
Explore more product updates at https://www.atommobility.com/atomupdates
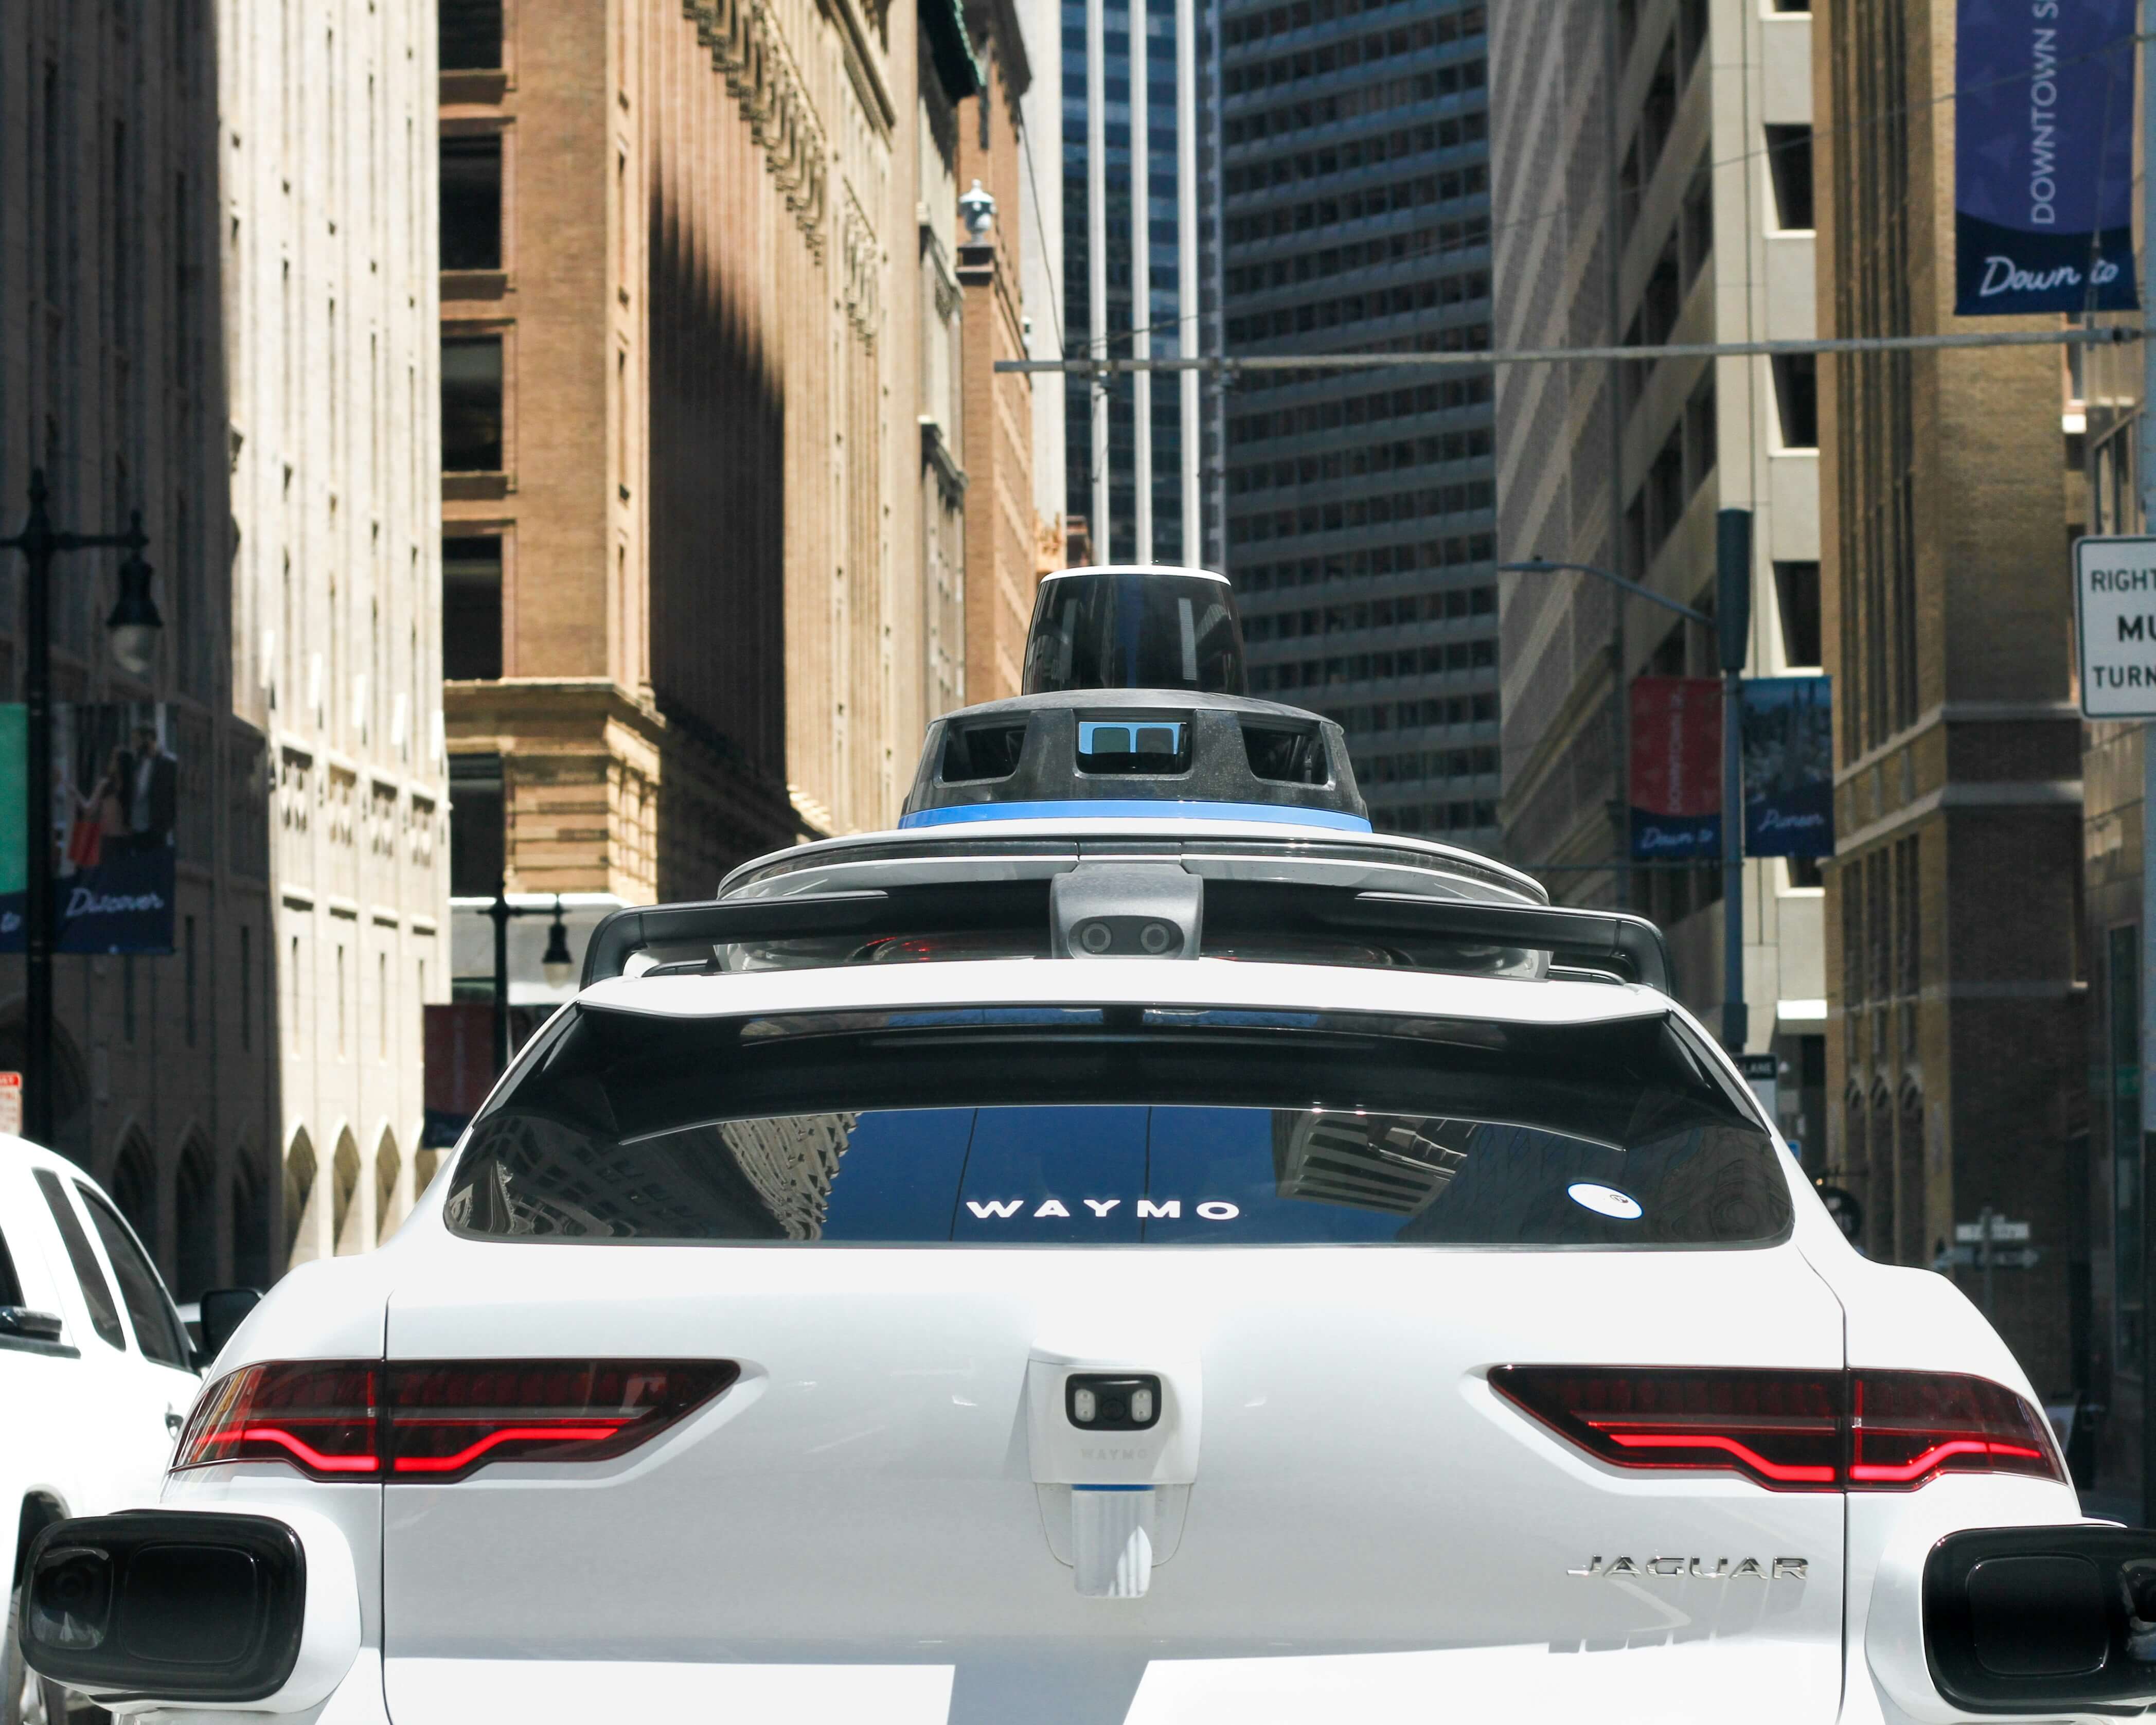
🤖 Who will actually operate Europe’s robotaxi fleets? Autonomous driving may remove the driver, but it doesn’t remove the work behind the car. Robotaxis still need charging, cleaning, maintenance, depots, customer support and someone managing the fleet every day. Early projects in Zagreb, Madrid and London illustrate different stages of deployment and how AV technology providers, fleet operators and booking platforms can work together. Taxi, rental and car-sharing companies already handle many of these tasks. What would it take to turn that experience into an autonomous fleet business?
For a taxi fleet owner, autonomous vehicles may seem to remove the most important part of the current business – the driver. But even without drivers, someone still needs to take care of the cars. They need to be owned or financed, charged, cleaned, inspected and repaired. Someone also needs to manage depots, deal with incidents, help customers and make sure enough cars are available.
The first robotaxi services and tests in Europe are already showing how this could work. The company that develops the autonomous driving technology does not always own or operate the cars. The app where customers book their rides may come from another company too. This could leave an important role for taxi, rental, car-sharing and other fleet companies that already know how to manage vehicles.
A taxi company today manages both cars and drivers. Drivers need to be recruited, scheduled, paid and supported. With a driverless fleet, these tasks would eventually disappear, but most of the work related to the cars would stay.
Autonomous cars still need charging or refuelling, cleaning, tyres, inspections, repairs and insurance. They also need somewhere to park when they are not working. If there is an accident or a technical problem, someone needs to deal with it and get the car back on the road. Customer support is still needed too when there are problems with bookings or payments, or when someone leaves something in the car.
Some of these tasks may even become more important. Robotaxis are expensive, and every hour a car spends charging, being cleaned or waiting for maintenance is an hour when it cannot take passengers. Moove, for example, already provides fleet ownership, depots, charging, maintenance and 24/7 operations for autonomous vehicles.
Drivers also do more than drive: they notice damage, report faults, help passengers and respond when something goes wrong. Without a driver, these responsibilities need clear processes and dedicated support. Existing fleet experience is an advantage, but operators will need to adapt it to vehicles running without someone behind the wheel.
There can be several companies behind one robotaxi ride. One provides autonomous driving technology, another may own the cars, and a local company can take care of the fleet. A platform such as Uber can then connect the cars with passengers. Sometimes one company may do several of these things, but this is not always the case.
Zagreb is one example. Pony.ai provides the autonomous driving system, Verne owns and operates the fleet, and Uber connects it with customers through its app. Autonomous rides became commercially available through Uber in August 2026 with a licensed operator onboard. On 10 September, Pony.ai and Verne also started fully driverless passenger test rides on a 22-kilometre route connecting parts of Zagreb with the airport. These are still limited test rides, not a fully driverless service across the whole city.
A similar model is being tested in Madrid. WeRide, Uber and AVOMO received permission in September 2026 to start testing and mapping under Spain’s ES-AV framework. The first 20 vehicles have an onboard specialist. WeRide provides the autonomous technology, Uber connects the cars with passengers, and AVOMO takes care of fleet operations. Commercial operations are planned for later in 2026, but the current permit is for testing and preparation rather than a general driverless taxi service.
In London, Wayve and Uber launched supervised autonomous passenger rides in September 2026. Customers can be matched with an autonomous vehicle through the Uber app, but there is still a licensed driver in the car.
The plans for the next few years are already much bigger. Pony.ai and Uber announced in August 2026 that they plan to deploy more than 2,000 robotaxis in Europe, starting with Zagreb and later expanding to four more European cities.
Bolt and Lucid announced another partnership in September, with Bolt aiming to deploy at least 25,000 autonomous Lucid vehicles across European cities. This is a future target, not 25,000 cars already operating today.
How these fleets are owned and operated may also be different from one city to another. Local regulations, available vehicles, charging and depot infrastructure and partnerships will all have an effect on how each service is set up.
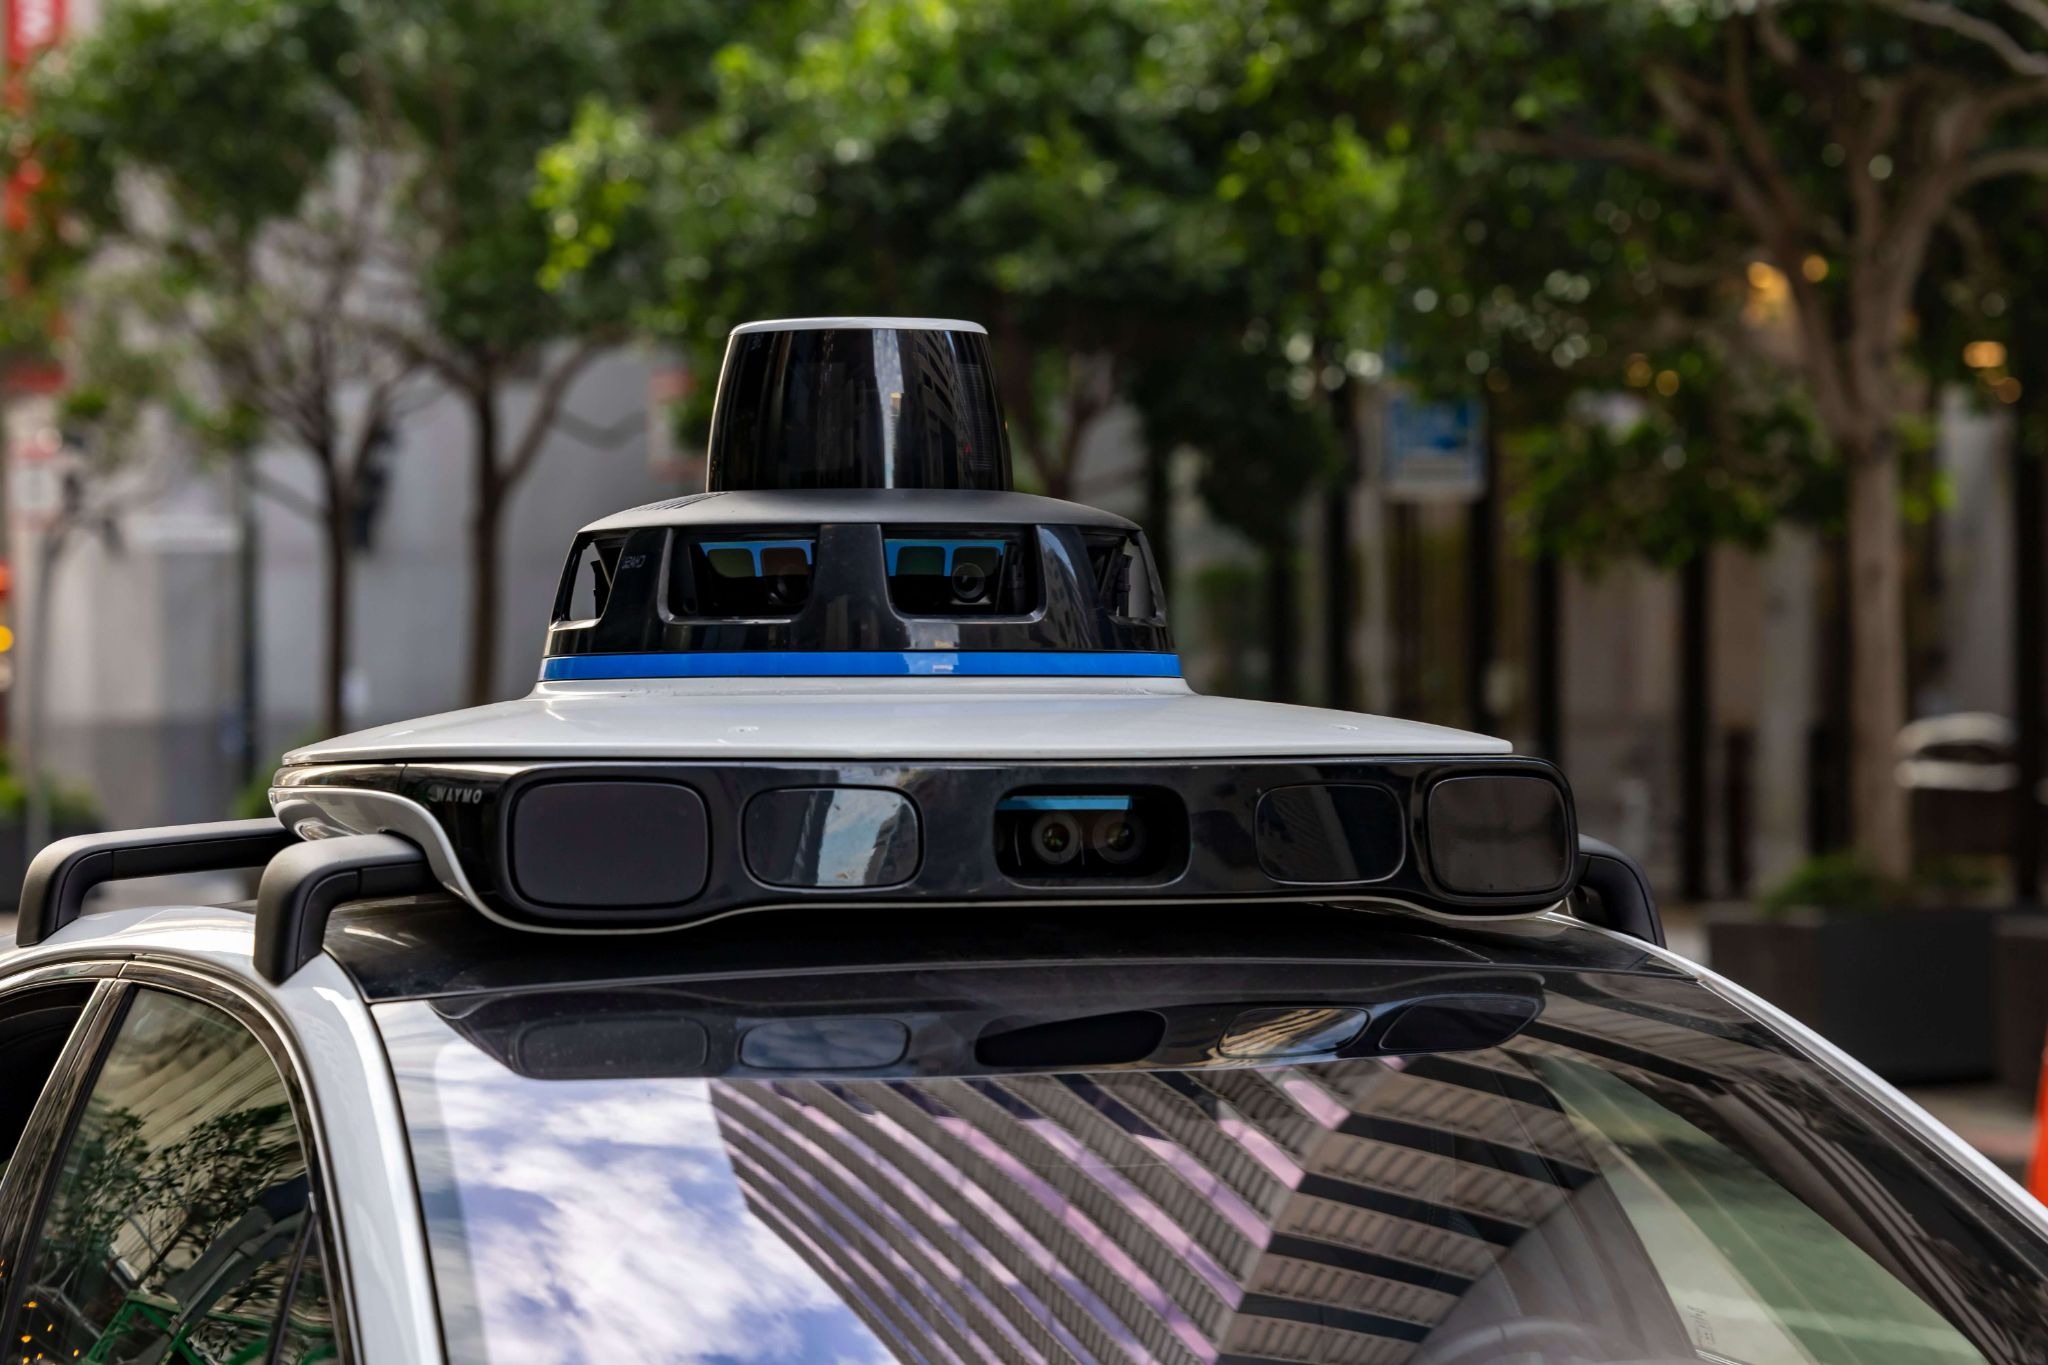
Taxi companies already do many of the things that would still be needed with an autonomous fleet. They maintain cars, deal with insurance and incidents, provide customer support and make sure enough vehicles are available. Some also already have their own depots, charging infrastructure or maintenance partners.
One possible model can already be seen in Zagreb. A local company owns and operates the autonomous fleet, while a larger ride-hailing platform brings customers. In the future, an existing taxi company could potentially have a similar role. Instead of managing cars and drivers, it could manage autonomous cars that receive bookings through a larger platform.
This does not mean platforms such as Uber will always rely on other companies to own the cars. Uber’s 2026 agreement with Rivian includes up to $1.25 billion in milestone-dependent investment and says that Uber or its fleet partners may purchase the autonomous vehicles. Uber is also developing infrastructure for autonomous fleets. Different ownership models are therefore possible.
Autonomous vehicles could also become interesting for rental and car-sharing companies, although this is probably further in the future. These businesses already manage vehicles, maintenance, cleaning, charging, bookings, customer accounts and payments, so much of the practical work is similar.
Autonomous driving could also change how rental and sharing cars are moved. Today, an employee may need to drive a car from one location to another. In the future, the vehicle could potentially do this itself within an area where autonomous driving is approved. It could even become possible for a rental car to drive itself to a customer’s pickup point.
Without drivers, it becomes especially important to understand how much time each vehicle is actually working. Every hour spent charging, being cleaned, waiting for maintenance or simply sitting unused means less time carrying paying passengers.
Some useful KPIs could be available hours per vehicle, paid trips per vehicle each day, revenue per available vehicle/day, empty kilometres, charging and maintenance downtime, cost per trip and incidents that need human help. These are most popular robotaxi industry KPIs of what a company could measure during a pilot.
For example, if cars spend too much time waiting to charge, the charging setup may need to change. A lot of empty kilometres could mean the cars are not in the right places, while too much maintenance downtime could make a vehicle more expensive to operate.
For either model, the business case depends on the partnership terms: who finances the vehicles, who carries the risk when demand is low, and how revenue and operating costs are shared. Operators should assess what remains after vehicle financing, insurance, charging, maintenance and partner fees. Depots, local service teams and reliable fleet availability could make an operator a valuable partner, but profitability still needs to be demonstrated.
One option for taxi fleets would be to work with an autonomous driving company and a larger ride-hailing platform. The local company could own or manage the cars and take care of the fleet, while customers book their rides through the larger platform.
Another option could be possible in cities where large ride-hailing platforms are not present or have limited coverage. A local company could work with an approved AV provider while using its own app, bookings, payments, customer support and fleet management.
In both cases, a company cannot simply buy autonomous cars and start offering rides. The technology needs to be approved, and local rules have to allow the service. These rules will also be different across Europe. Great Britain, for example, introduced its Automated Passenger Services permitting framework in 2026. Services similar to taxis or private hire vehicles need consent from the relevant local authority, while responsibility for the autonomous driving technology and the passenger service are treated separately.
A company does not need to have autonomous cars today to start preparing. A good first step is understanding the current fleet in detail – what each vehicle costs, how many hours it is available, how much time it spends charging or being repaired, and when cars are used the most.
Charging, cleaning, maintenance and depot processes are also worth looking at because all of these will still be needed with autonomous vehicles. A company interested in an AV pilot can then choose a location and use case, look at the local permit process and start talking to autonomous driving technology providers.
The software will also need some preparation. Customers still need to book and pay for rides, while the company needs fleet information, customer support, reporting and connections between its own systems and the AV technology. Starting with a small pilot makes it possible to test all of this before trying to build a larger service.
ATOM Mobility already provides many of the software functions used by taxi, ride-hailing, rental and sharing companies, including customer apps, bookings, payments, fleet management, maintenance tasks, analytics and APIs. Its ride-hailing software includes passenger and driver apps, dispatch, payments, fleet data, analytics and integrations. The ATOM Mobility API can also exchange data about vehicles, bookings, rides, payments, telemetry and maintenance tasks.
ATOM Mobility does not provide autonomous driving technology. This would come from a specialised AV company, and each project would have its own technical requirements and local approvals. For an AV pilot, ATOM Mobility could work with the fleet company and AV provider on the rider experience, integrations, fleet management and the data needed to measure how the pilot is working.
If you operate a taxi, rental or sharing fleet and want to explore an AV pilot, ATOM Mobility can help plan the booking and fleet-management setup, integrations and metrics you would need to test together with an AV technology partner.
Use test credentials to log in - Phone number: +1 123123123, Code: 777777


Driver App demo credentials - Email: test@atom.com, Password: driver