Traditional car rental vs peer-to-peer vs on demand car sharing
November 22, 2023
min. read

With the increasing demand for shared mobility, we've seen different business models in the car market: traditional car rental, peer-to-peer car sharing, and on-demand car sharing.
In this blog post, we're going to compare these business models. We'll look at the established traditional car rental companies and how they stack up against the newer peer-to-peer and on-demand services. We'll explore how these companies are doing financially – and make some predictions about their possible future.
Traditional car rental companies like Hertz, Enterprise, and Avis operate by owning or leasing their own fleets of vehicles. They usually have rental offices and parking lots in strategic locations such as airports and city centers. Customers looking to rent a car make reservations through the company's websites, mobile apps, or by phone. Typically, customers pay a daily or weekly rate, plus additional costs for mileage and optional services like insurance.
Avis was founded in 1946 in Detroit, and it quickly established itself as a major player in the car rental market. Avis is best known for its "We Try Harder" slogan, which was introduced in the 1960s and became a symbol of the company's commitment to customer service. Over the years, Avis has expanded its operations globally.
Avis had a strong second quarter in 2023. They reported $3.1 billion in revenue, with a net income of $436 million. The company saw an increase in usage compared to the same period in 2022, reaching 70.5%. Avis also performed better than expected on Wall Street, with earnings of $11.01 per share – surpassing the estimated $9.79.
At the end of Q2 2023, Avis had around $1.1 billion in liquidity and an additional $1.1 billion for fleet funding. Avis CEO Joe Ferraro credited the strong results to the company's ability to capitalize on the growing travel demand, particularly during the busy summer season.
Hertz was founded in 1918 in Chicago. Over the years, Hertz grew into a global brand, serving both the leisure and business travel sectors. Despite various ownership changes, it has maintained a strong presence in the car rental market.
Hertz also reported a healthy second quarter in 2023. They made $2.4 billion in revenue, mainly due to high demand – rental volume increased by 12% compared to the previous year, and their average fleet grew by 9%.
Each vehicle brought in an average of $1,516 per month during the quarter, thanks to a usage rate of 82%, which was 230 basis points higher than in Q2 2022. As of June 30, 2023, Hertz had $1.4 billion in liquidity, with $682 million in unrestricted cash. Overall, Avis' old rivals Hertz are doing quite well too.
Peer-to-peer car sharing allows private vehicle owners to offer their cars for rent through platforms like Turo and Getaround. The vehicles are distributed across various neighborhoods and residential areas, offering a decentralized and more flexible system. Customers can use these platforms to find and reserve their vehicles of choice.

Turo, founded in 2009, began as RelayRides and was later rebranded. Turo offers an online platform that allows individual car owners to rent out their vehicles to other people when they are not using them. The company provides a marketplace where people can list their cars for rent, and renters can search for and book vehicles for short-term use.
Turo has gained popularity as a more flexible and often cost-effective alternative to traditional car rental services. It allows car owners to monetize their vehicles when they're not in use and provides renters with a wide selection of cars to choose from.
Turo, valued at $1.2 billion in 2019, has seen promising financials. In 2022, they earned $746.59 million, up 59% from the previous year, with 320,000 vehicle listings. They went from substantial losses in 2019 and 2020 to a net income of $154.66 million in 2022.
Turo also grew its marketplace, engaging with 160,000 active car owners and 2.9 million riders worldwide by the end of 2022. However, according to their S-1 filing, they anticipate increasing expenses in the future, which might challenge their profitability.
Turo applied for an IPO on the Nasdaq in 2022 but didn't proceed. The IPO plans were delayed, likely due to challenges like the 2022 tech downturn. However, recently, Turo revived its plan to go public and could list their shares in the fall of 2023.
Getaround is another popular peer-to-peer car-sharing platform that allows individuals to rent out their personal vehicles to others when they are not using them. It's often referred to as the "Airbnb of cars." Introduced in 2011, it is currently accessible in over 1,000 cities in the United States and Europe.
In 2022, Getaround earned $62.3 million in revenue. However, they reported an EBITDA of -$25.0 million, indicating that its operating expenses exceeded its earnings. Overall, the company experienced a net loss of -$46.8 million for the year. Getaround's total assets were valued at $217.1 million.
During its public market debut in 2022, Getaround witnessed a significant decrease in its share value, plummeting by as much as 65%.
In March 2023, the company got a notice from the New York Stock Exchange saying it didn't meet the requirements. This was because their average global market capitalization over 30 consecutive trading days fell below $50 million, and their reported stockholders' equity was also below $50 million.
Overall, Getaround's stock market troubles and weak finances make their future uncertain for now.

On-demand car sharing services like Zipcar and Share Now (formerly Car2Go) maintain their own fleets, which are parked throughout cities in designated spots or on the streets. Customers can access these vehicles in real-time using mobile apps. The pricing structure usually includes fuel, maintenance, and insurance.
Share Now, a German carsharing firm born from the merger of Car2Go and DriveNow, now operates as a subsidiary of Stellantis' Free2Move division, offering car sharing services in European urban areas. It has over four million registered members and a fleet of 14,000+ vehicles across 18 European cities.
In late 2019, ShareNow announced the closure of its North American operations due to competition, increasing operational costs, and limited support for electric vehicles. Service in London, Brussels, and Florence was also discontinued.
On May 3, 2022, Share Now was acquired by Stellantis, with the ownership now managed by Stellantis subsidiary Free2Move, following the closure of the acquisition on July 18, 2022.
CityBee, founded in 2012 in Lithuania, started as a car-sharing service primarily aimed at businesses. It now operates in the whole Baltic region. Customers can choose from a variety of vehicles, including cars, vans, bikes, and electric scooters. The fleet also includes electric and hybrid cars. CityBee takes care of insurance, fuel, and parking fees in CityBee areas.
In 2022, CityBee reported a sales revenue of €33,168,028, slightly down from the previous year's €39,814,173. However, the company's profitability surged, with a profit before taxes of €2,193,820 – a substantial increase from the €968,722 in 2021. This also resulted in a higher profit margin of 6.61% in 2022, compared to 2.43% in 2021.
CityBee saw its net profit rise to €1,857,517 in 2022, a substantial increase from the €876,986 in 2021. The company's equity capital also grew to €4,688,176, indicating a stronger financial foundation. CityBee shows that on-demand car sharing can succeed with the right approach in the right market.

The shared car mobility market is large enough for different solutions to exist together – especially with car ownership costs going up. Companies like Hertz and Avis demonstrate that the traditional rental model remains relevant and holds significant profit potential.
Despite financial challenges, peer-to-peer car sharing and on-demand car sharing are attracting a fresh customer base. Peer-to-peer car sharing offers a more personal touch by letting people rent their own vehicles. On-demand car-sharing services are a great solution for urban residents, offering quick pay-as-you-go access to vehicles.
While the position of traditional car rental giants might seem unshakeable, it's a fast-moving, evolving market. Regional success stories – such as CityBee – certainly prove that challengers are not asleep.
If you own a fleet, operate a car rental business, or are looking to get into one, ATOM Mobility can equip you with an end-to-end software suite that will put you miles ahead from competition.
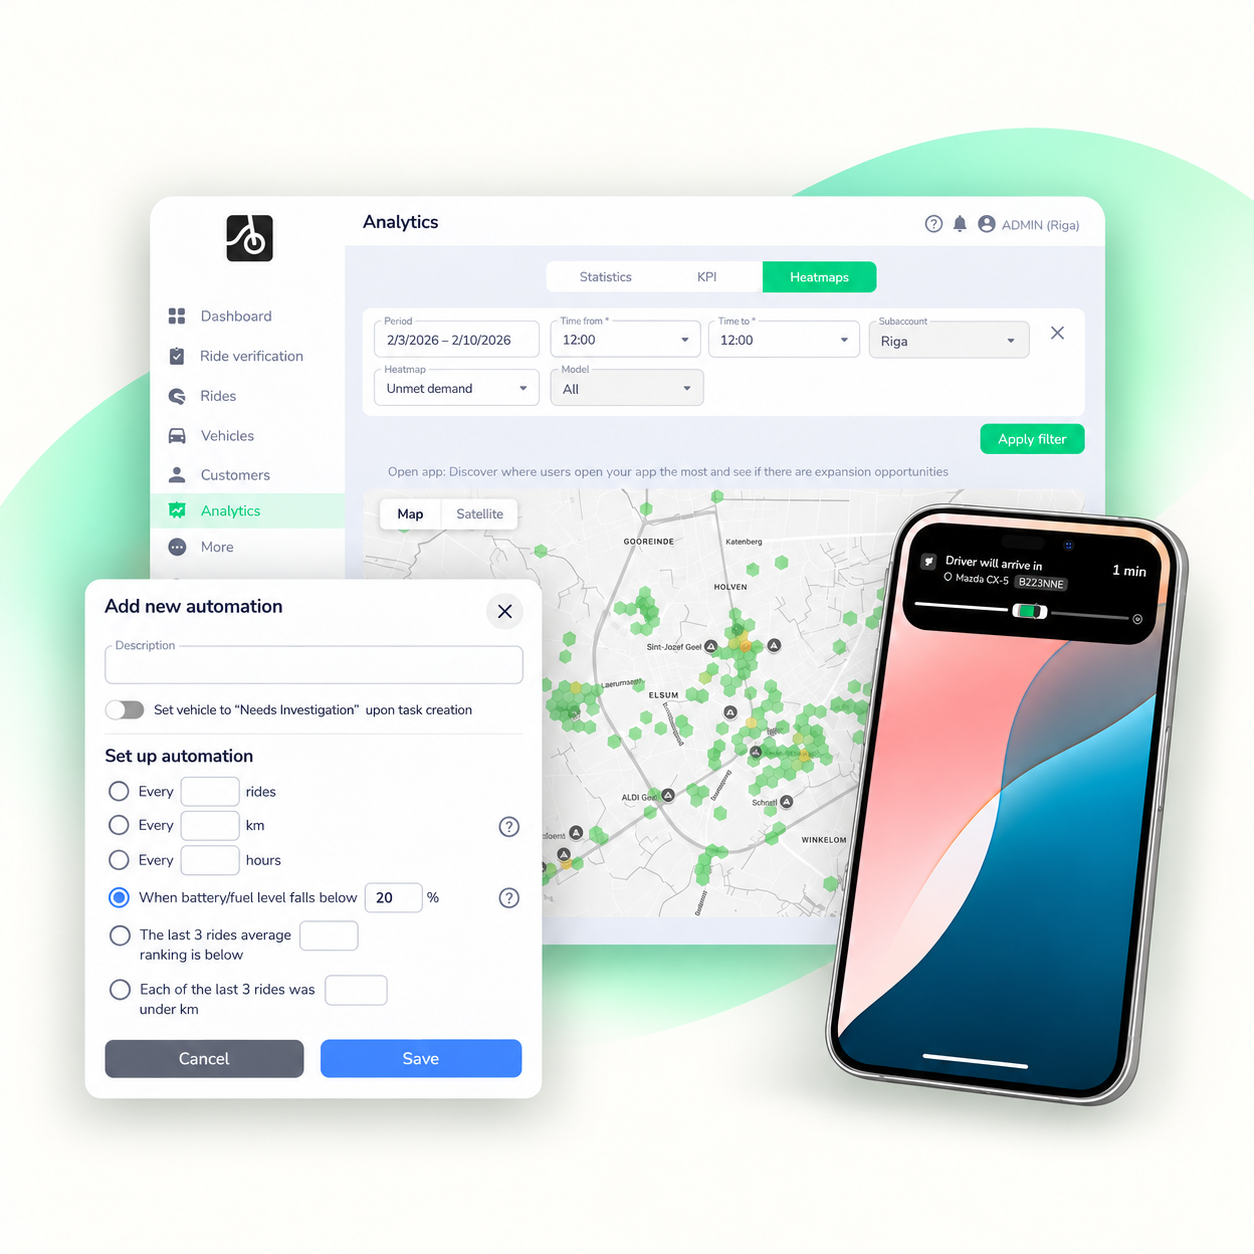
🚀 ATOM Mobility ships 7-15 new features every month, alongside smaller improvements and fixes. Explore five recent highlights: unmet demand heatmaps, automated fleet tasks, field-team performance tracking, new subscription types, and lock-screen ride updates - helping operators run more efficient fleets and improve the rider experience.
Knowing where customers need vehicles, keeping field teams productive, and giving riders reasons to return are everyday priorities for mobility operators. Every month, ATOM Mobility ships 7-15 new features, alongside smaller improvements and fixes. Here are five highlights from our recent releases - and how they can help operators improve fleet performance and the customer experience.
A customer opens your app, finds no vehicle nearby, and leaves. Your ride history alone won’t show you that missed opportunity.
The Unmet Demand heatmap highlights areas where users open the app but cannot find an available scooter, bike, or car within 1000 metres radius. Beyond colour-coded hexagons, on zoomed in view it shows the number of unique users who searched for a vehicle in each area without finding one nearby.
Use these insights to identify gaps in fleet coverage, prioritise rebalancing, and assess potential parking locations. Alongside seeing where rides happen, you can now understand where potential demand goes unmet.

Keeping a fleet ready for customers means staying on top of maintenance, charging, refuelling, and service quality. As your fleet grows into hundreds of vehicles, manually tracking when each vehicle needs attention becomes increasingly time-consuming.
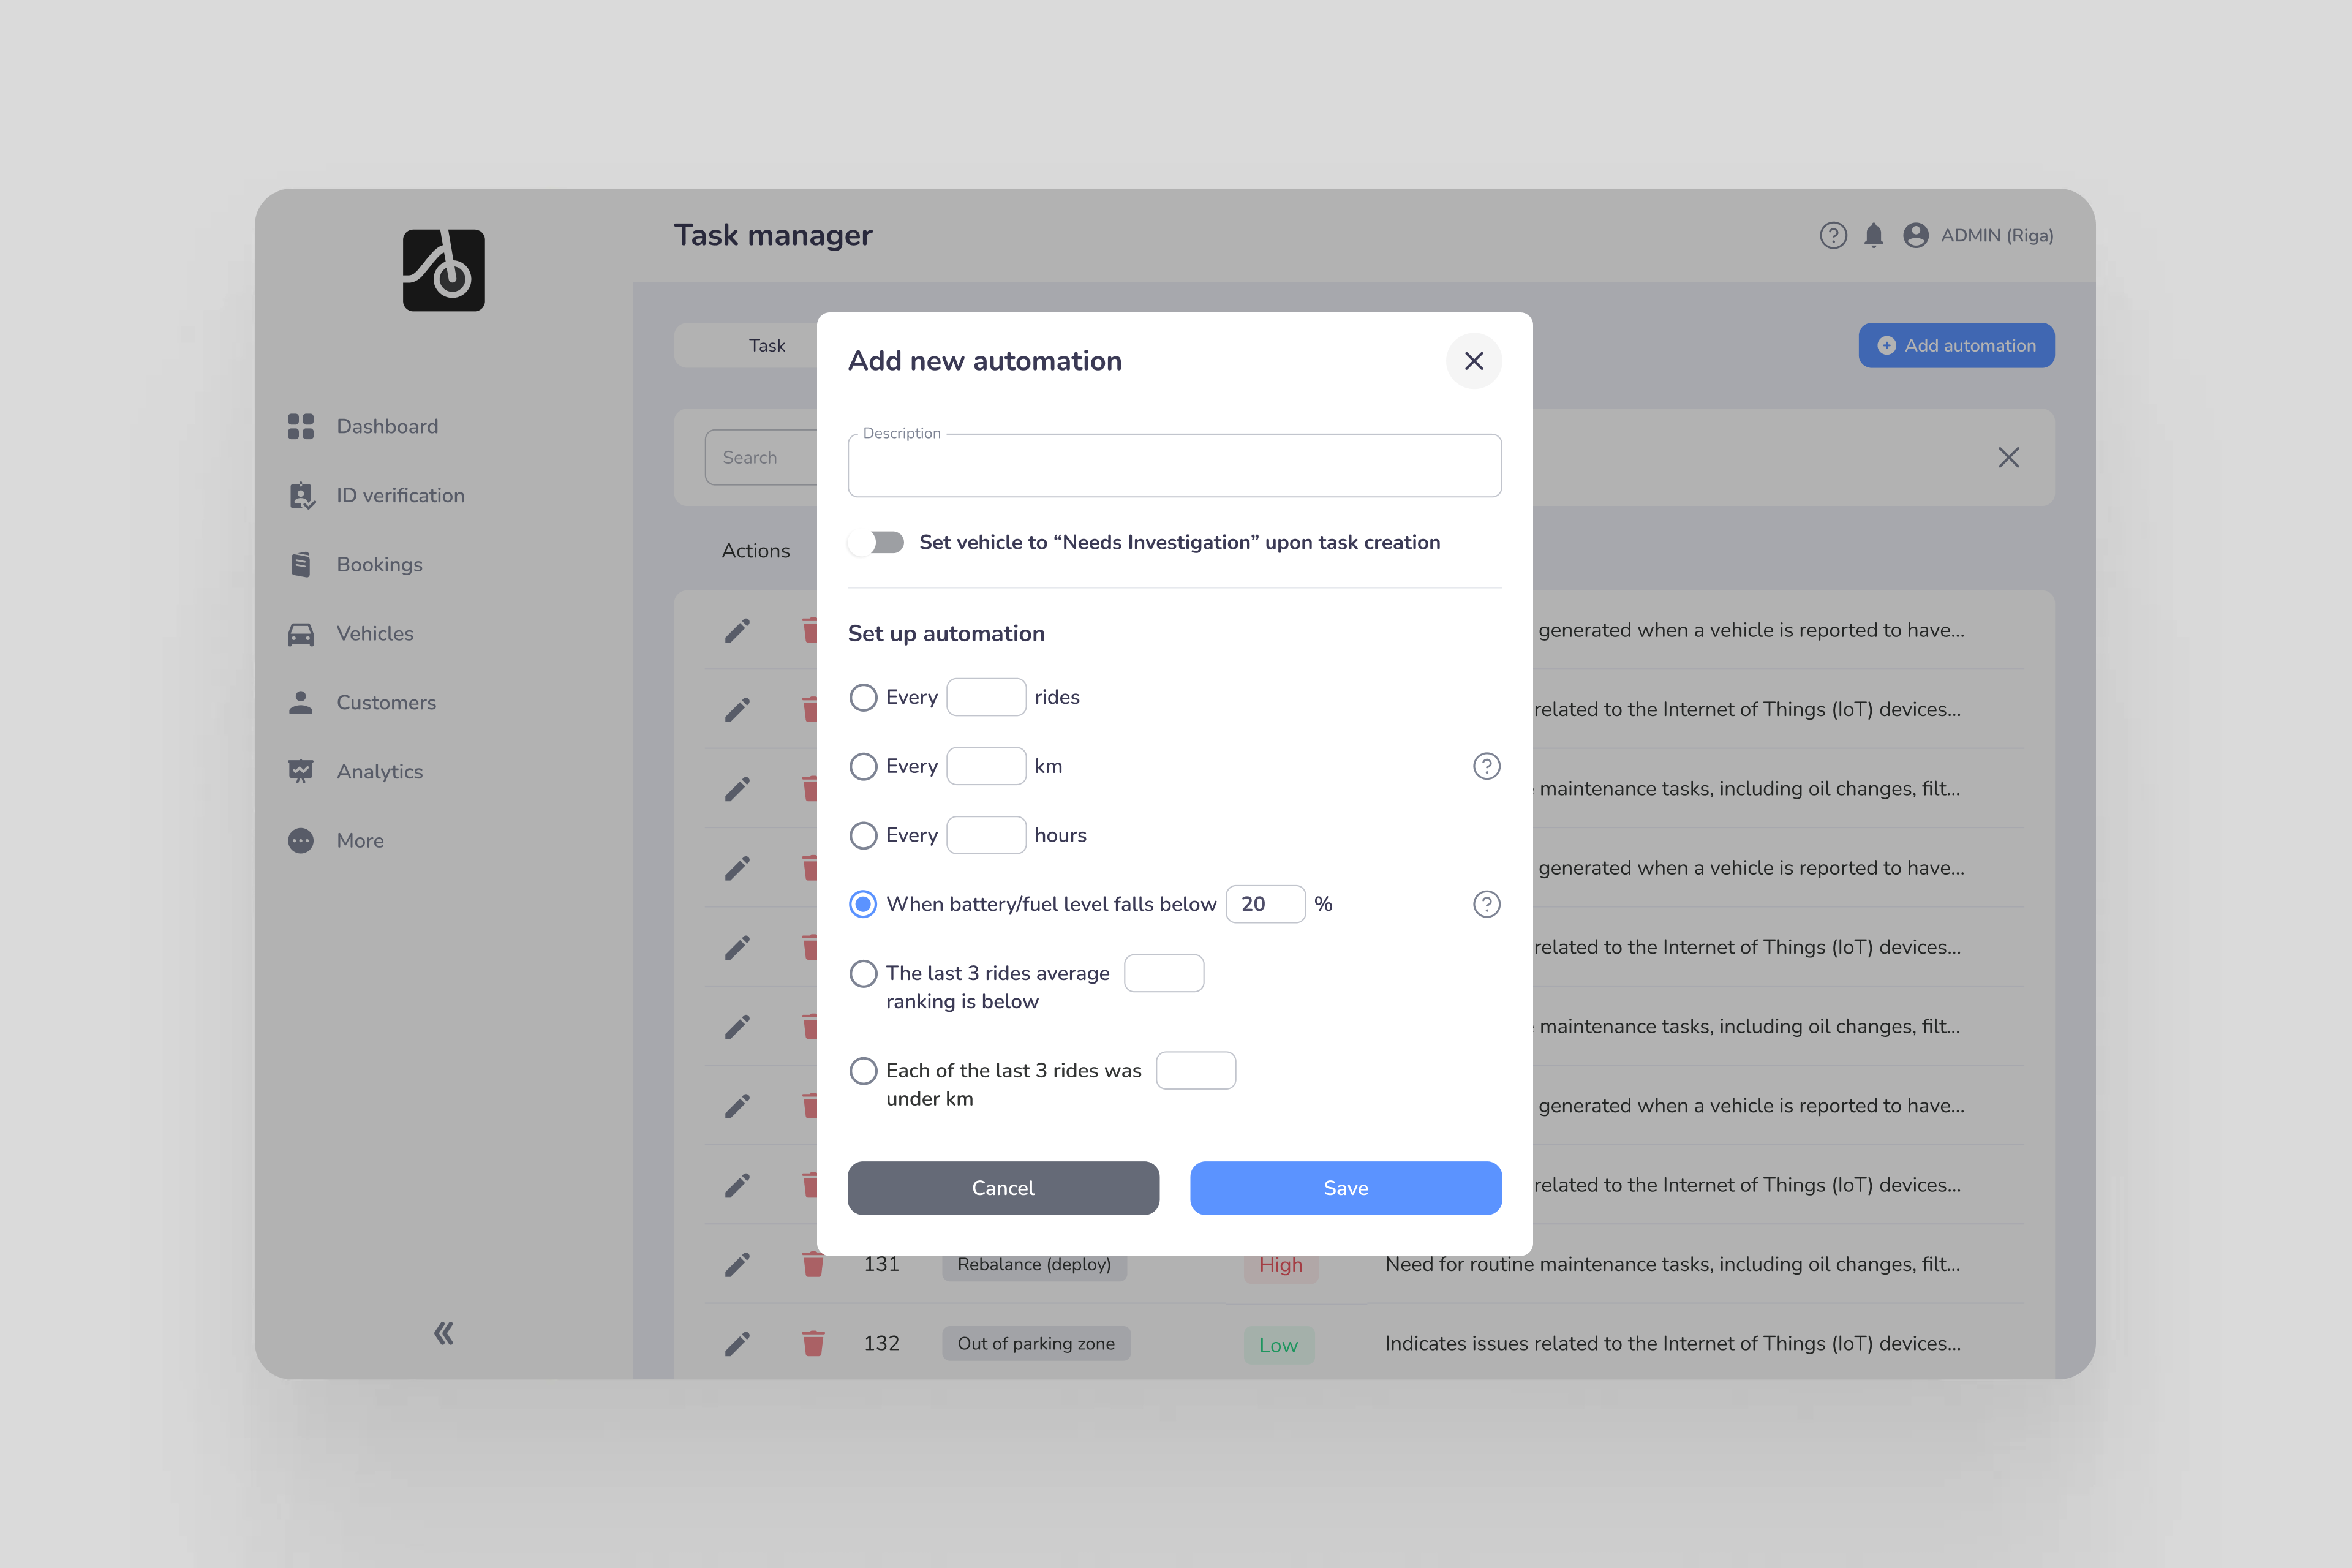
Task Manager automations turn vehicle usage, condition, and ride feedback into actionable tasks. Operators can configure tasks to be created:
These rules can support routine maintenance, trigger charging or refuelling tasks, and flag vehicles for inspection after low ratings or unusually short rides. For rebalancing tasks, if a customer uses the vehicle before collection, the task is automatically removed. This reduces manual monitoring and helps your team respond to vehicles that need attention.
How long do tasks take? Where does your team spend its time? Which operational bottlenecks need attention?
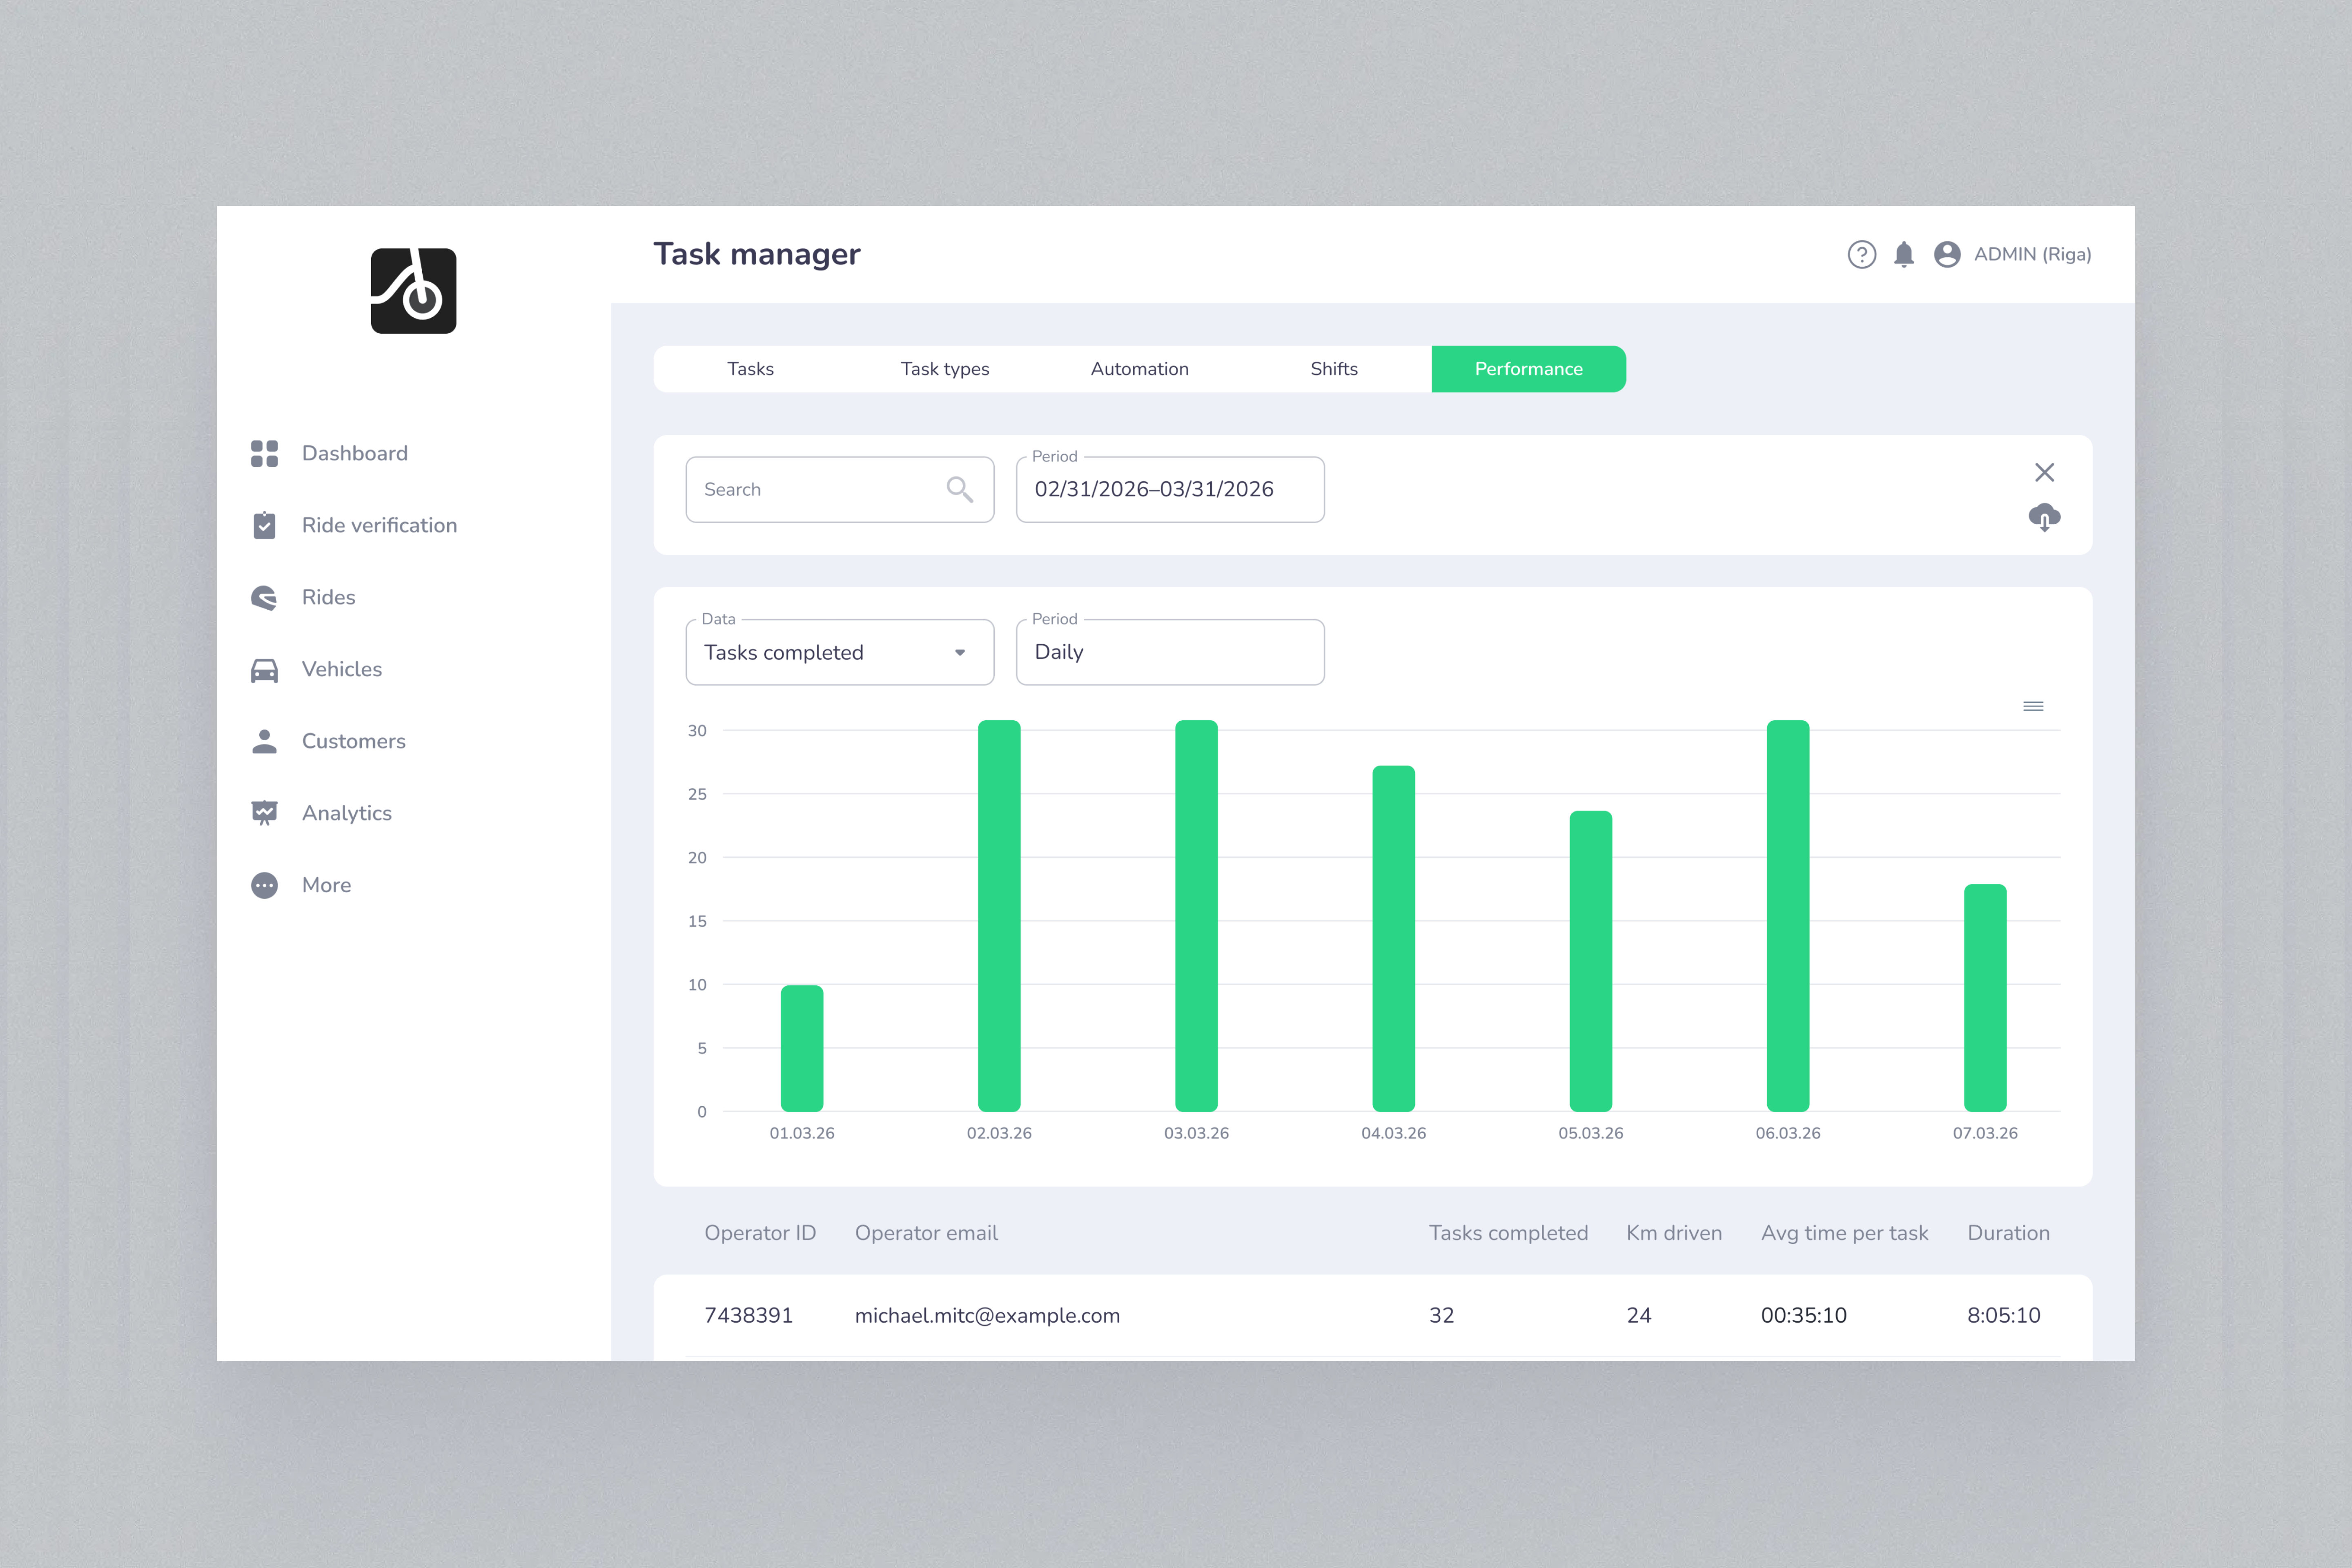
New Shifts and Operator Performance views give vehicle sharing and digital rental operators visibility into shift status and duration, distance driven, completed tasks, and average time per task.
Managers can use these insights to investigate delays, improve routes, and identify training needs. For example, longer task completion times could prompt a closer look at travel distances, workload, or the processes used at each location. Comparing results alongside task types and working conditions helps turn performance data into practical operational improvements.
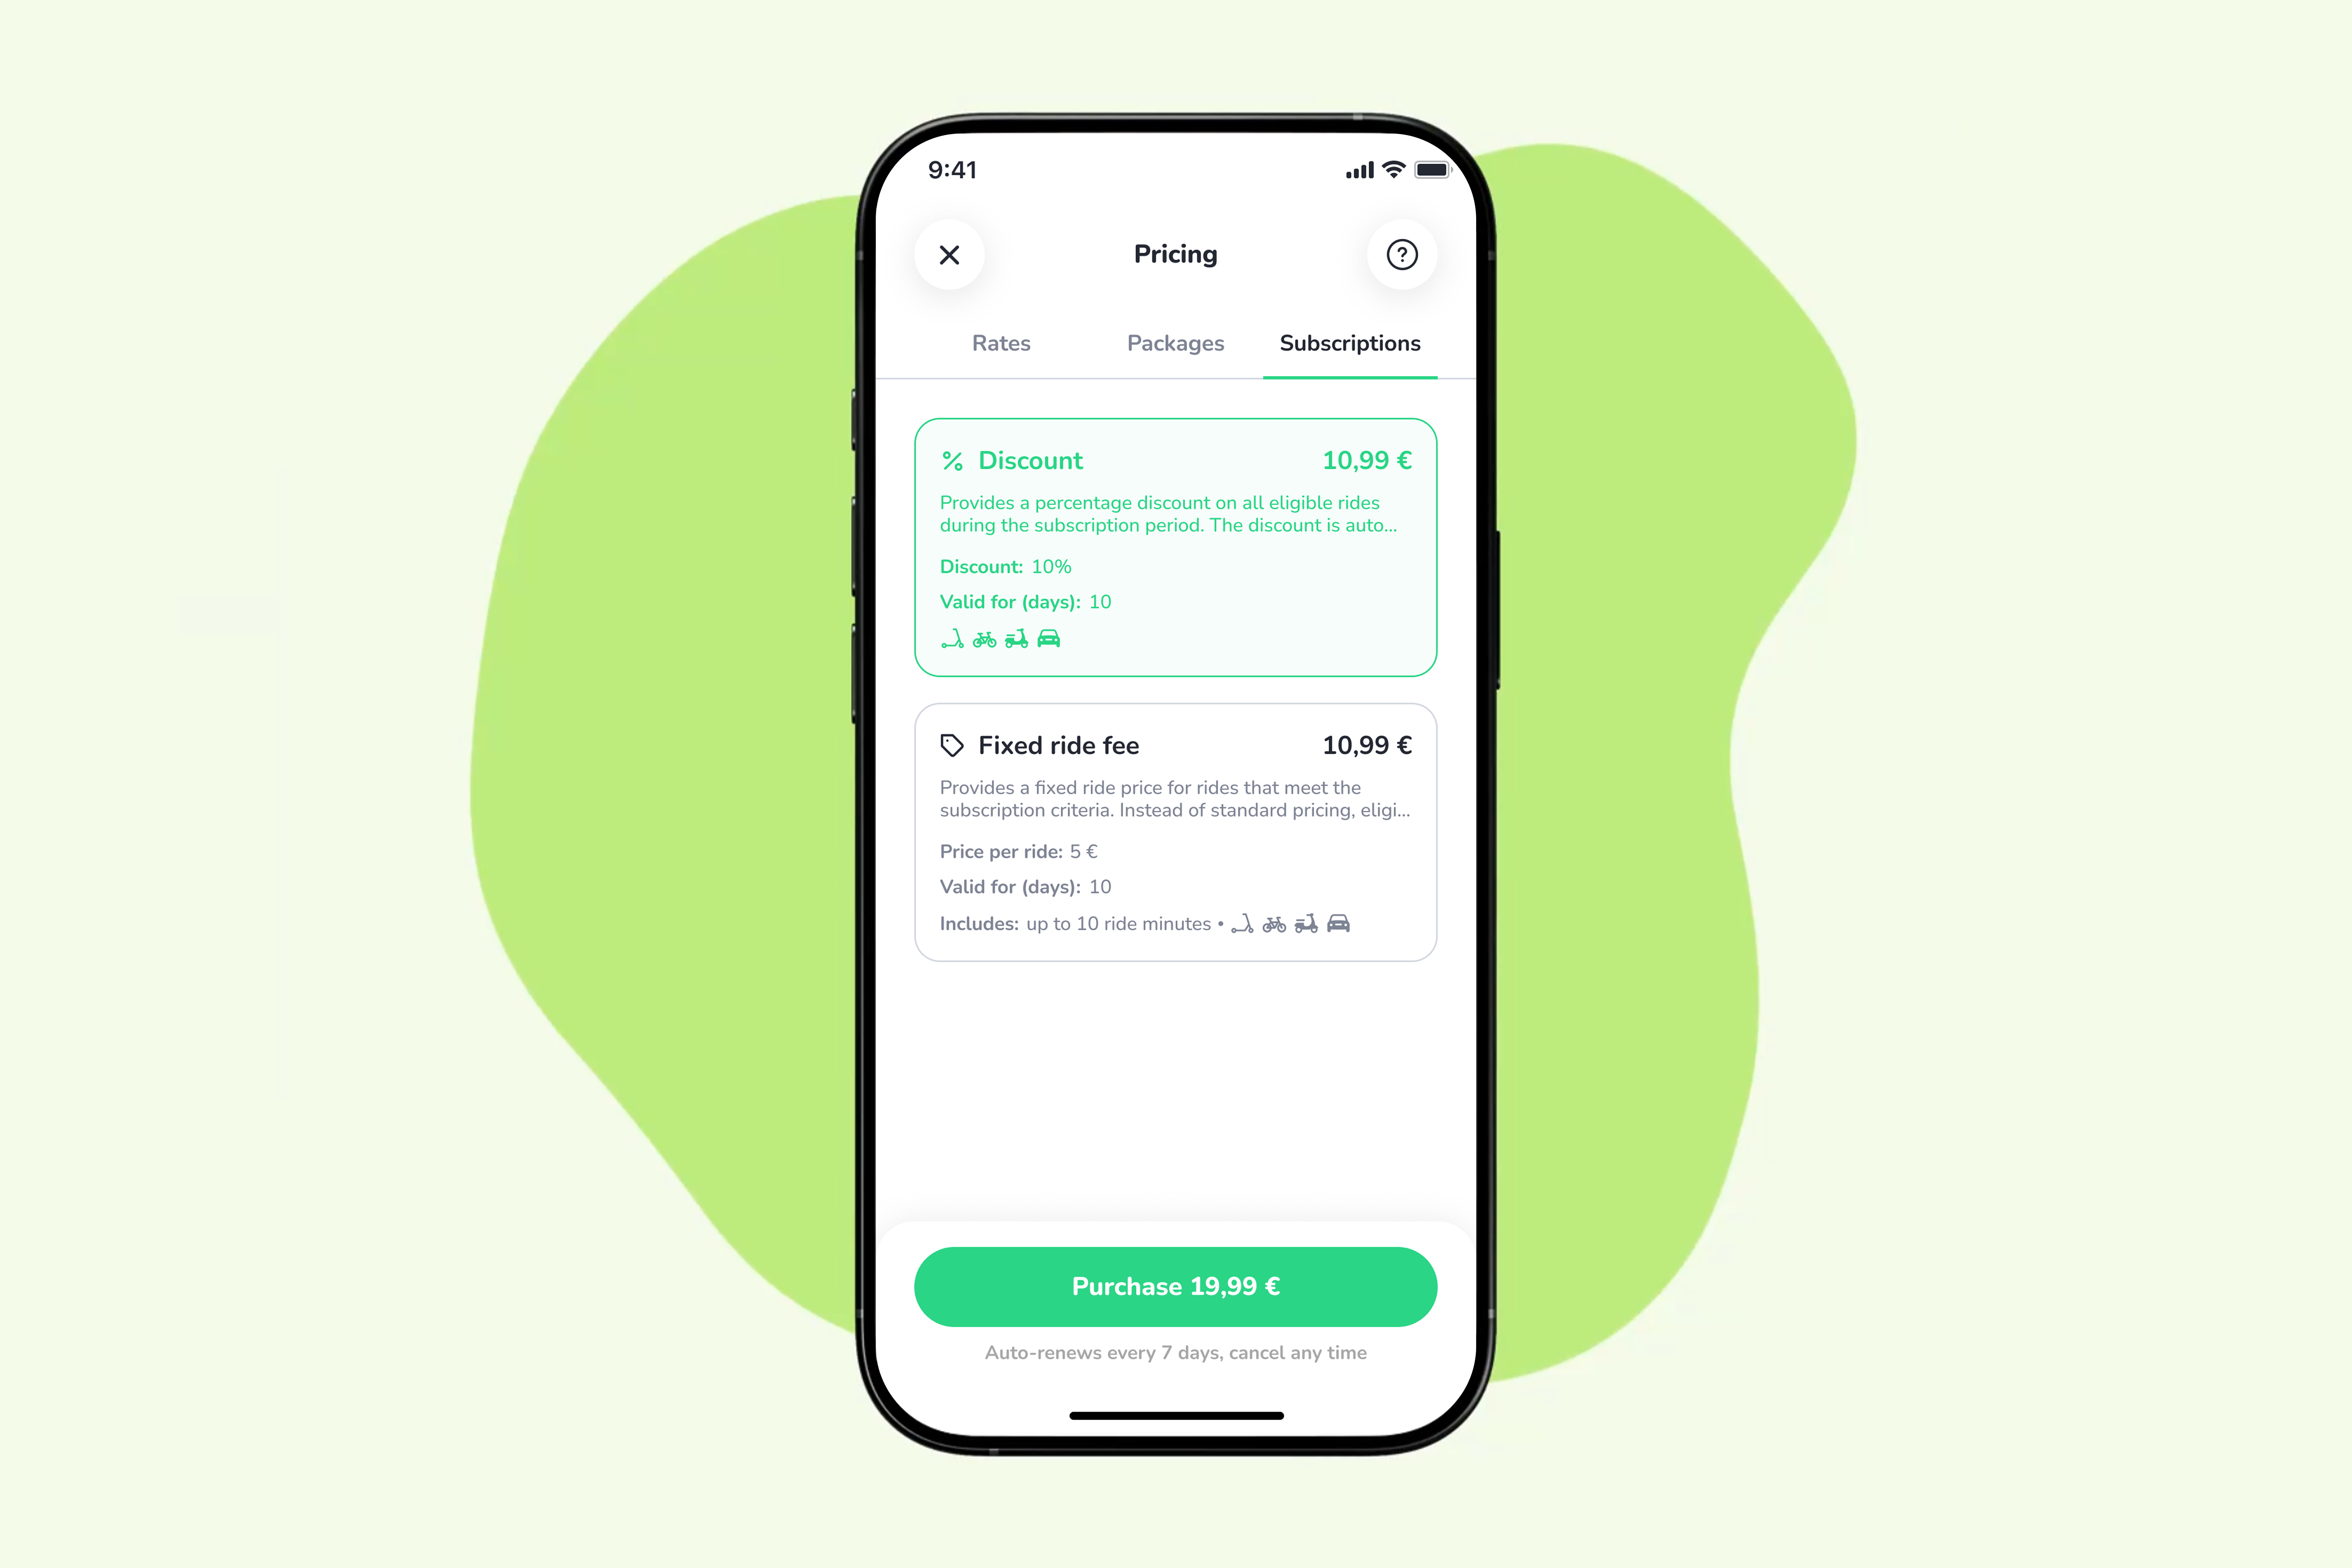
Different customers have different riding habits. Your subscriptions should reflect that.
ATOM Mobility now supports two additional subscription types:
These options let operators design offers around frequent riders and short-distance commuters. For example, you could offer subscribers a percentage discount on eligible rides or a predictable flat fee for qualifying short trips. Operators gain more flexibility to test offers that encourage repeat usage while fitting their pricing strategy.
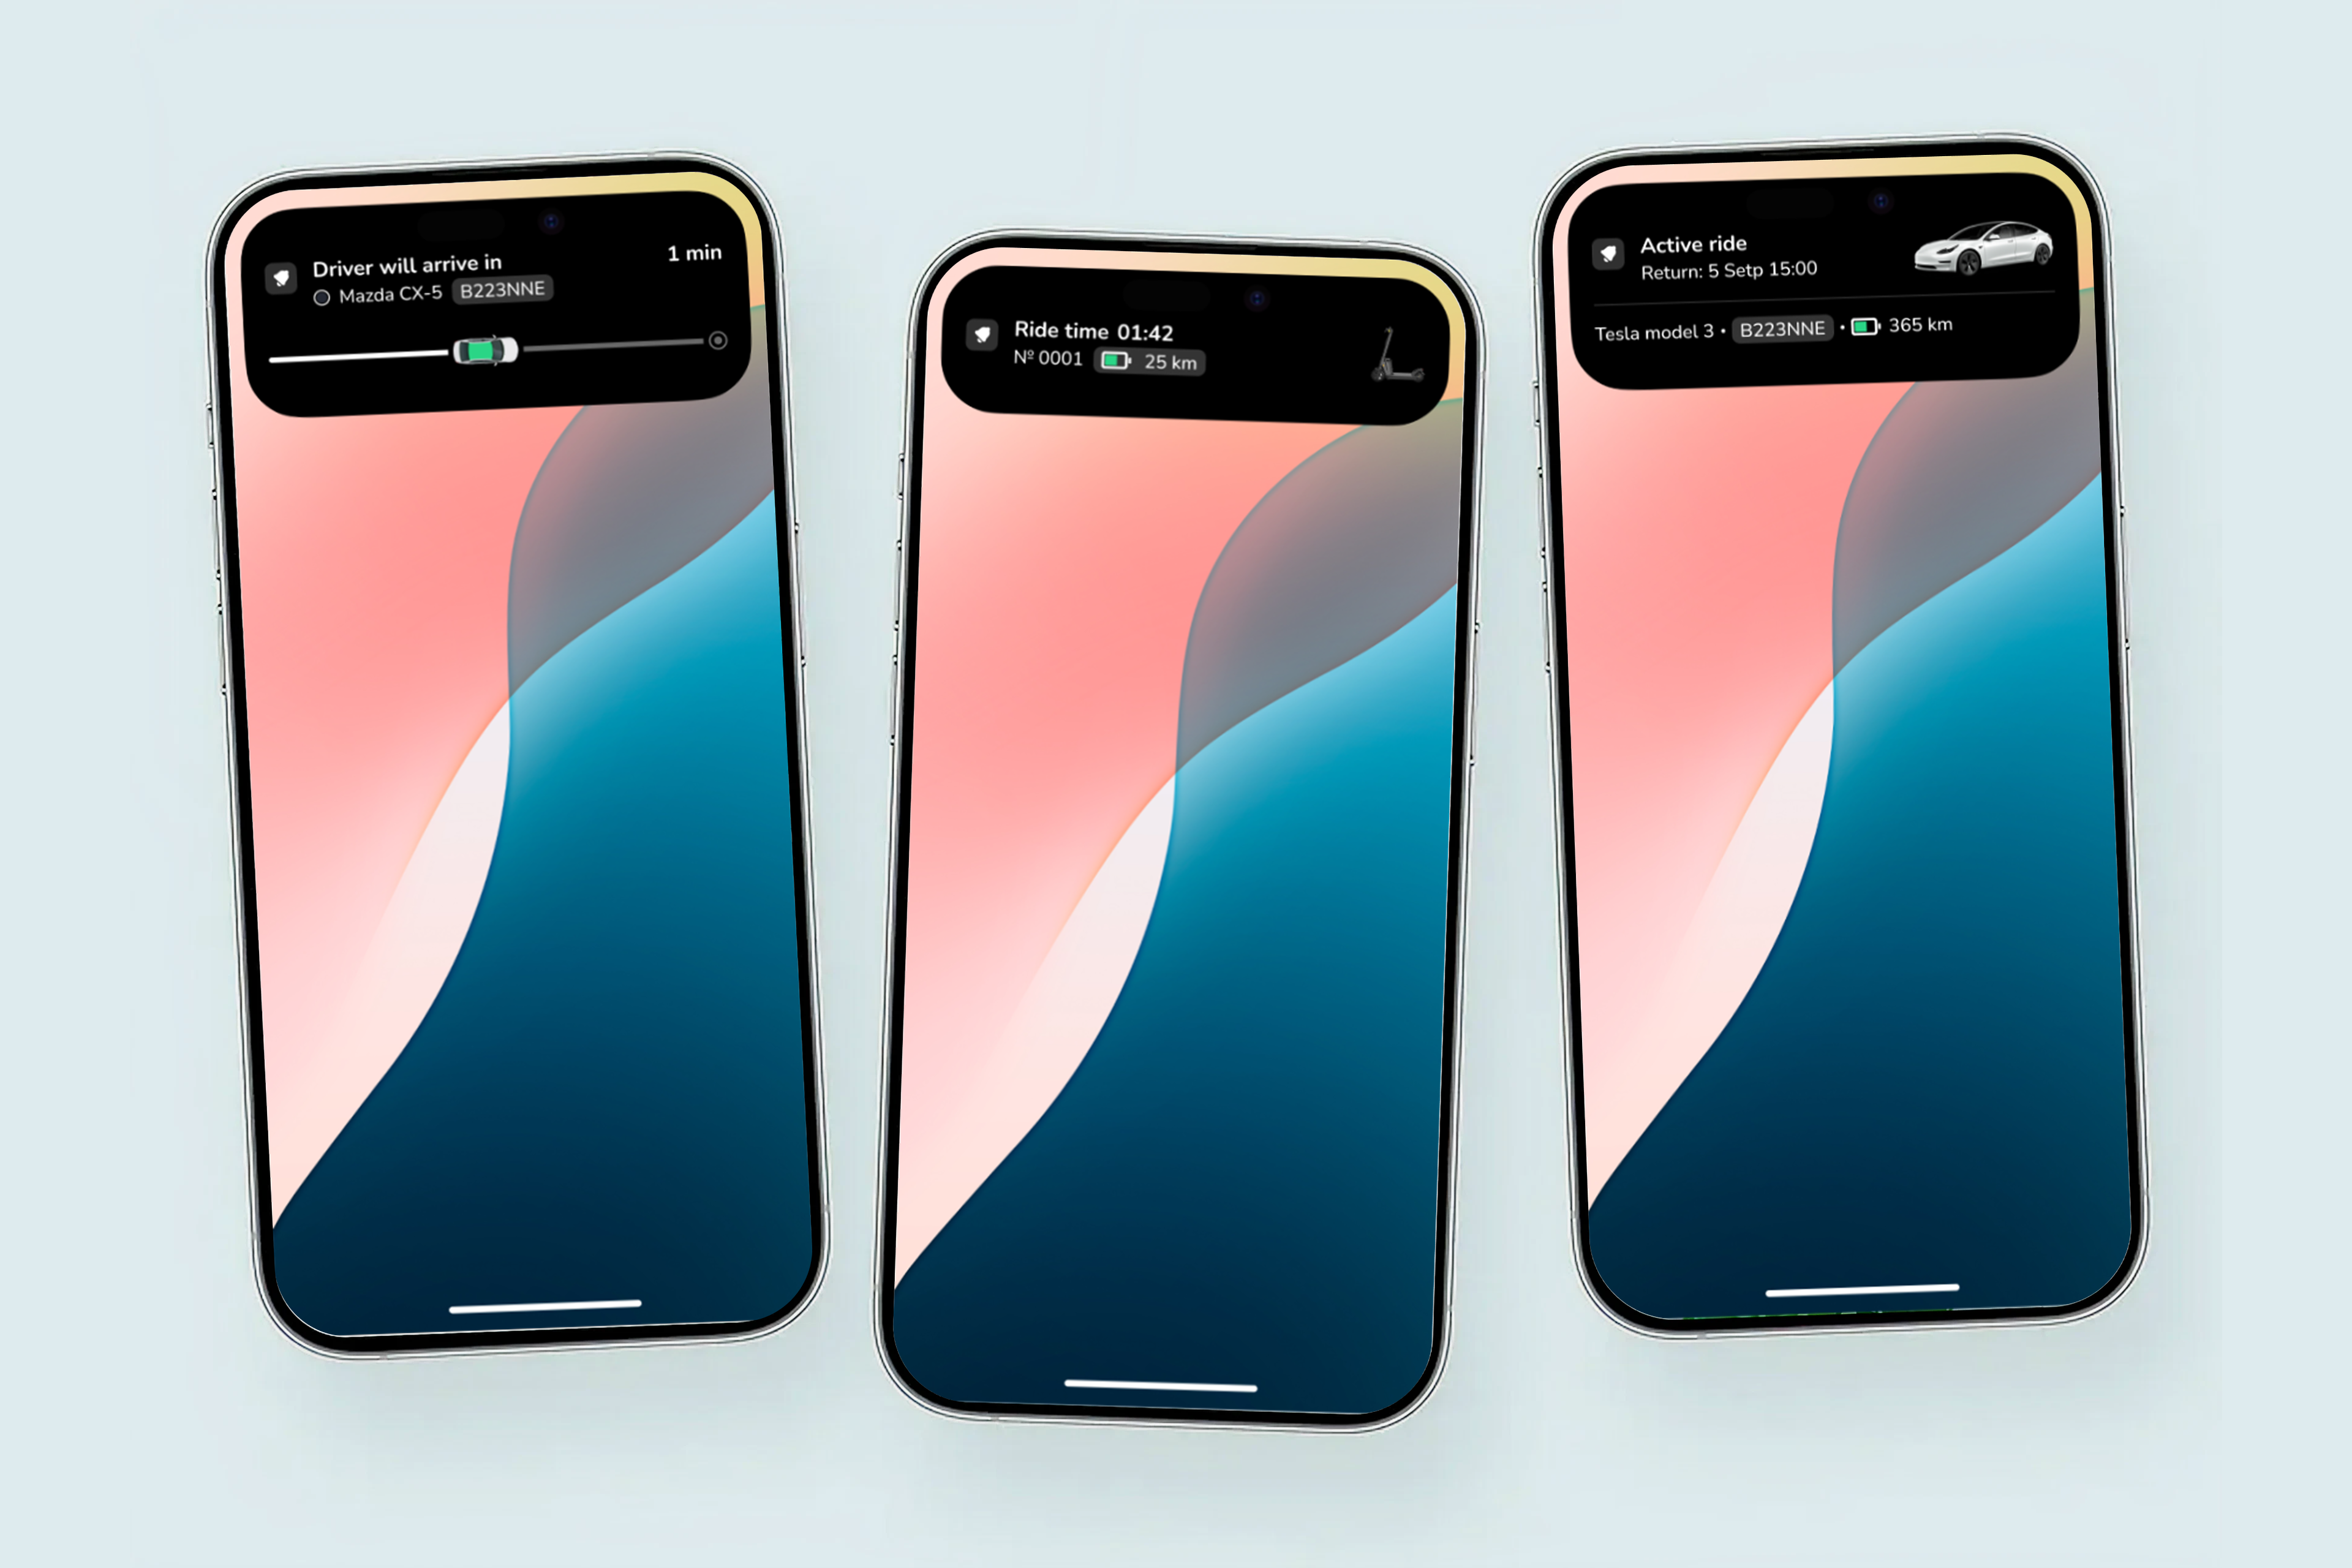
Checking an active trip should be simple.
Live Activity lets customers view key ride information directly on their phone lock screen without repeatedly opening the app. Depending on the service, this can help them follow an active ride or a driver’s arrival.
Making this information readily accessible gives customers a more convenient way to stay informed throughout their journey.
These five releases are part of ATOM Mobility’s ongoing product development, helping operators identify unmet demand, automate routine coordination, understand field-team performance, and improve the customer experience.
Exploring software for your mobility business? Book a demo to see how ATOM Mobility can support your fleet, team, and customers.
Explore more product updates at https://www.atommobility.com/atomupdates
🤖 Who will actually operate Europe’s robotaxi fleets? Autonomous driving may remove the driver, but it doesn’t remove the work behind the car. Robotaxis still need charging, cleaning, maintenance, depots, customer support and someone managing the fleet every day. Early projects in Zagreb, Madrid and London illustrate different stages of deployment and how AV technology providers, fleet operators and booking platforms can work together. Taxi, rental and car-sharing companies already handle many of these tasks. What would it take to turn that experience into an autonomous fleet business?
For a taxi fleet owner, autonomous vehicles may seem to remove the most important part of the current business – the driver. But even without drivers, someone still needs to take care of the cars. They need to be owned or financed, charged, cleaned, inspected and repaired. Someone also needs to manage depots, deal with incidents, help customers and make sure enough cars are available.
The first robotaxi services and tests in Europe are already showing how this could work. The company that develops the autonomous driving technology does not always own or operate the cars. The app where customers book their rides may come from another company too. This could leave an important role for taxi, rental, car-sharing and other fleet companies that already know how to manage vehicles.
A taxi company today manages both cars and drivers. Drivers need to be recruited, scheduled, paid and supported. With a driverless fleet, these tasks would eventually disappear, but most of the work related to the cars would stay.
Autonomous cars still need charging or refuelling, cleaning, tyres, inspections, repairs and insurance. They also need somewhere to park when they are not working. If there is an accident or a technical problem, someone needs to deal with it and get the car back on the road. Customer support is still needed too when there are problems with bookings or payments, or when someone leaves something in the car.
Some of these tasks may even become more important. Robotaxis are expensive, and every hour a car spends charging, being cleaned or waiting for maintenance is an hour when it cannot take passengers. Moove, for example, already provides fleet ownership, depots, charging, maintenance and 24/7 operations for autonomous vehicles.
Drivers also do more than drive: they notice damage, report faults, help passengers and respond when something goes wrong. Without a driver, these responsibilities need clear processes and dedicated support. Existing fleet experience is an advantage, but operators will need to adapt it to vehicles running without someone behind the wheel.
There can be several companies behind one robotaxi ride. One provides autonomous driving technology, another may own the cars, and a local company can take care of the fleet. A platform such as Uber can then connect the cars with passengers. Sometimes one company may do several of these things, but this is not always the case.
Zagreb is one example. Pony.ai provides the autonomous driving system, Verne owns and operates the fleet, and Uber connects it with customers through its app. Autonomous rides became commercially available through Uber in August 2026 with a licensed operator onboard. On 10 September, Pony.ai and Verne also started fully driverless passenger test rides on a 22-kilometre route connecting parts of Zagreb with the airport. These are still limited test rides, not a fully driverless service across the whole city.
A similar model is being tested in Madrid. WeRide, Uber and AVOMO received permission in September 2026 to start testing and mapping under Spain’s ES-AV framework. The first 20 vehicles have an onboard specialist. WeRide provides the autonomous technology, Uber connects the cars with passengers, and AVOMO takes care of fleet operations. Commercial operations are planned for later in 2026, but the current permit is for testing and preparation rather than a general driverless taxi service.
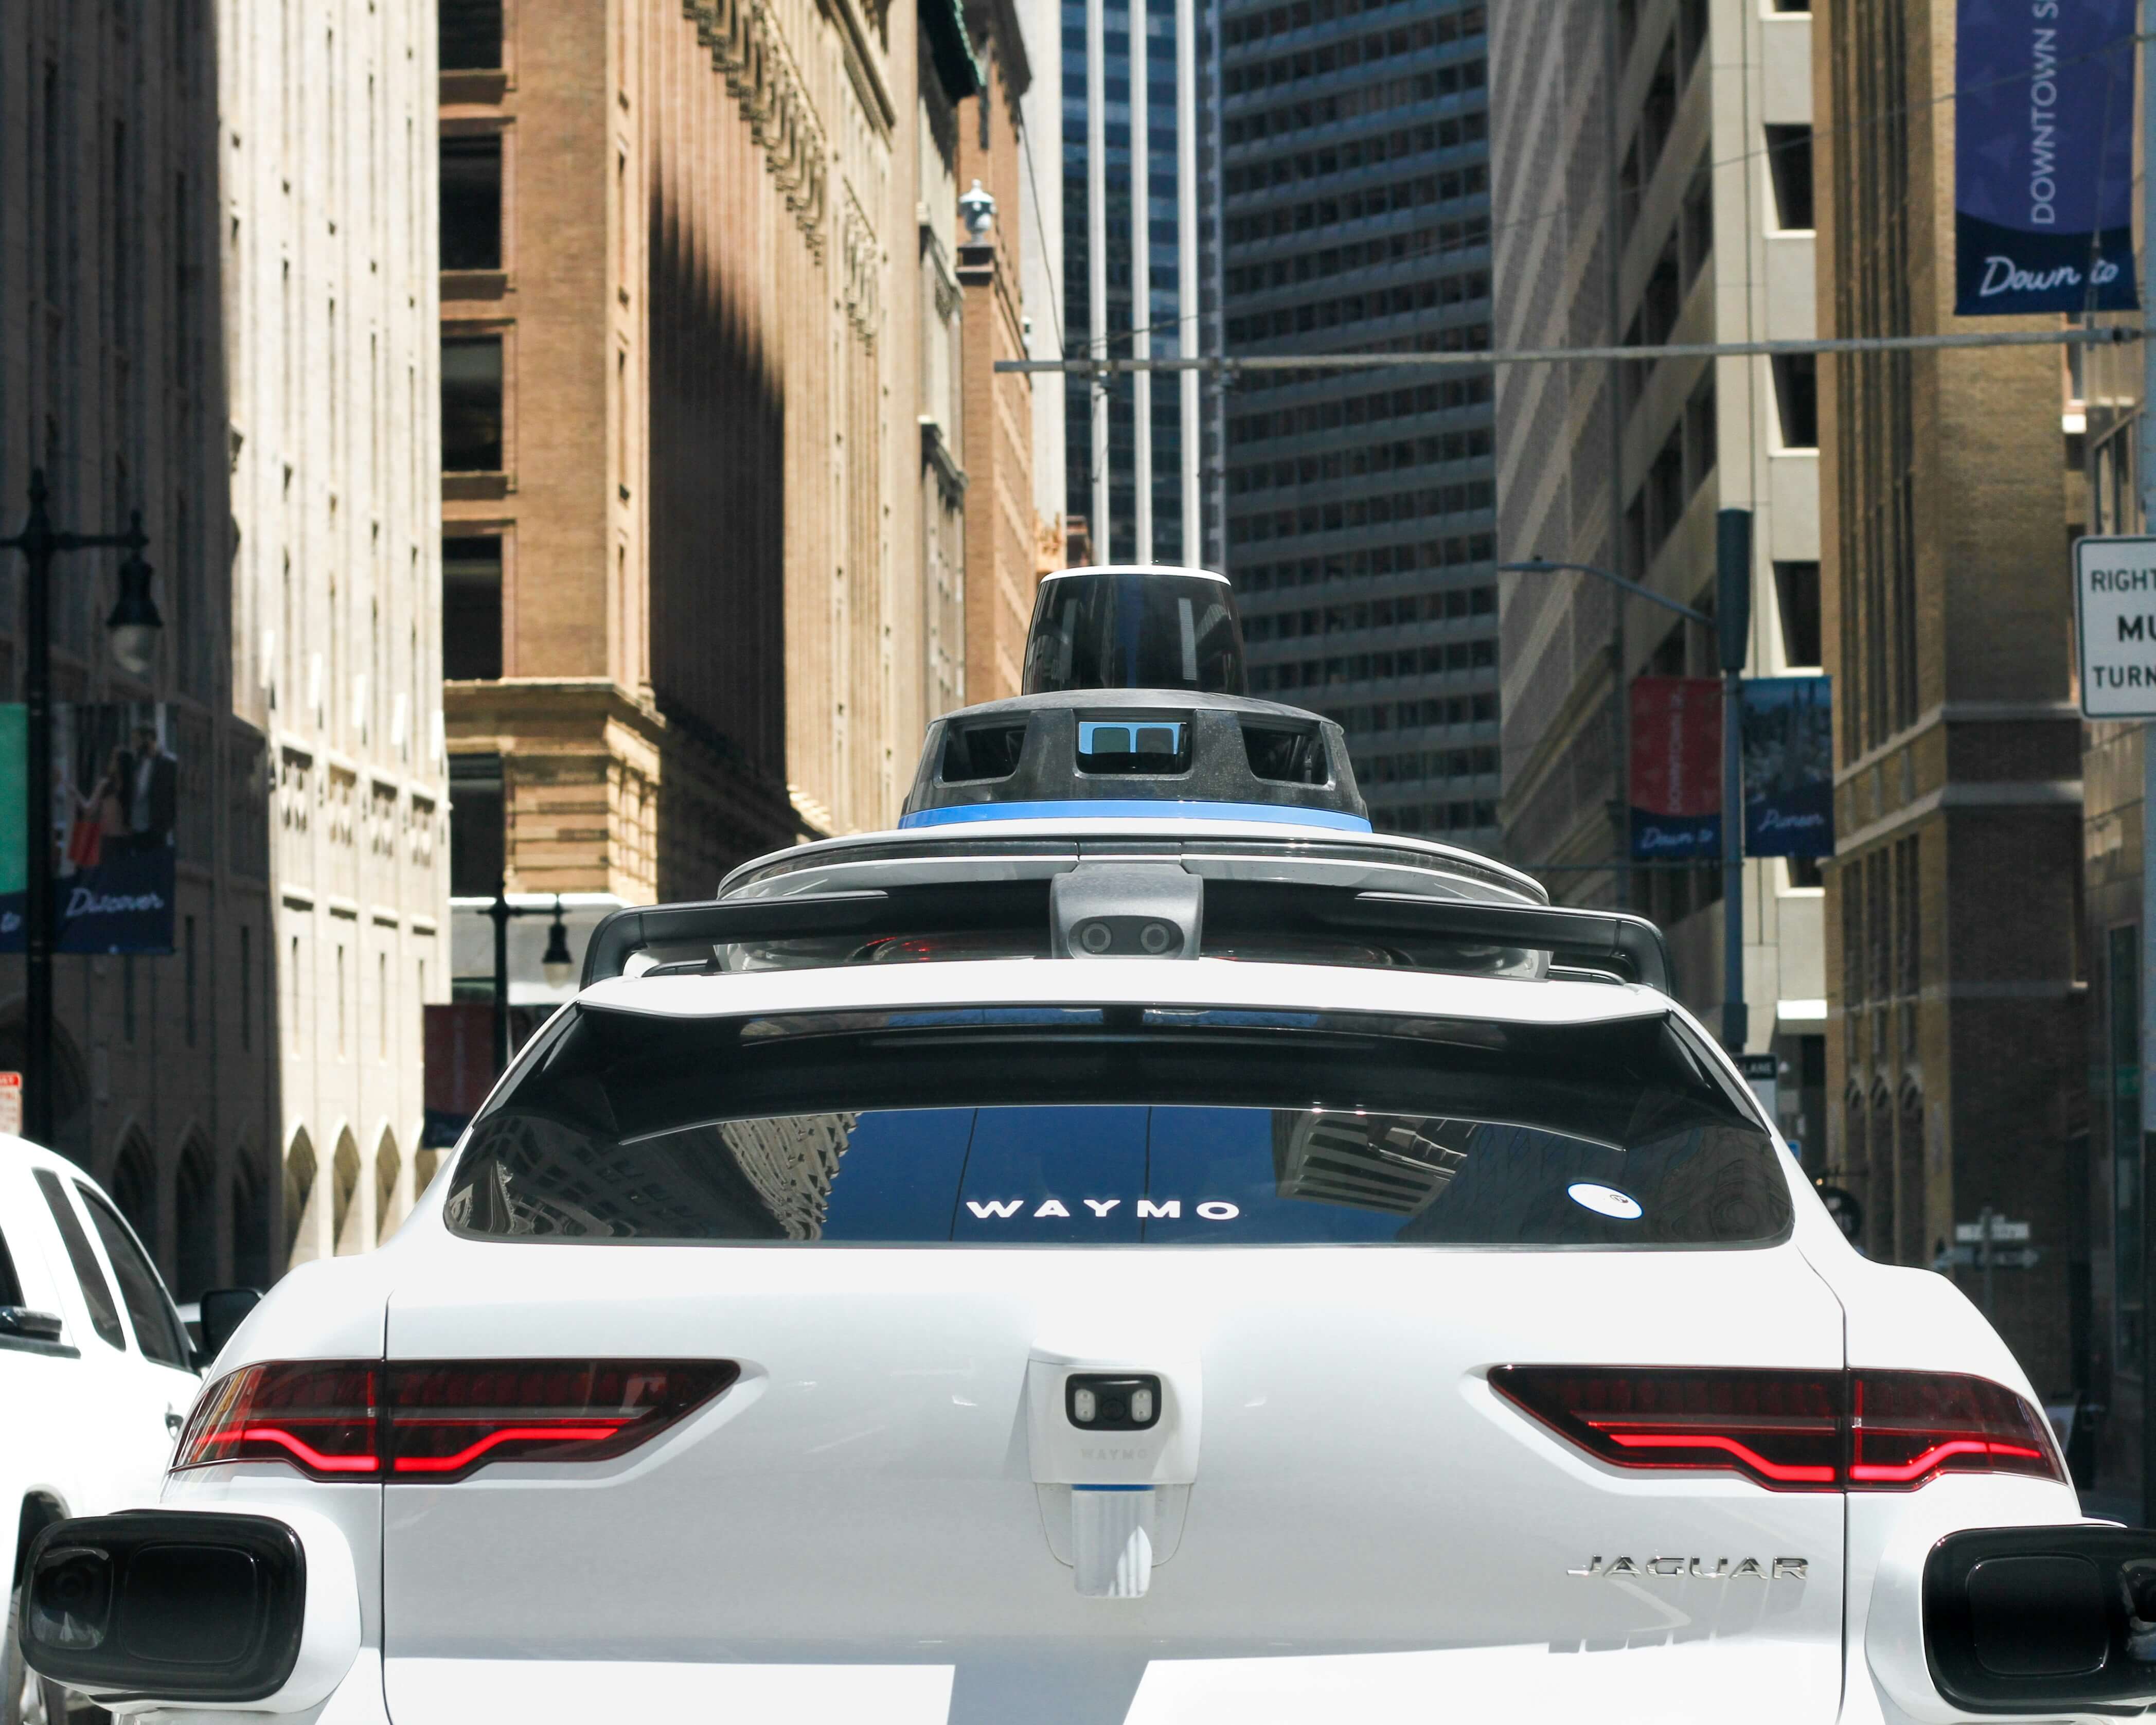
In London, Wayve and Uber launched supervised autonomous passenger rides in September 2026. Customers can be matched with an autonomous vehicle through the Uber app, but there is still a licensed driver in the car.
The plans for the next few years are already much bigger. Pony.ai and Uber announced in August 2026 that they plan to deploy more than 2,000 robotaxis in Europe, starting with Zagreb and later expanding to four more European cities.
Bolt and Lucid announced another partnership in September, with Bolt aiming to deploy at least 25,000 autonomous Lucid vehicles across European cities. This is a future target, not 25,000 cars already operating today.
How these fleets are owned and operated may also be different from one city to another. Local regulations, available vehicles, charging and depot infrastructure and partnerships will all have an effect on how each service is set up.
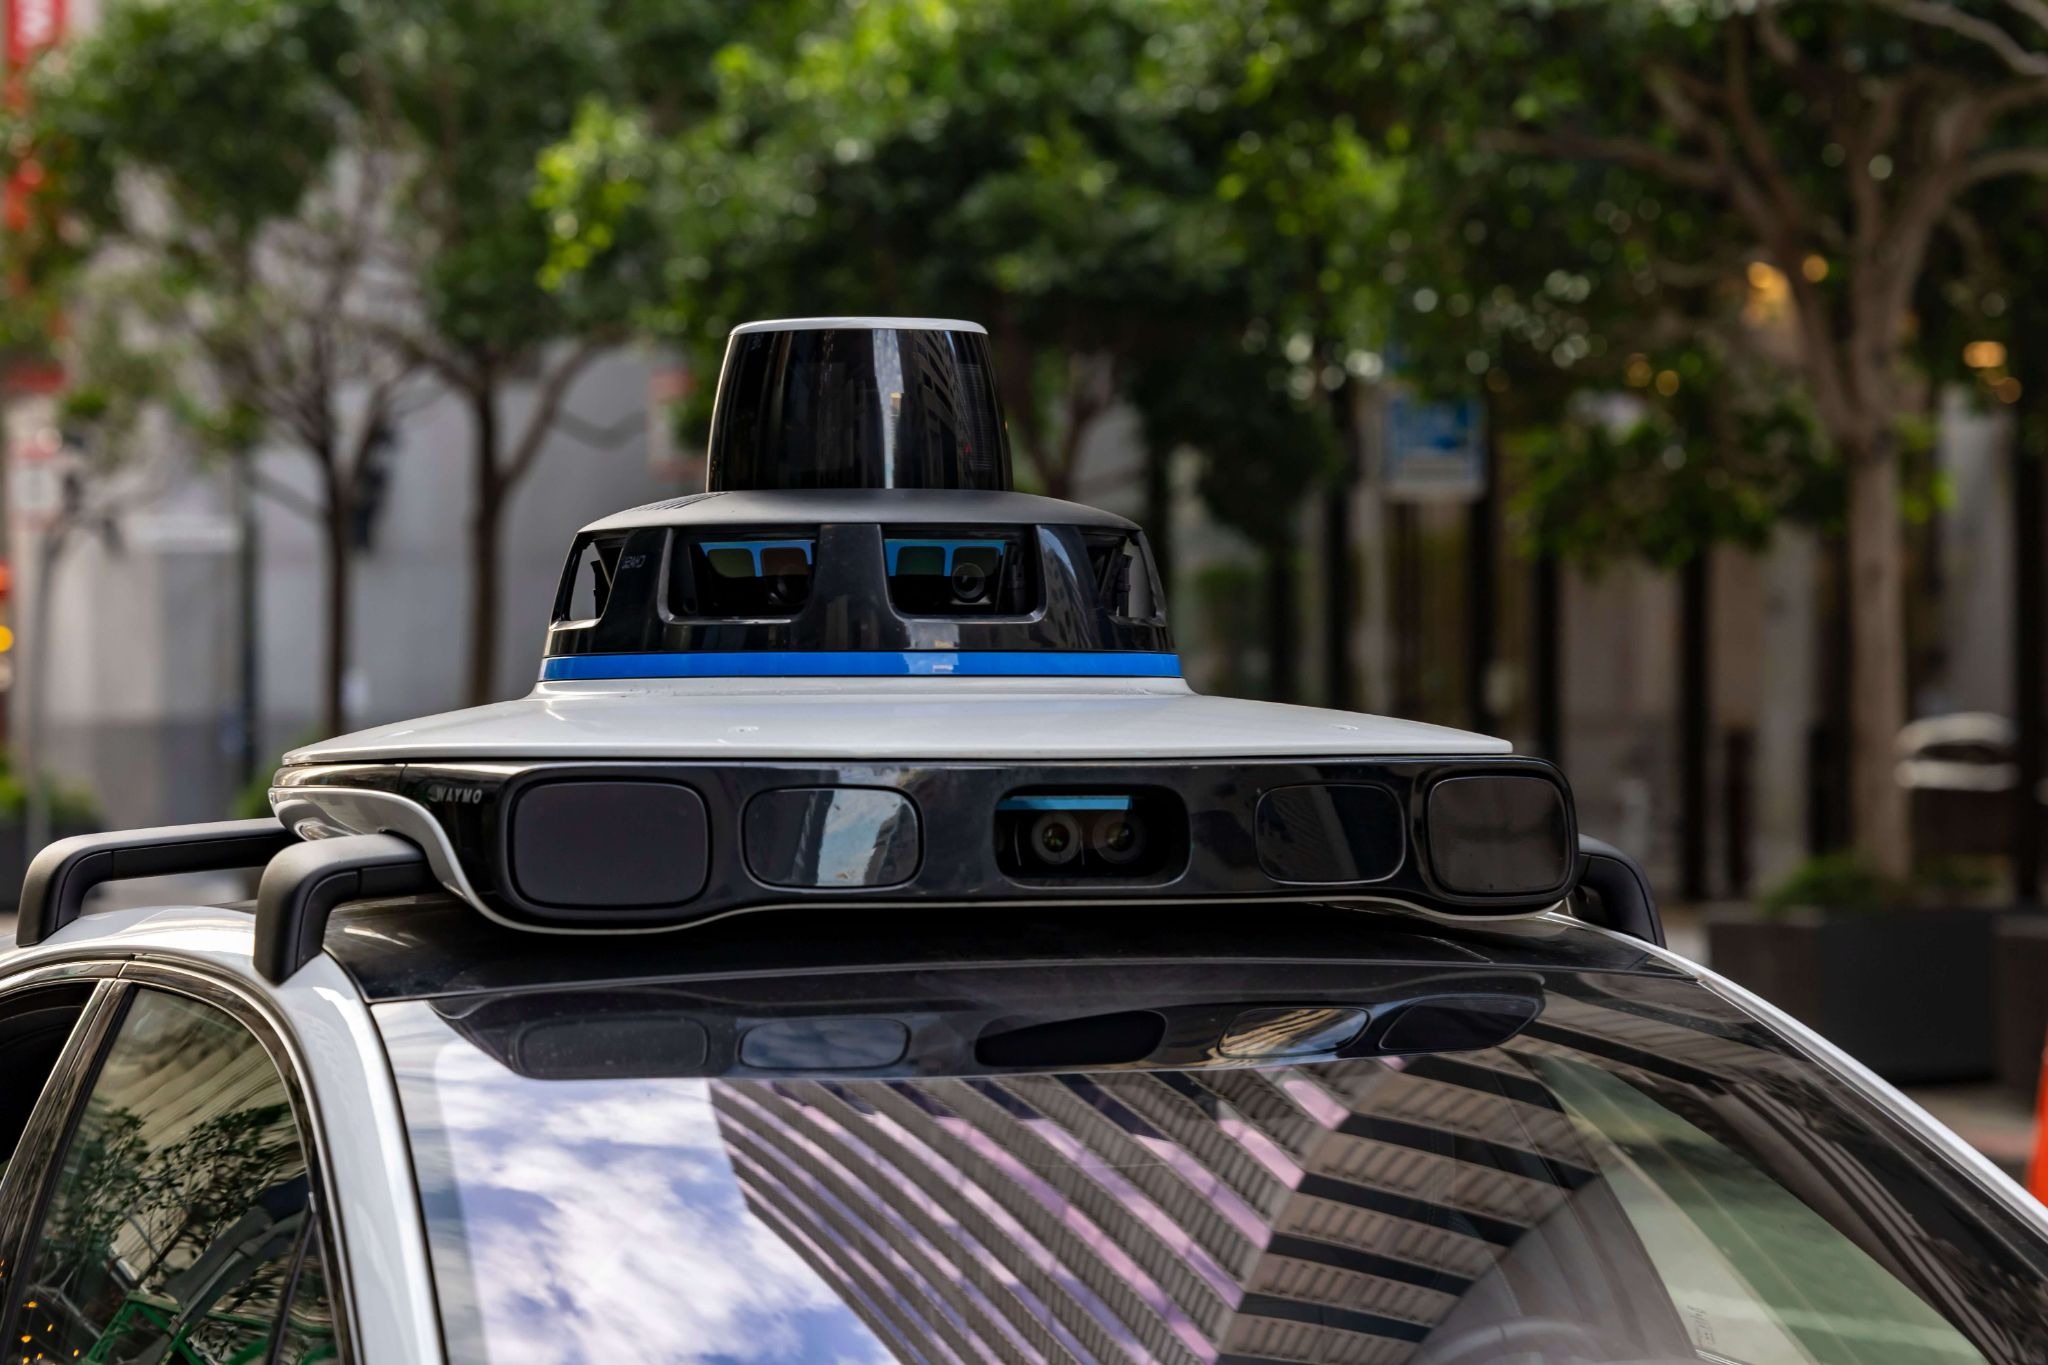
Taxi companies already do many of the things that would still be needed with an autonomous fleet. They maintain cars, deal with insurance and incidents, provide customer support and make sure enough vehicles are available. Some also already have their own depots, charging infrastructure or maintenance partners.
One possible model can already be seen in Zagreb. A local company owns and operates the autonomous fleet, while a larger ride-hailing platform brings customers. In the future, an existing taxi company could potentially have a similar role. Instead of managing cars and drivers, it could manage autonomous cars that receive bookings through a larger platform.
This does not mean platforms such as Uber will always rely on other companies to own the cars. Uber’s 2026 agreement with Rivian includes up to $1.25 billion in milestone-dependent investment and says that Uber or its fleet partners may purchase the autonomous vehicles. Uber is also developing infrastructure for autonomous fleets. Different ownership models are therefore possible.
Autonomous vehicles could also become interesting for rental and car-sharing companies, although this is probably further in the future. These businesses already manage vehicles, maintenance, cleaning, charging, bookings, customer accounts and payments, so much of the practical work is similar.
Autonomous driving could also change how rental and sharing cars are moved. Today, an employee may need to drive a car from one location to another. In the future, the vehicle could potentially do this itself within an area where autonomous driving is approved. It could even become possible for a rental car to drive itself to a customer’s pickup point.
Without drivers, it becomes especially important to understand how much time each vehicle is actually working. Every hour spent charging, being cleaned, waiting for maintenance or simply sitting unused means less time carrying paying passengers.
Some useful KPIs could be available hours per vehicle, paid trips per vehicle each day, revenue per available vehicle/day, empty kilometres, charging and maintenance downtime, cost per trip and incidents that need human help. These are most popular robotaxi industry KPIs of what a company could measure during a pilot.
For example, if cars spend too much time waiting to charge, the charging setup may need to change. A lot of empty kilometres could mean the cars are not in the right places, while too much maintenance downtime could make a vehicle more expensive to operate.
For either model, the business case depends on the partnership terms: who finances the vehicles, who carries the risk when demand is low, and how revenue and operating costs are shared. Operators should assess what remains after vehicle financing, insurance, charging, maintenance and partner fees. Depots, local service teams and reliable fleet availability could make an operator a valuable partner, but profitability still needs to be demonstrated.
One option for taxi fleets would be to work with an autonomous driving company and a larger ride-hailing platform. The local company could own or manage the cars and take care of the fleet, while customers book their rides through the larger platform.
Another option could be possible in cities where large ride-hailing platforms are not present or have limited coverage. A local company could work with an approved AV provider while using its own app, bookings, payments, customer support and fleet management.
In both cases, a company cannot simply buy autonomous cars and start offering rides. The technology needs to be approved, and local rules have to allow the service. These rules will also be different across Europe. Great Britain, for example, introduced its Automated Passenger Services permitting framework in 2026. Services similar to taxis or private hire vehicles need consent from the relevant local authority, while responsibility for the autonomous driving technology and the passenger service are treated separately.
A company does not need to have autonomous cars today to start preparing. A good first step is understanding the current fleet in detail – what each vehicle costs, how many hours it is available, how much time it spends charging or being repaired, and when cars are used the most.
Charging, cleaning, maintenance and depot processes are also worth looking at because all of these will still be needed with autonomous vehicles. A company interested in an AV pilot can then choose a location and use case, look at the local permit process and start talking to autonomous driving technology providers.
The software will also need some preparation. Customers still need to book and pay for rides, while the company needs fleet information, customer support, reporting and connections between its own systems and the AV technology. Starting with a small pilot makes it possible to test all of this before trying to build a larger service.
ATOM Mobility already provides many of the software functions used by taxi, ride-hailing, rental and sharing companies, including customer apps, bookings, payments, fleet management, maintenance tasks, analytics and APIs. Its ride-hailing software includes passenger and driver apps, dispatch, payments, fleet data, analytics and integrations. The ATOM Mobility API can also exchange data about vehicles, bookings, rides, payments, telemetry and maintenance tasks.
ATOM Mobility does not provide autonomous driving technology. This would come from a specialised AV company, and each project would have its own technical requirements and local approvals. For an AV pilot, ATOM Mobility could work with the fleet company and AV provider on the rider experience, integrations, fleet management and the data needed to measure how the pilot is working.
If you operate a taxi, rental or sharing fleet and want to explore an AV pilot, ATOM Mobility can help plan the booking and fleet-management setup, integrations and metrics you would need to test together with an AV technology partner.
Use test credentials to log in - Phone number: +1 123123123, Code: 777777


Driver App demo credentials - Email: test@atom.com, Password: driver