Blog
Insights and news from the ATOM Mobility team
We started our blog to share free valuable information about the mobility industry: inspirational stories, financial analysis, marketing ideas, practical tips, new feature announcements and more.
We started our blog to share free valuable information about the mobility industry: inspirational stories, financial analysis, marketing ideas, practical tips, new feature announcements and more.
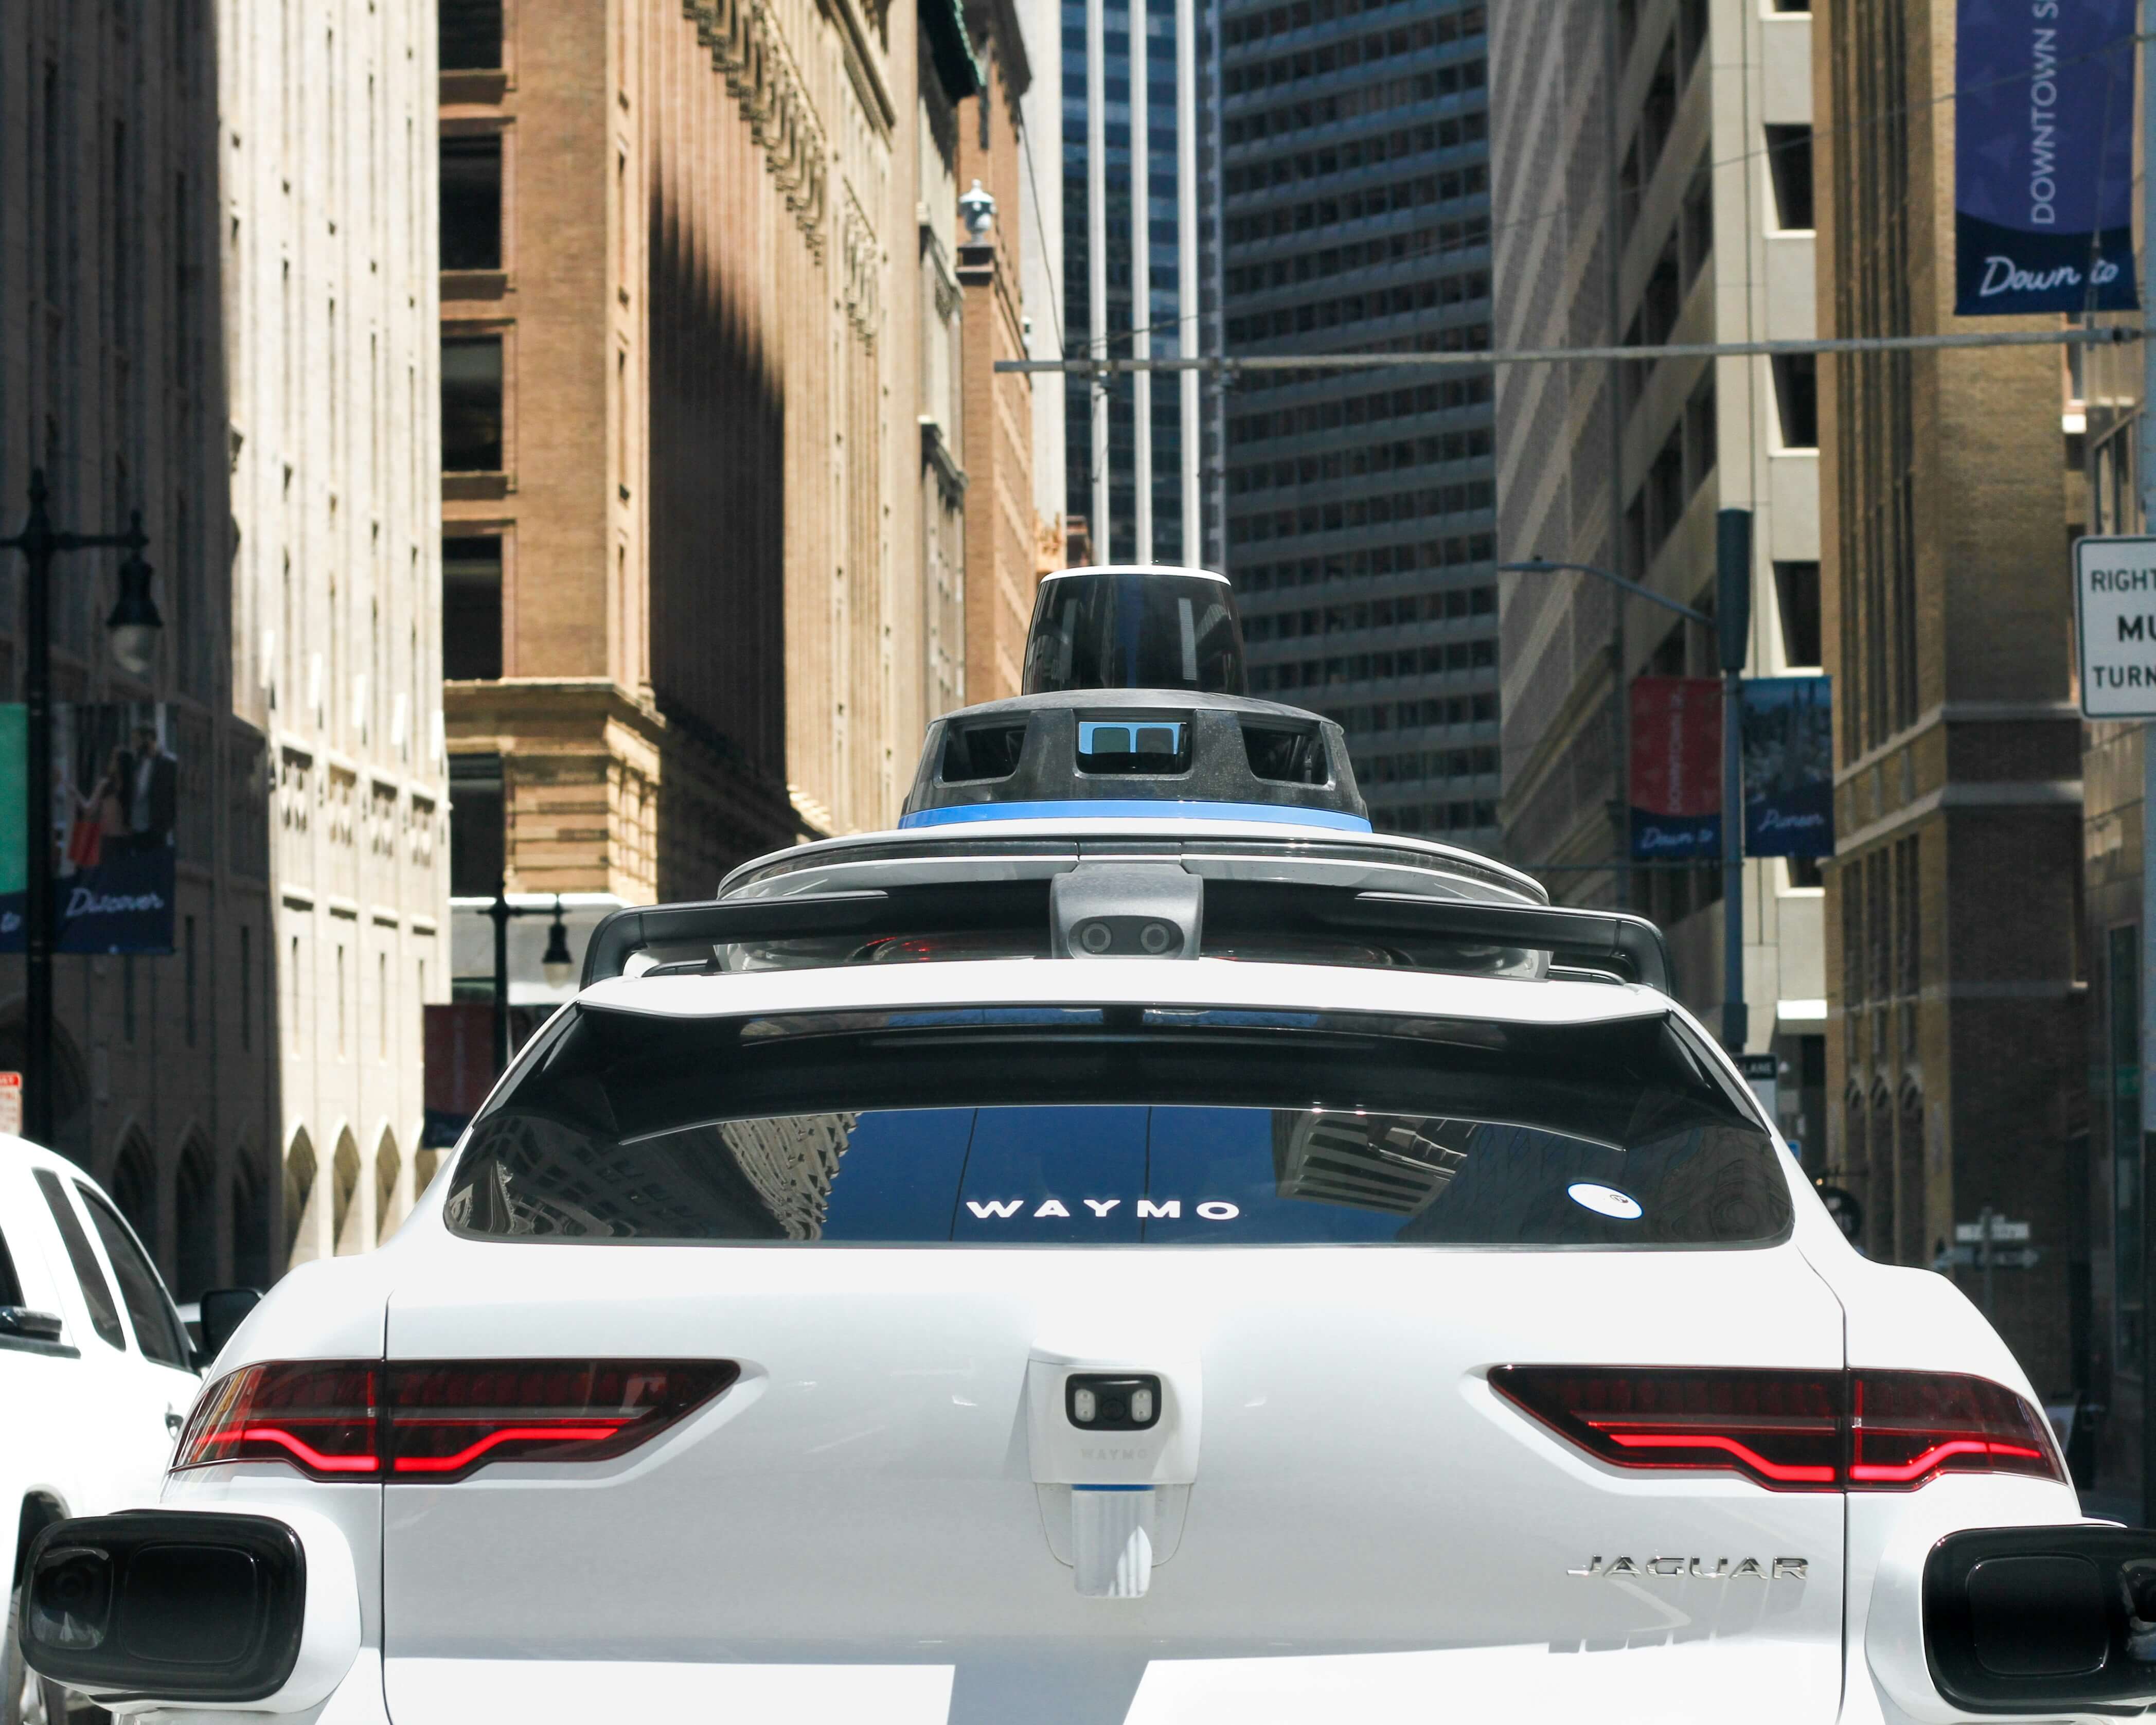
🤖 Who will actually operate Europe’s robotaxi fleets? Autonomous driving may remove the driver, but it doesn’t remove the work behind the car. Robotaxis still need charging, cleaning, maintenance, depots, customer support and someone managing the fleet every day. Early projects in Zagreb, Madrid and London illustrate different stages of deployment and how AV technology providers, fleet operators and booking platforms can work together. Taxi, rental and car-sharing companies already handle many of these tasks. What would it take to turn that experience into an autonomous fleet business?
For a taxi fleet owner, autonomous vehicles may seem to remove the most important part of the current business – the driver. But even without drivers, someone still needs to take care of the cars. They need to be owned or financed, charged, cleaned, inspected and repaired. Someone also needs to manage depots, deal with incidents, help customers and make sure enough cars are available.
The first robotaxi services and tests in Europe are already showing how this could work. The company that develops the autonomous driving technology does not always own or operate the cars. The app where customers book their rides may come from another company too. This could leave an important role for taxi, rental, car-sharing and other fleet companies that already know how to manage vehicles.
A taxi company today manages both cars and drivers. Drivers need to be recruited, scheduled, paid and supported. With a driverless fleet, these tasks would eventually disappear, but most of the work related to the cars would stay.
Autonomous cars still need charging or refuelling, cleaning, tyres, inspections, repairs and insurance. They also need somewhere to park when they are not working. If there is an accident or a technical problem, someone needs to deal with it and get the car back on the road. Customer support is still needed too when there are problems with bookings or payments, or when someone leaves something in the car.
Some of these tasks may even become more important. Robotaxis are expensive, and every hour a car spends charging, being cleaned or waiting for maintenance is an hour when it cannot take passengers. Moove, for example, already provides fleet ownership, depots, charging, maintenance and 24/7 operations for autonomous vehicles.
Drivers also do more than drive: they notice damage, report faults, help passengers and respond when something goes wrong. Without a driver, these responsibilities need clear processes and dedicated support. Existing fleet experience is an advantage, but operators will need to adapt it to vehicles running without someone behind the wheel.
There can be several companies behind one robotaxi ride. One provides autonomous driving technology, another may own the cars, and a local company can take care of the fleet. A platform such as Uber can then connect the cars with passengers. Sometimes one company may do several of these things, but this is not always the case.
Zagreb is one example. Pony.ai provides the autonomous driving system, Verne owns and operates the fleet, and Uber connects it with customers through its app. Autonomous rides became commercially available through Uber in August 2026 with a licensed operator onboard. On 10 September, Pony.ai and Verne also started fully driverless passenger test rides on a 22-kilometre route connecting parts of Zagreb with the airport. These are still limited test rides, not a fully driverless service across the whole city.
A similar model is being tested in Madrid. WeRide, Uber and AVOMO received permission in September 2026 to start testing and mapping under Spain’s ES-AV framework. The first 20 vehicles have an onboard specialist. WeRide provides the autonomous technology, Uber connects the cars with passengers, and AVOMO takes care of fleet operations. Commercial operations are planned for later in 2026, but the current permit is for testing and preparation rather than a general driverless taxi service.
In London, Wayve and Uber launched supervised autonomous passenger rides in September 2026. Customers can be matched with an autonomous vehicle through the Uber app, but there is still a licensed driver in the car.
The plans for the next few years are already much bigger. Pony.ai and Uber announced in August 2026 that they plan to deploy more than 2,000 robotaxis in Europe, starting with Zagreb and later expanding to four more European cities.
Bolt and Lucid announced another partnership in September, with Bolt aiming to deploy at least 25,000 autonomous Lucid vehicles across European cities. This is a future target, not 25,000 cars already operating today.
How these fleets are owned and operated may also be different from one city to another. Local regulations, available vehicles, charging and depot infrastructure and partnerships will all have an effect on how each service is set up.
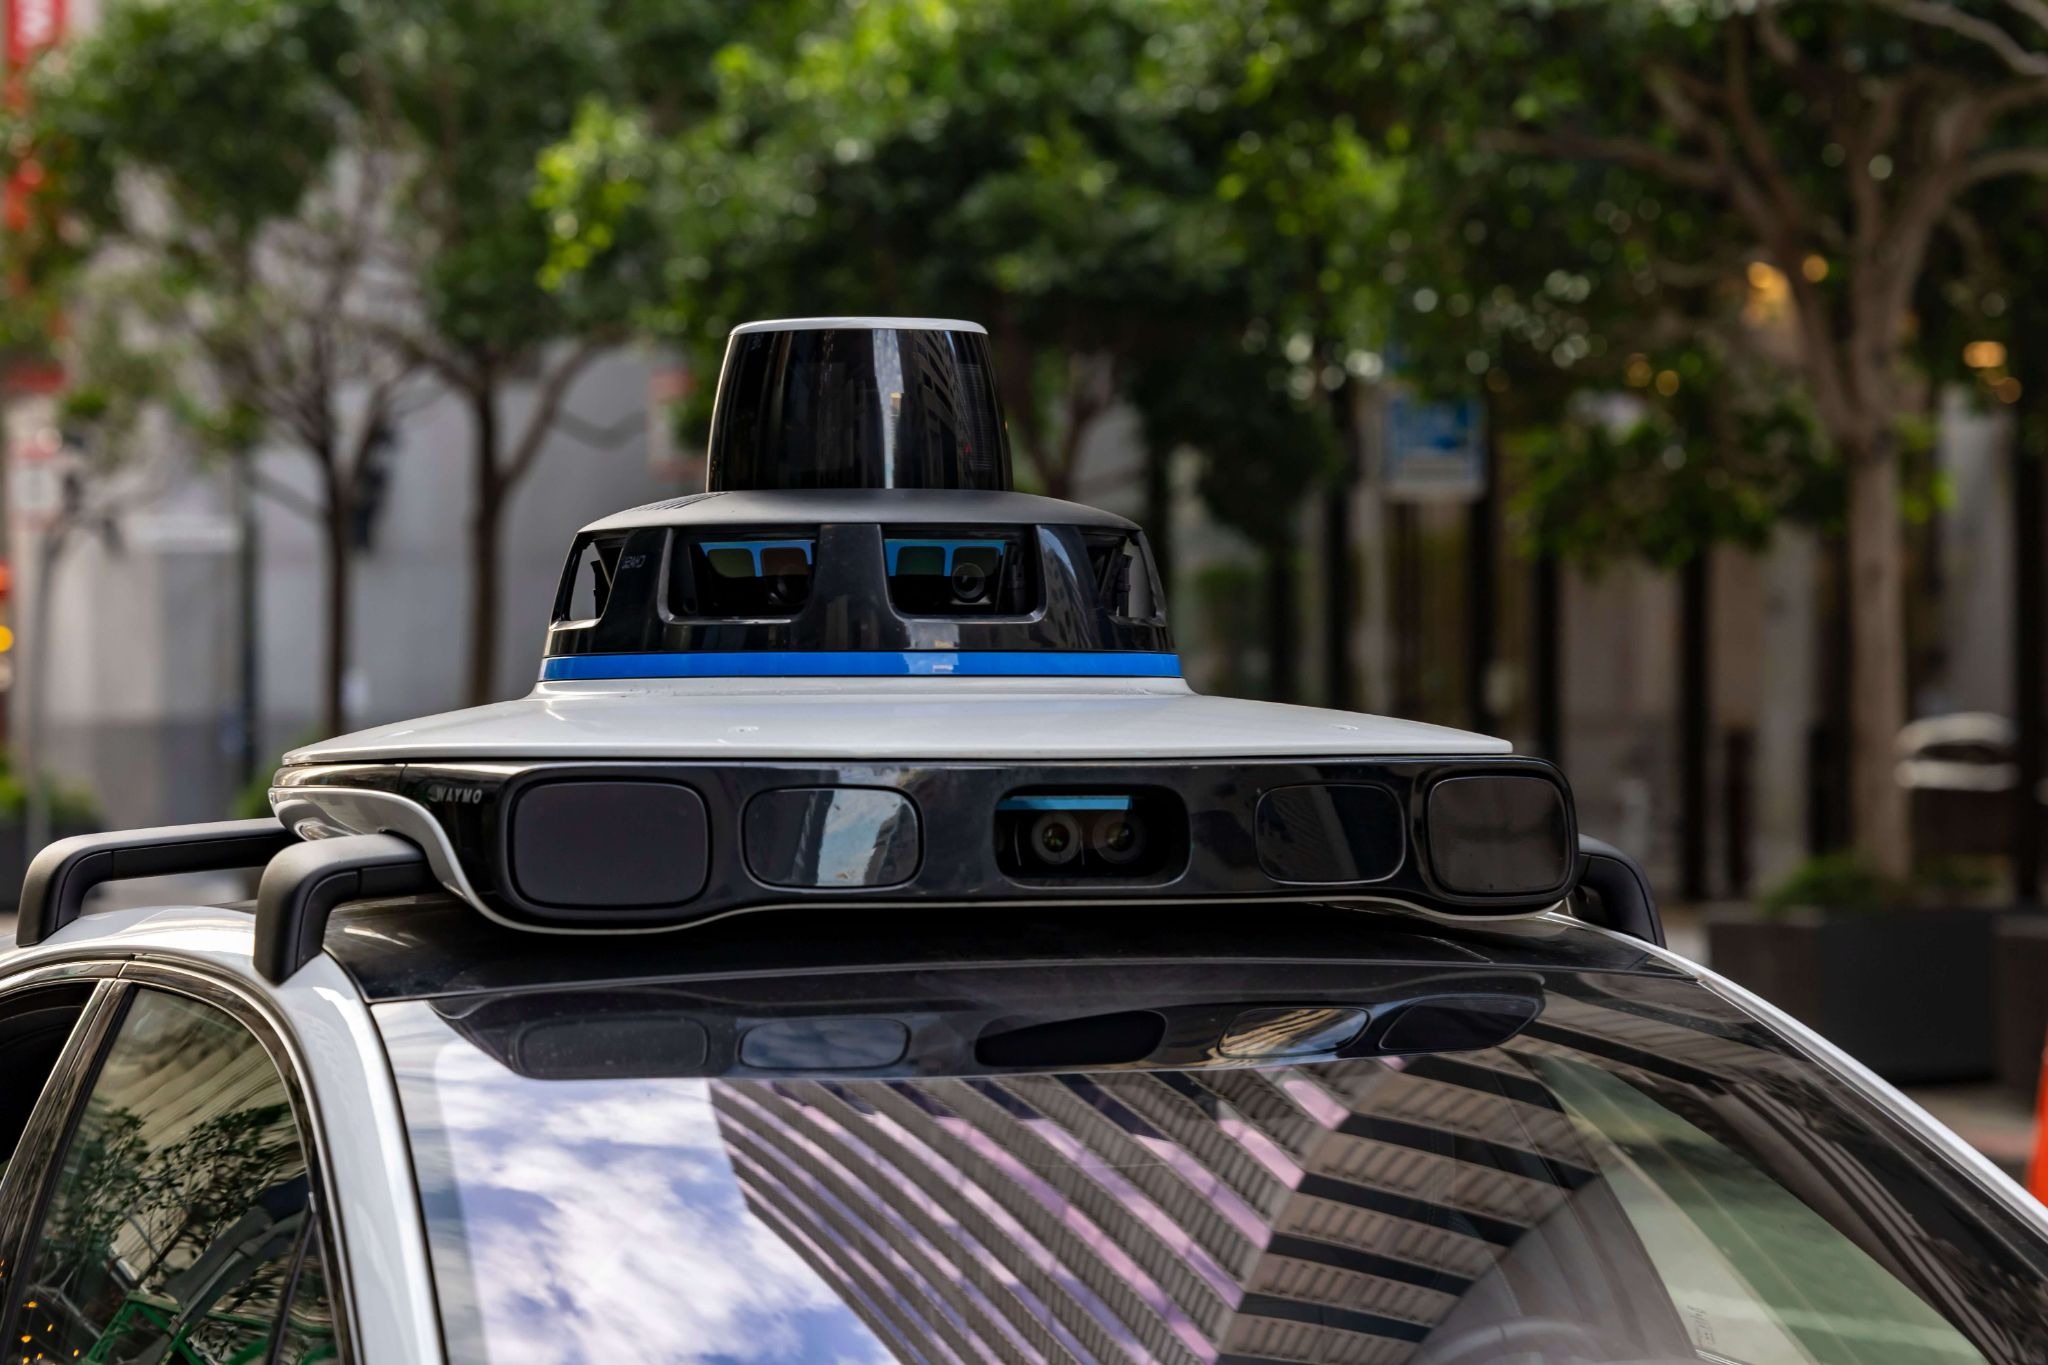
Taxi companies already do many of the things that would still be needed with an autonomous fleet. They maintain cars, deal with insurance and incidents, provide customer support and make sure enough vehicles are available. Some also already have their own depots, charging infrastructure or maintenance partners.
One possible model can already be seen in Zagreb. A local company owns and operates the autonomous fleet, while a larger ride-hailing platform brings customers. In the future, an existing taxi company could potentially have a similar role. Instead of managing cars and drivers, it could manage autonomous cars that receive bookings through a larger platform.
This does not mean platforms such as Uber will always rely on other companies to own the cars. Uber’s 2026 agreement with Rivian includes up to $1.25 billion in milestone-dependent investment and says that Uber or its fleet partners may purchase the autonomous vehicles. Uber is also developing infrastructure for autonomous fleets. Different ownership models are therefore possible.
Autonomous vehicles could also become interesting for rental and car-sharing companies, although this is probably further in the future. These businesses already manage vehicles, maintenance, cleaning, charging, bookings, customer accounts and payments, so much of the practical work is similar.
Autonomous driving could also change how rental and sharing cars are moved. Today, an employee may need to drive a car from one location to another. In the future, the vehicle could potentially do this itself within an area where autonomous driving is approved. It could even become possible for a rental car to drive itself to a customer’s pickup point.
Without drivers, it becomes especially important to understand how much time each vehicle is actually working. Every hour spent charging, being cleaned, waiting for maintenance or simply sitting unused means less time carrying paying passengers.
Some useful KPIs could be available hours per vehicle, paid trips per vehicle each day, revenue per available vehicle/day, empty kilometres, charging and maintenance downtime, cost per trip and incidents that need human help. These are most popular robotaxi industry KPIs of what a company could measure during a pilot.
For example, if cars spend too much time waiting to charge, the charging setup may need to change. A lot of empty kilometres could mean the cars are not in the right places, while too much maintenance downtime could make a vehicle more expensive to operate.
For either model, the business case depends on the partnership terms: who finances the vehicles, who carries the risk when demand is low, and how revenue and operating costs are shared. Operators should assess what remains after vehicle financing, insurance, charging, maintenance and partner fees. Depots, local service teams and reliable fleet availability could make an operator a valuable partner, but profitability still needs to be demonstrated.
One option for taxi fleets would be to work with an autonomous driving company and a larger ride-hailing platform. The local company could own or manage the cars and take care of the fleet, while customers book their rides through the larger platform.
Another option could be possible in cities where large ride-hailing platforms are not present or have limited coverage. A local company could work with an approved AV provider while using its own app, bookings, payments, customer support and fleet management.
In both cases, a company cannot simply buy autonomous cars and start offering rides. The technology needs to be approved, and local rules have to allow the service. These rules will also be different across Europe. Great Britain, for example, introduced its Automated Passenger Services permitting framework in 2026. Services similar to taxis or private hire vehicles need consent from the relevant local authority, while responsibility for the autonomous driving technology and the passenger service are treated separately.
A company does not need to have autonomous cars today to start preparing. A good first step is understanding the current fleet in detail – what each vehicle costs, how many hours it is available, how much time it spends charging or being repaired, and when cars are used the most.
Charging, cleaning, maintenance and depot processes are also worth looking at because all of these will still be needed with autonomous vehicles. A company interested in an AV pilot can then choose a location and use case, look at the local permit process and start talking to autonomous driving technology providers.
The software will also need some preparation. Customers still need to book and pay for rides, while the company needs fleet information, customer support, reporting and connections between its own systems and the AV technology. Starting with a small pilot makes it possible to test all of this before trying to build a larger service.
ATOM Mobility already provides many of the software functions used by taxi, ride-hailing, rental and sharing companies, including customer apps, bookings, payments, fleet management, maintenance tasks, analytics and APIs. Its ride-hailing software includes passenger and driver apps, dispatch, payments, fleet data, analytics and integrations. The ATOM Mobility API can also exchange data about vehicles, bookings, rides, payments, telemetry and maintenance tasks.
ATOM Mobility does not provide autonomous driving technology. This would come from a specialised AV company, and each project would have its own technical requirements and local approvals. For an AV pilot, ATOM Mobility could work with the fleet company and AV provider on the rider experience, integrations, fleet management and the data needed to measure how the pilot is working.
If you operate a taxi, rental or sharing fleet and want to explore an AV pilot, ATOM Mobility can help plan the booking and fleet-management setup, integrations and metrics you would need to test together with an AV technology partner.
📲 Choosing mobility software is a decision that can shape your business. 🔍 This review takes a deeper look at ATOM Mobility, covering how the platform works, 💰 its pricing model, 🔌 hardware flexibility, 🤝 customer support, and 🚀 the types of operators it's built for.
Choosing mobility software is a long-term decision. Once a platform is integrated into daily operations, replacing it can take months and require significant time and resources. That's why it's worth looking beyond feature lists and understanding how a platform performs in practice.
ATOM Mobility has become the leading white-label mobility platform for operators launching and scaling vehicle-sharing, car rental, and ride-hailing businesses. This review covers how the platform works, how its pricing is structured, what customers say about it, and the types of businesses it's best suited for.
ATOM Mobility is a white-label SaaS platform built specifically for mobility businesses.
Instead of developing software in-house, operators can launch their own branded mobility service using an established platform that already includes the infrastructure needed to run daily operations.
The platform brings together three products:
All three run on the same technology, allowing operators to manage multiple mobility services without maintaining separate software platforms.
ATOM Mobility uses a transparent pricing model based on a one-time implementation fee followed by a subscription that scales with the business. The exact cost depends on the products, integrations, and level of customization required, but customers know what is included from the start, without unexpected licensing costs or hidden platform fees.
Compared to building proprietary software or purchasing enterprise mobility platforms, ATOM Mobility can be up to five times more affordable, depending on the project and deployment requirements.
The rider app is an important part but not the only service on the platform. Customers use the mobile app to register, verify their identity, locate nearby vehicles, unlock them, make payments, purchase subscriptions, and manage bookings.
Operators manage the business through a web dashboard that provides access to fleet monitoring, pricing, reservations, customer management, payments, analytics, maintenance workflows, reporting, promotions, and day-to-day operations.
For fleet management, ATOM Mobility also offers a dedicated Operator app, designed to help teams manage vehicles, tasks, damages, and routes while on the go.
Companies offering ride-hailing services also receive a dedicated driver app, allowing drivers to accept rides, navigate trips, and track their earnings within the same ecosystem.
Altogether, the platform includes more than 300 features and 100+ integrations designed specifically for mobility operators, allowing businesses to launch 8-15 times faster than building comparable software from scratch.
One of ATOM Mobility's biggest advantages is its hardware flexibility. The platform works with numerous IoT providers and vehicle manufacturers, meaning operators are not locked into a single hardware supplier.
For example, if a business decides to replace its smart locks or expand its fleet with vehicles from another manufacturer, it doesn't need to replace the software platform as well. This gives operators more flexibility as their business evolves and reduces the risk of becoming dependent on a single hardware vendor. To name just a few, ATOM Mobility already supports integrations with Segway, Teltonika, Acton, Omni, Okai, Fitrider, Freego, Zimo, Marti, Comodule, Hongji, Yadea, NIU, NEXT, Geotab, Acacus, INVERS, Velco, Navee, Vaimoo, Dynasys, 2hire, Sentinel, Linka, and many others.
Launching a mobility business often requires close collaboration between the operator and the software provider, particularly during implementation and expansion.
ATOM Mobility provides support through email, WhatsApp, and scheduled calls with a dedicated team that has worked together for several years. Rather than speaking with a different representative every time, customers build relationships with specialists who become familiar with their business and operational goals. For urgent or business-critical matters, customers can also communicate directly with company leadership, including the CEO when needed.
ATOM Mobility has received consistently positive reviews on Capterra, where customers frequently highlight both the quality of the platform and the team behind it.
Some of the reviews describe ATOM Mobility as:
"ATOM is an exceptional app developer."
"Clear communication and good service."
"Atom has been a reliable partner to us for 3 seasons now."
"Great Partnership with the ATOM Team."
"Reliable Partner with Great Support and Continuous Improvements."
Across the reviews, the same themes appear repeatedly: responsive communication, long-term partnerships, and continuous product development.
ATOM Mobility is designed for companies that want to launch, operate, or scale a mobility business without spending years developing proprietary software. The platform is ideal for entrepreneurs launching their first mobility service, SMEs entering the shared mobility market, established operators expanding into new cities or mobility verticals, and fleet operators managing anywhere from a single vehicle to more than 10,000 vehicles who need a modern, feature-rich platform at a reasonable cost.
Because the platform is white-label, operators keep full control over their branding, pricing strategy, and customer experience while relying on technology that has already been proven across more than 80 different markets.
ATOM Mobility is built specifically for vehicle sharing, car rental, and ride-hailing businesses. Companies such as Uber, Bolt, Lime, and Voi have invested hundreds of millions of dollars and many years into developing proprietary software, creating platforms that are deeply integrated into their operations. While replacing such systems could potentially deliver commercial benefits, the migration effort, operational risk, and loss of flexibility that comes with owning and customizing their own technology make a complete platform switch unlikely. As a result, these companies typically continue investing in their in-house platforms rather than adopting third-party software.
Similarly, companies looking to build software outside the mobility sector or develop entirely different types of platforms may find that ATOM Mobility's feature set is too focused on its core products.
Like any software platform, ATOM Mobility has strengths as well as situations where another approach may be a better fit.
Pros
Potential limitations
For startups, SMEs, and growing mobility operators, ATOM Mobility offers a practical alternative to building software in-house. The platform combines three mobility products in a single ecosystem, supports a wide range of hardware providers, and includes the operational tools needed to launch and scale a business. Beyond the technology itself, customers gain access to ATOM Academy - industry expertise, best practices, and educational resources, helping them avoid common mistakes and build a successful mobility business faster.
It isn't intended to replace proprietary platforms developed by companies such as Uber or Bolt, nor is it designed for businesses outside the mobility sector. For operators looking for an established white-label platform backed by long-term customer support and continuous product development, ATOM Mobility is a solution worth considering.
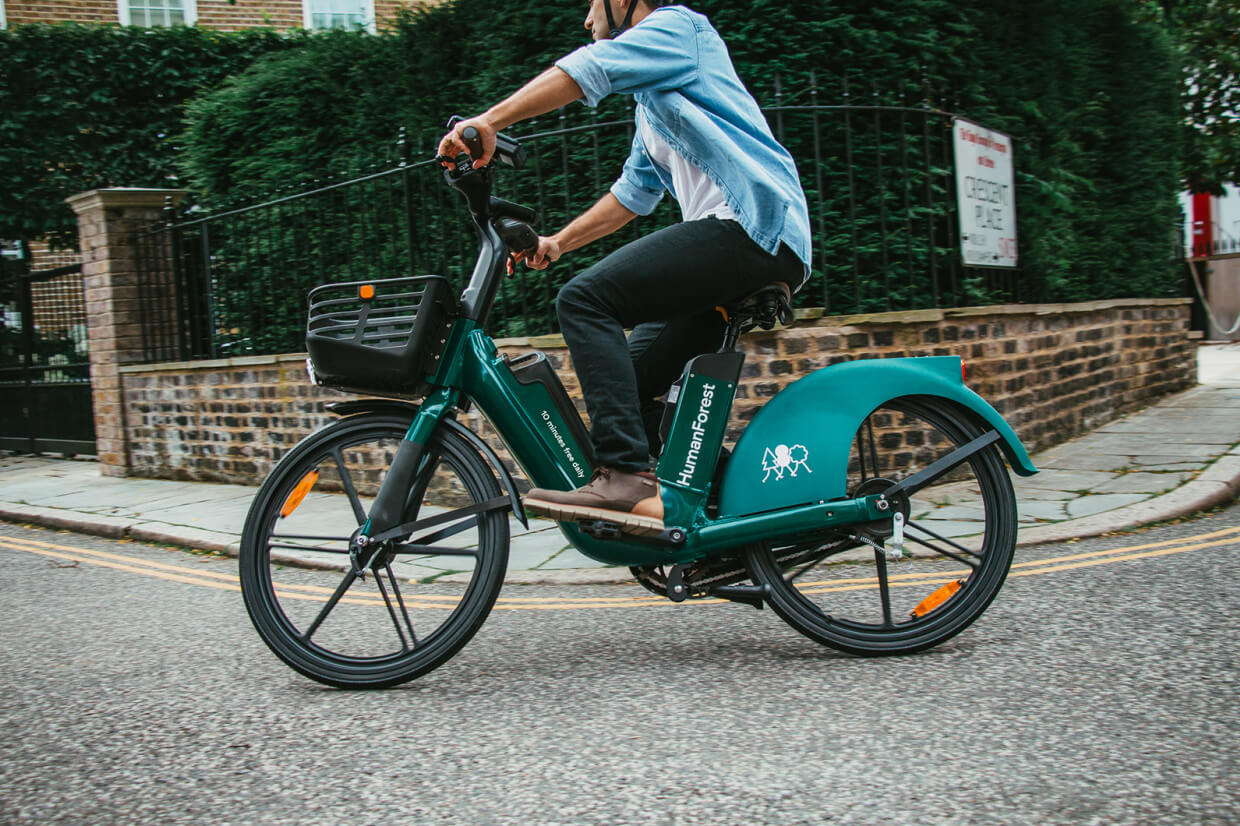
🚲 🛴 E-scooters or e-bikes? Docked or dockless? Every vehicle choice shapes the success of your micromobility business. In this new article, we break down the key micromobility fleet vehicles – their features, best use cases, and how to match them to your city profile. Plus, how ATOM Mobility helps operators manage both scooter and bike fleets in one platform.
Operators entering the micromobility space today face one major early decision: which vehicles to deploy. Your fleet type affects user experience, operational costs, maintenance needs, and regulatory compliance. Whether you plan to launch e‑scooters, e‑bikes, mopeds, or a mixed fleet, each vehicle category serves a different purpose.
This guide covers the main micromobility fleet vehicles – bike, e‑bike, kick scooter, e‑scooter, moped, and e‑moped – along with their features, common manufacturers, docking options, and ideal use cases.
Understanding the vehicle types
Bike (mechanical bicycle) A standard pedal bicycle with no motor. In shared fleets, mechanical bikes are simple, durable, and cost‑efficient. They require minimal electronics and are ideal for cities with strong cycling infrastructure. They generate lower maintenance costs but depend entirely on rider effort. Normally, user demand for this type of bike is also lower, thus operators can expect lower RPV rate (rides per vehicle per day).
E‑bike (electric bicycle) An electric bike combines pedal power with an electric motor that assists the rider. E‑bikes allow longer trips, easier hill climbing, and broader user appeal. Typical shared e‑bike trips range between 5–10 km. They cost more upfront but often generate higher revenue per ride. Many fleet operators source models from manufacturers such as Segway‑Ninebot, Okai, and Yadea. You can explore available e‑bike hardware options on the ATOM Mobility vehicles page: https://www.atommobility.com/vehicles.
Kick scooter (non‑electric scooter) A kick scooter is manually powered by pushing off the ground. While less common in commercial shared fleets today, they are still used in some controlled campus or tourism environments where low speed and low complexity are priorities.
E‑scooter (electric scooter) E‑scooters are lightweight, battery‑powered vehicles designed for short urban trips, typically under 4 km. They are highly flexible and well suited for dense city centers and first‑mile/last‑mile transport. Modern fleet models include swappable batteries, improved braking systems, suspension upgrades, and integrated IoT modules. Popular manufacturers include Segway‑Ninebot, Okai, and Navee that can also be found at ATOM Mobility.
Moped (fuel‑powered light motorcycle) A moped is a small motorized vehicle traditionally powered by gasoline, offering higher speeds and longer range than bikes or scooters. In shared mobility, fuel mopeds are becoming less common due to emissions regulations but still operate in some regions.
E‑moped (electric moped) An e‑moped is an electric version of a traditional moped. It provides longer range and higher speed than e‑scooters, often up to 45 km/h depending on local regulations. E‑mopeds are ideal for suburban areas or cities with longer commuting distances. Manufacturers such as NIU, Silence, Super Soco, and Yadea dominate this segment.
The table below provides a general comparison of the most common shared mobility vehicle types, including typical purchase prices, expected service life in commercial fleets, and average utilization (rides per vehicle per day). Actual figures vary depending on manufacturer, market, operating conditions, and fleet maintenance.
Approx. new purchase price – The typical cost of purchasing a new commercial-grade vehicle for a shared mobility fleet. Prices vary depending on the manufacturer, hardware specifications, battery capacity, IoT integration, and fleet order size.
Approx. used purchase price – The typical market price of a pre-owned commercial vehicle suitable for shared mobility operations. Factors such as vehicle age, mileage, battery health (for electric vehicles), overall condition, and refurbishment status significantly influence the price.
Typical fleet lifespan – The average period a vehicle remains economically viable in a shared mobility fleet before being retired or replaced. Lifespan depends on ride frequency, maintenance quality, weather conditions, road infrastructure, vandalism, accidents, and how intensively the fleet is operated.
Average rides/day/vehicle (RPV) – Rides Per Vehicle per Day (RPV) is one of the most important performance metrics for shared mobility operators. It measures the average number of completed trips each vehicle performs daily. Higher RPV generally leads to better fleet utilization, faster return on investment, and improved profitability. Actual RPV varies depending on vehicle type, city size, demand, seasonality, pricing strategy, fleet availability, and operational efficiency.
Docked vs dockless infrastructure
Beyond vehicle choice, parking strategy matters. Dockless fleets offer flexibility but may create parking compliance challenges. Docked systems use physical stations that improve order, security, and charging efficiency.
Several manufacturers specialize in docking and locking infrastructure, including KNOT CITY (which recently is out of market), and Kuhmute. These docking systems can improve vehicle organization, reduce vandalism, and simplify charging logistics for e‑bikes and e‑mopeds.
E‑scooters: Best for dense urban zones
E‑scooters work best in compact city centers, student districts, and areas with high short‑trip demand. They require less parking space and are faster to deploy. However, they demand consistent maintenance and battery management.
E‑bikes: Broader demographic appeal
E‑bikes provide greater comfort and stability, making them suitable for older users, tourists, and riders carrying bags. They perform well in cities with established cycling lanes or moderate hills. Although more expensive than scooters, they often achieve longer ride durations and stronger customer loyalty.
E‑mopeds: Extended range and higher revenue potential
E‑mopeds are suitable for cities with wider geography or suburban commuting patterns. They typically deliver higher revenue per trip but require licensing compliance and more robust fleet management.
Matching vehicles to city profiles
Tourist cities often benefit from e‑bikes due to comfort and sightseeing suitability. College towns frequently lean toward e‑scooters because of affordability and convenience. Larger or hilly cities may support mixed fleets. Suburban zones often justify e‑mopeds for longer travel distances.
Climate also influences hardware decisions. Wet or cold regions require sealed wiring, water‑resistant components, and tires suitable for slippery conditions.
Planning your hardware strategy
Choosing the right fleet is not only about vehicle type. It involves sourcing reliable manufacturers, evaluating docking options, understanding regulatory requirements, and planning maintenance cycles. Reviewing available hardware categories through ATOM Mobility’s vehicles directory can help operators compare models and integrations before committing to a large fleet purchase.
The most successful operators treat fleet composition as flexible. They start with one category and expand based on usage data, seasonality, and rider behavior. A balanced hardware strategy allows adaptation without replacing the entire fleet.
ATOM Mobility supports mixed fleets – including e‑scooters, e‑bikes, and e‑mopeds – within one platform, covering booking, payments, hardware integrations, and analytics. This allows operators to scale gradually while maintaining operational control.
Vehicle choice is not static. As cities evolve and regulations tighten, operators who understand their hardware options and adapt quickly are better positioned for long‑term growth.
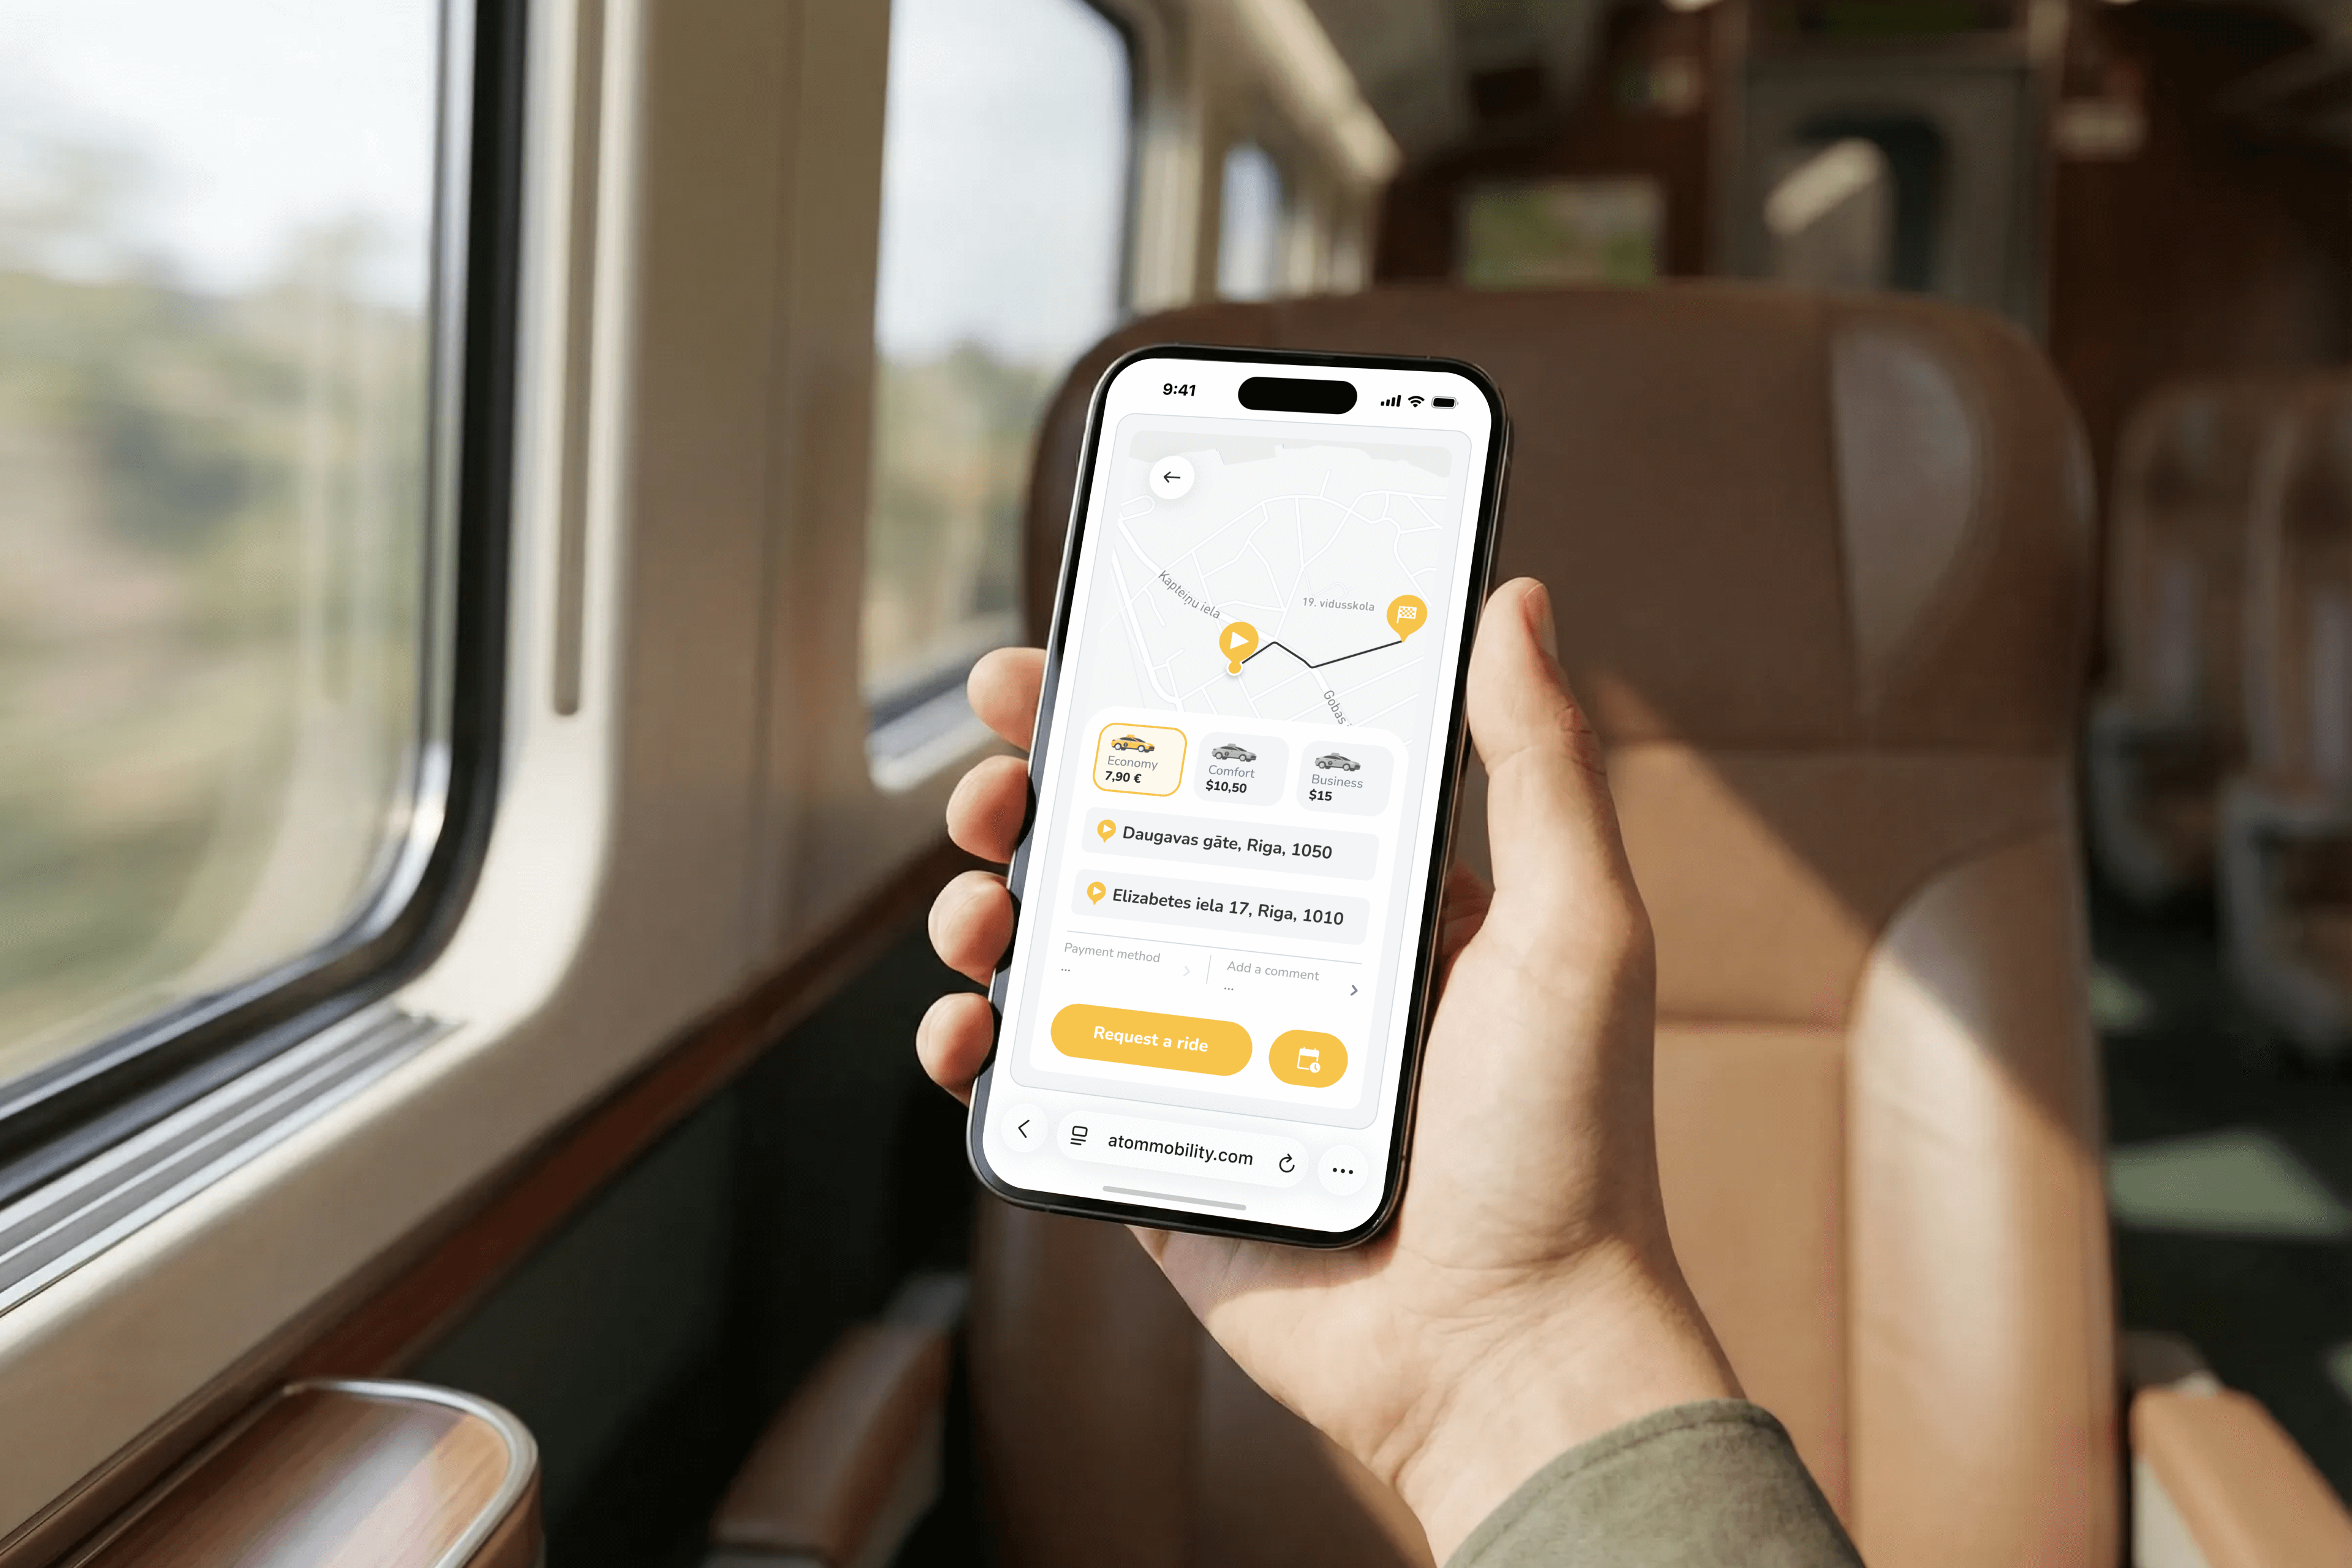
🚕 Getting drivers on the road is not the only thing you need to launch your taxi business. Many new platforms struggle with the same problem – drivers with no demand and riders with no available drivers. Building both at the same time is where most launches fail. This article introduces the key steps to launch a taxi business and avoid the most common mistakes.
Launching a taxi business today takes more than having drivers. It requires a system that can attract riders, onboard drivers, manage bookings, process payments, and keep daily operations running smoothly as demand grows.
The ride-hailing market is growing fast, while customer acquisition is getting more expensive and more competitive. Technavio estimates the global ride-hailing market will grow by more than $102 billion between 2024 and 2029, which creates room for new operators, but also raises the cost of visibility, paid acquisition, and brand differentiation in crowded markets, according to this ride-hailing services market forecast.
Many operators now launch faster by using ready-made tools instead of building every part from scratch. ATOM Mobility has already helped operators launch mobility businesses in as little as 90 days through a phased rollout covering market validation, legal setup, branding, driver onboarding, and launch execution.
But how to actually launch your business, if you’re not willing to do everything from scratch?
Most taxi businesses do not fail because the app is missing a feature but because there is no clear reason for customers to switch. Before choosing software or recruiting drivers, define where your opportunity is. That could mean:
This matters more than most expect. Your pricing, branding, driver experience, and customer acquisition all depend on the niche you choose. That is why defining a clear angle early matters, especially in crowded markets.
A taxi business is still a regulated business. Before launch, you need to set up the basics properly:
Skipping this part slows everything down later.
This is also the stage where many founders underestimate operating costs. Beyond software, you will need to plan for driver incentives, support, payment processing, and customer acquisition. That is one reason many operators now launch with white-label software instead of funding a custom build from day one.
Building a taxi app from scratch is expensive (in many cases we see it costs more than 30 000 -50 000 EUR), slow (takes many monhts), and usually unnecessary. To launch a working taxi business, you need:
Most early-stage operators do not need to build these systems themselves but a working infrastructure they can brand and launch quickly. That is why many operators start with ATOM Mobility, where the full system already includes rider and driver apps, dispatch tools, payments, analytics, integrations and backend operations in one platform. This is the same logic behind building a branded taxi service with white-label software instead of spending months on custom development.
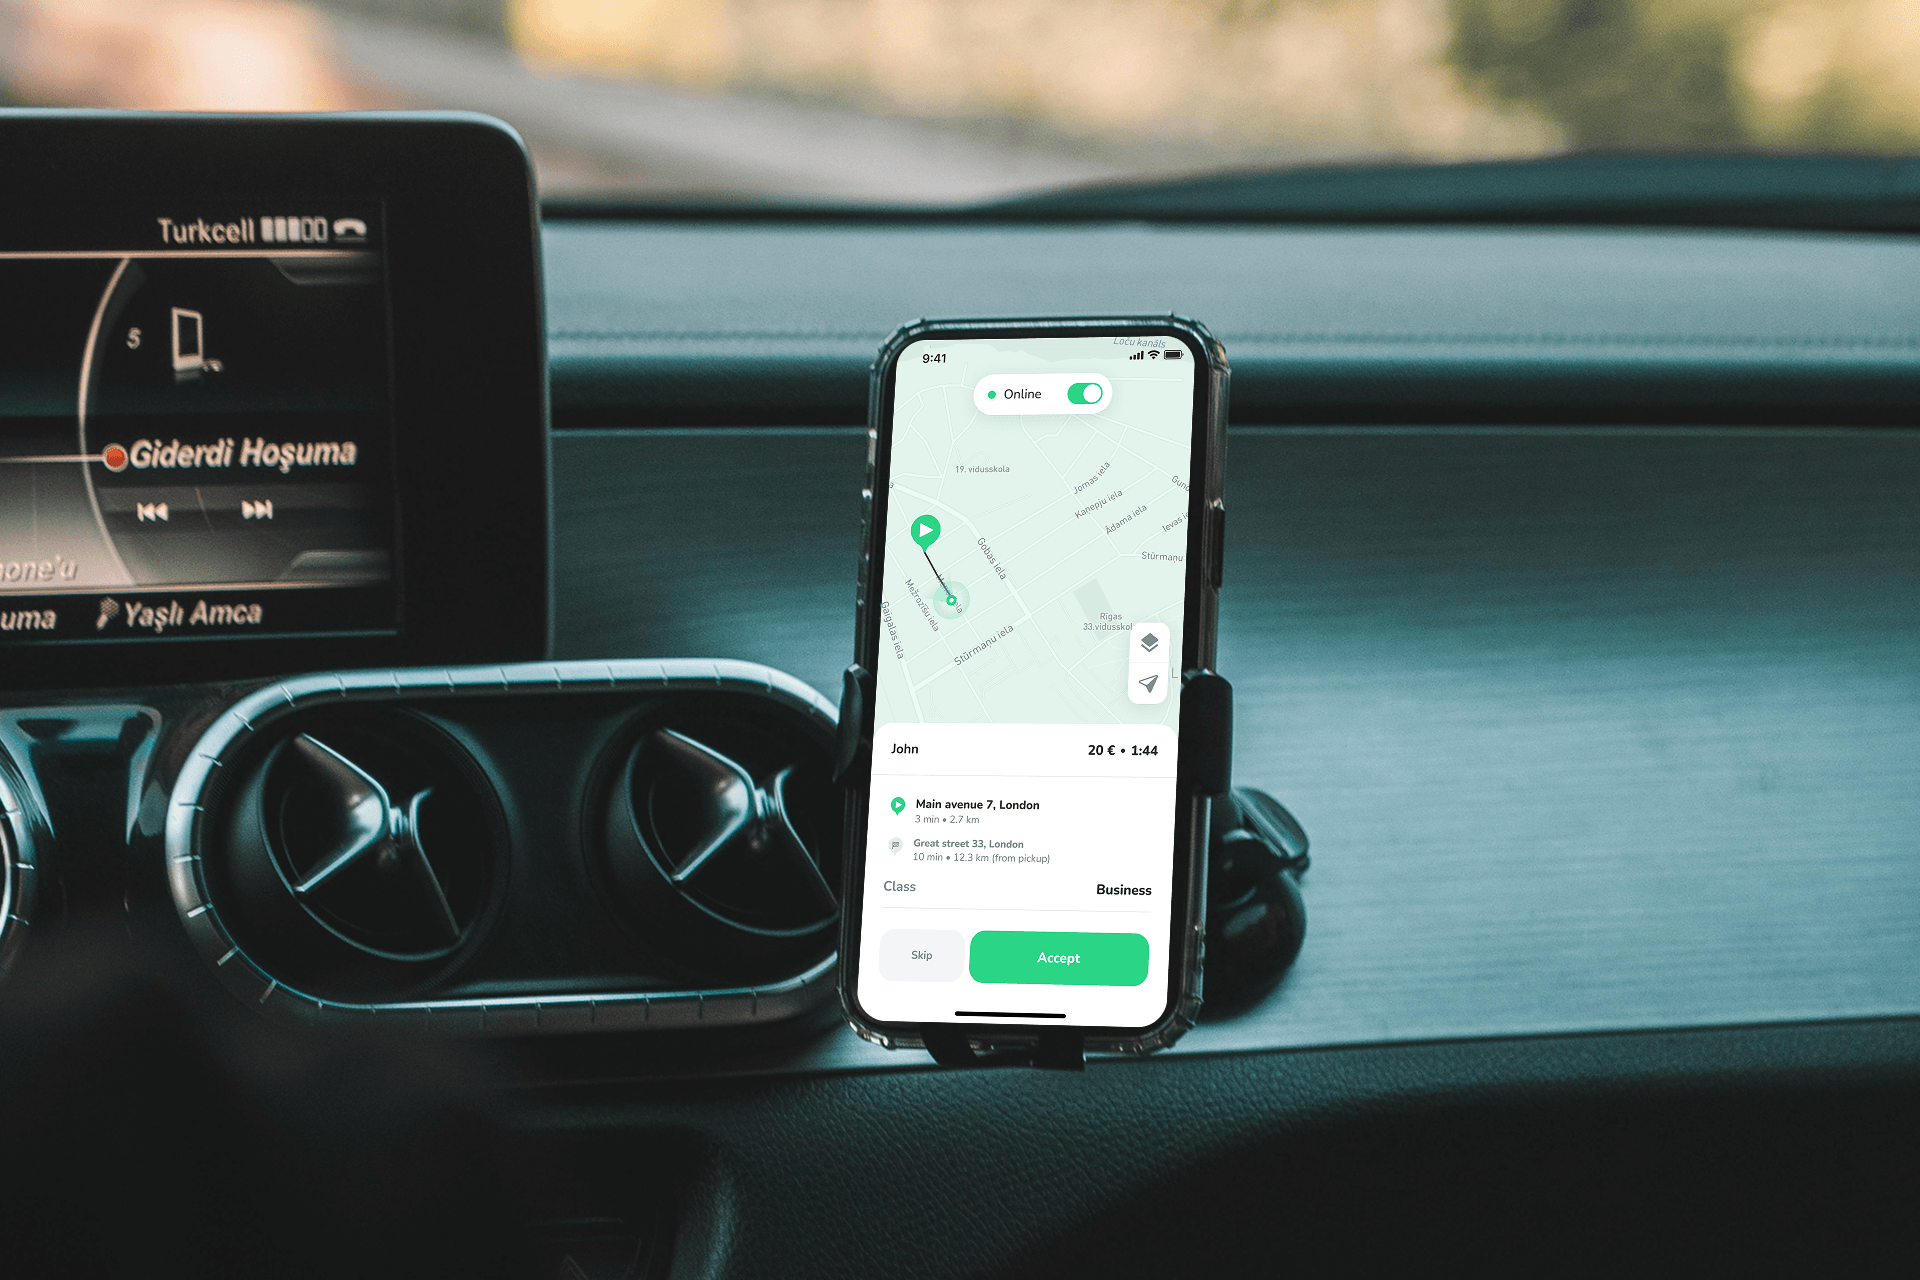
Driver onboarding needs to be fast and easy enough that drivers can register, upload documents, get approved, and start working without delays. But if onboarding takes too long, drivers drop off before they complete their first ride.
A strong launch setup should include:
This is also where the ATOM Mobility driver app becomes important, since it gives drivers one place to accept rides, navigate, manage earnings, and stay active without switching between tools.
Many taxi businesses still focus only on app installs but that is a mistake. Not every rider wants to download an app before booking a ride. This is especially true for airport pickups and tourists in general, hotel guests, older riders, and occasional users. That is why booking flexibility is important. Alongside mobile apps, many operators now add browser-based booking so riders can order without installing anything.
This is what ATOM introduced with its Web Booker for ride-hail, which gives operators a simple way to capture web traffic, direct bookings, and one-time users without forcing an app download.
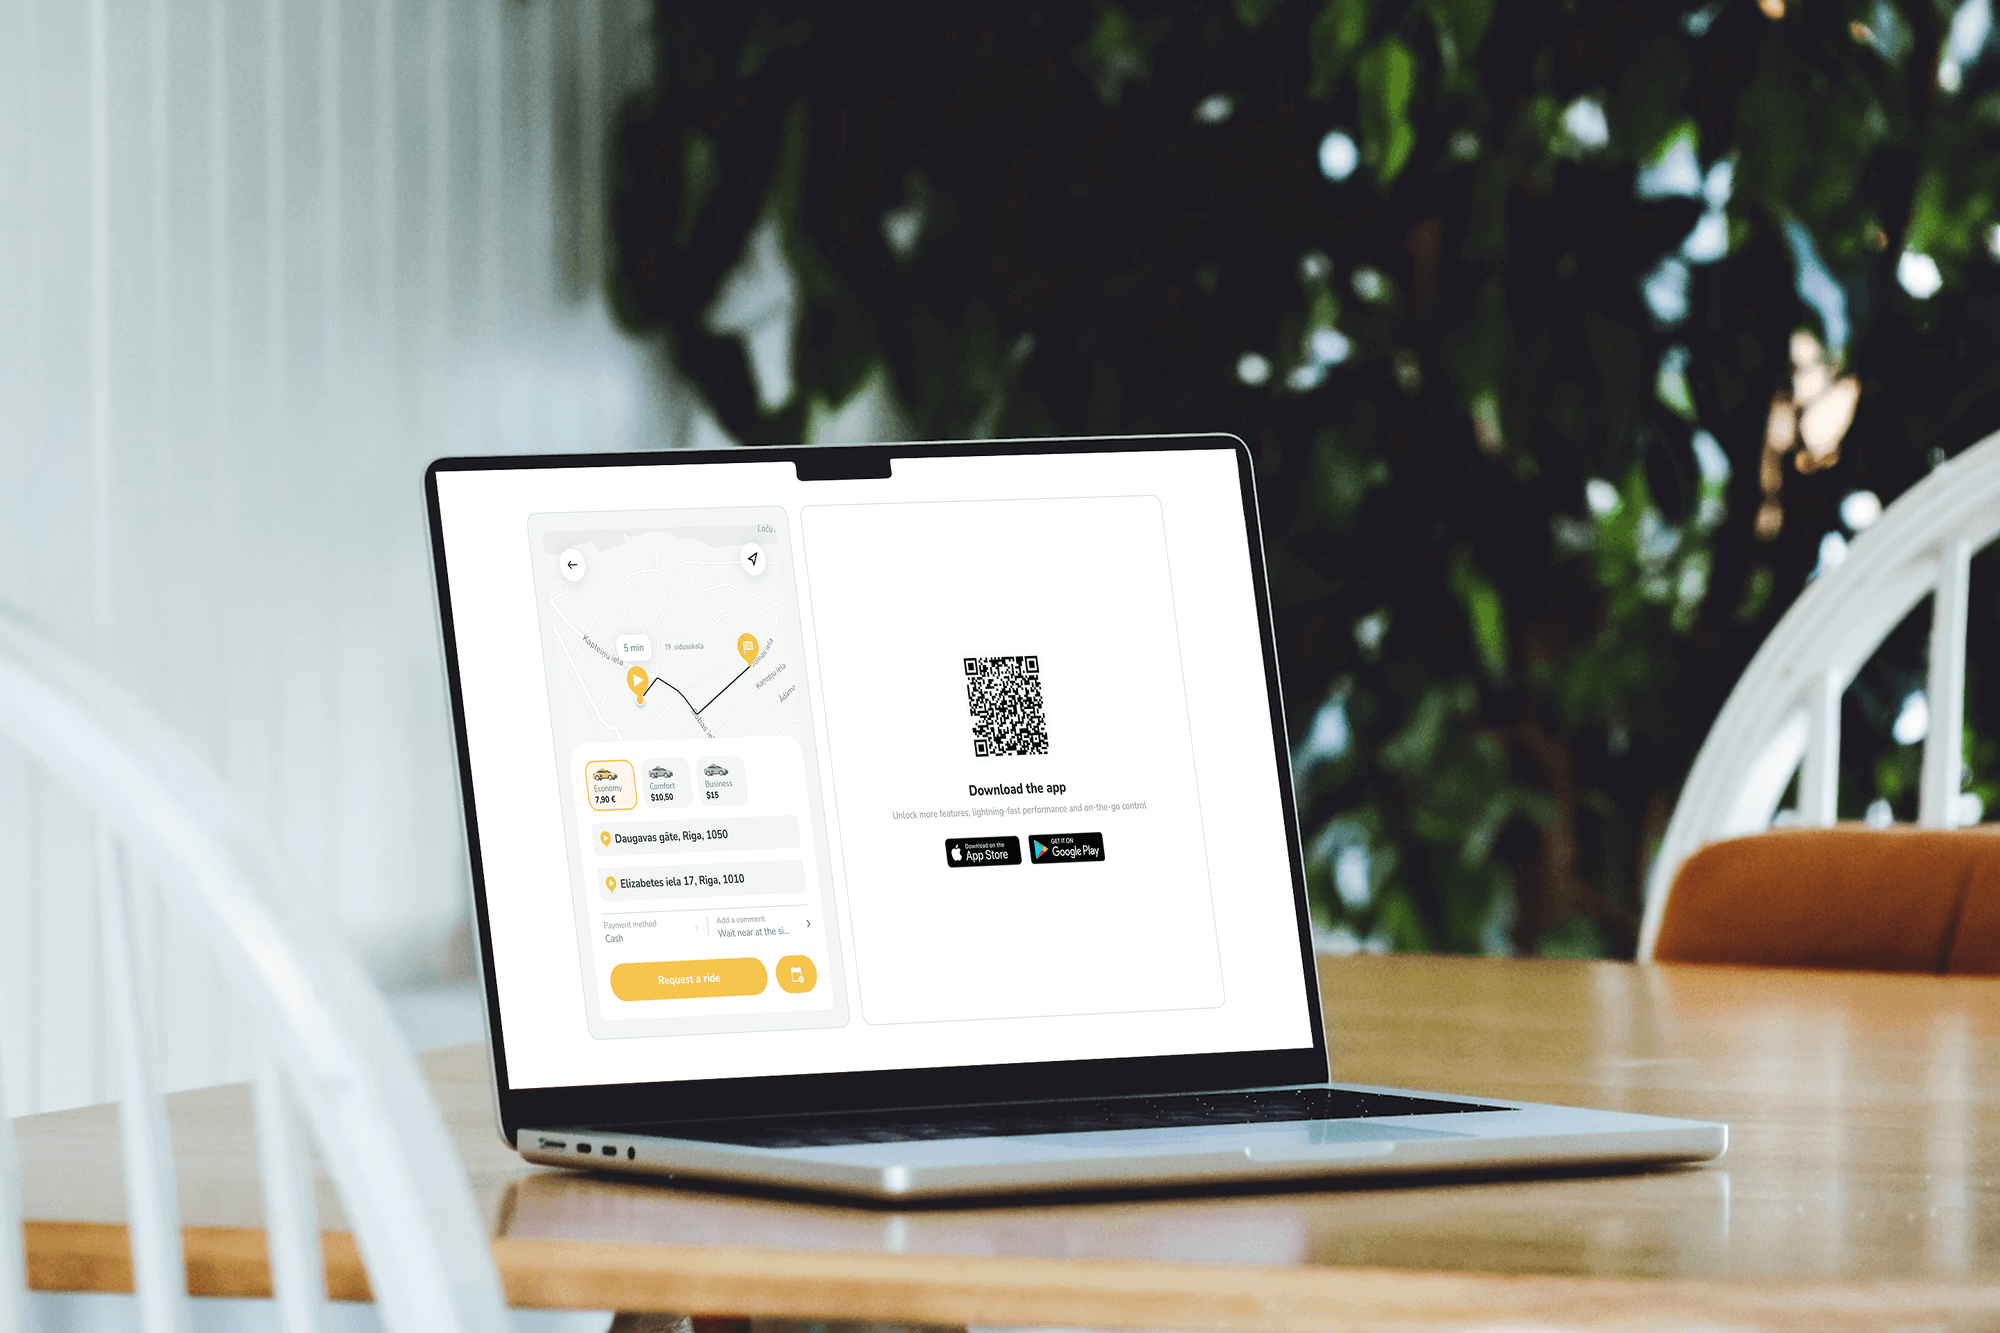
You need both, drivers and riders, to be interested in your service from day one – drivers will not stick around without rides and riders won’t pick you if there are no available drivers.
That means:
This is one reason local launches tend to perform better than city-wide launches. Smaller launch zones create stronger supply-demand density and better first user experience.
Most taxi businesses fail because not enough people know they exist, not because they lack great technology. Founders often spend months building operations, then treat marketing as something to figure out later, which can become an aspect in which the expenses start rising fast.
You need:
ATOM now offers a dedicated marketing agency for mobility businesses, built specifically for operators who need help acquiring riders, running paid campaigns, and building predictable demand. Without consistent rider acquisition, even a strong product struggles.
Many operators launch with taxis first, then expand into extra services once demand is stable.
That could mean:
This is one of the strongest advantages of launching on flexible mobility software. You are not building a single-use taxi app but a mobility platform that can grow. That is also why ATOM’s ride-hailing platform was built to integrate with broader shared mobility services instead of staying limited to one transport model.
If you’re launching a taxi business, building the right system usually is more important than building a software from scratch. The strongest operators start with a clear market gap, launch with ready-made tools, onboard drivers quickly, give riders flexible booking options, and invest in demand early.

🛴 The global e-scooter sharing market is forecast to more than double from $1.54 billion in 2025 to $3.12 billion by 2030. But what does it take to run a profitable operation? We break down revenue, costs and the rides needed to break even - with a practical financial example.
A scooter rental business can be profitable when revenue from rides covers fleet operations, overhead and the cost of replacing vehicles. The key is understanding how much each scooter earns, how much it costs to keep it available, and whether the business can sustain that balance throughout the year.
The market outlook points to further growth. According to The Business Research Company, the global e-scooter sharing market is forecast to grow from $1.54 billion in 2025 to $3.12 billion by 2030 - more than doubling over five years. The report identifies demand for sustainable urban transport, investment in smart-city mobility and integration with public transport as growth drivers. For operators, this creates opportunities, but profitability still depends on local demand, fleet utilisation and operating efficiency.
A busy summer month does not necessarily mean a profitable year. Discounts, maintenance downtime, winter demand and vehicle replacement can all change the result.
This article focuses on app-based electric scooter sharing, where customers typically pay an unlock fee and a per-minute rate. Hourly or daily scooter rental businesses follow similar principles, but their pricing and operating costs differ.
Below, we break down the main revenue drivers, costs and calculations to help you assess the opportunity.
There is no single standard price. Rates vary by city, operator, vehicle type and subscription or ride package. Before launching, compare local competitors’ prices alongside permit conditions and customer demand.
A common scooter-sharing pricing structure combines:
For example, a €1 unlock fee and a €0.20 per-minute rate produce a €4 fare for a 15-minute ride:
Unlock fee + (ride duration × per-minute rate) = ride fare
€1 + (15 × €0.20) = €4
Bike-sharing services may use per-minute pricing, timed passes or subscriptions. For a mixed fleet, model bikes and scooters separately because pricing, usage and operating costs can differ.
For financial planning, distinguish the advertised fare from net realised revenue per ride: revenue after discounts, refunds and applicable sales taxes, but before operating expenses such as payment processing.
Subscription and package revenue should also be allocated consistently. Counting the full package purchase and then counting its covered rides as additional revenue would overstate income.
Once you have an estimated net revenue per ride, the next calculation is:
Monthly revenue = deployed scooters × rides per scooter per day × operating days × net revenue per ride
For example:
100 scooters × 2 rides × 30 days × €4 = €24,000 monthly revenue
This is an illustrative calculation, not an industry benchmark. Here, €4 represents net realised revenue rather than the customer-facing fare in the earlier example.
The next question is how much of that revenue remains after costs.
Scooter sharing pricing examples:

Bike sharing pricing examples:

Rides per scooter per day is one of the most important inputs in a scooter-sharing business plan. The same fleet can lose money or generate a profit depending on how frequently customers use it.
Demand depends on several local factors:
A larger fleet does not automatically mean better utilisation. Adding scooters where demand is already served can increase costs without producing enough additional rides.
For planning, test conservative, base and strong-demand scenarios rather than relying on one forecast. For example, you could model 1, 2 and 3 rides per deployed scooter per day, then replace these assumptions with local evidence or pilot results.
Keep the denominator consistent. If your utilisation figure counts only available scooters, account separately for vehicles that are charging, awaiting repair or otherwise unavailable. Applying an available-vehicle usage rate to the entire fleet can overstate revenue.

According to research conducted by the National Association of City Transportation Officials, scooters are making up to two times more rides per vehicle per day compared to bikes. Bike services complete anywhere from 0.5 to 2.5 rides per day at an average of 1, with trends showing a shift away from traditional pedal bicycles as the interest in e-vehicles continues to grow.

An evaluation of the City of Chicago’s E-scooter pilot program found that over time the number of trips per day decreased from an average of 3.7 to 2.5. This aligns with the seasonality of mobility vehicles, which has been proven to impact ridership. Our experience shows that there can be decreases between 30 to 50 percent during the off-season.
In short, the average rides per day you can count on for bike sharing services is 0.5 to 2.5, and 1.8 to 5 for scooter sharing services.
Revenue is only one part of the calculation. A useful financial model separates costs that change with ride volume from costs incurred per vehicle or across the business.
Vehicle acquisition and replacement
Include scooters, batteries, spare parts, shipping and deployment preparation. Estimate a realistic useful lifespan and residual value. Depreciation spreads the vehicle’s cost over that lifespan; your cash-flow forecast must also reflect when you actually pay for the fleet and its replacements.
Charging and battery swapping
Include electricity, staff time, collection or swapping routes, charging equipment and any spare batteries required. Electricity alone does not represent the full cost of keeping scooters charged.
Maintenance and repairs
Budget for inspections, tyres, brakes, labour and spare parts. Repairs also affect revenue when vehicles are unavailable.
Rebalancing and field operations
Scooters may need to be moved from low-demand locations, collected after incorrect parking or returned to service. Include field staff, service vehicles and transport costs.
Payment processing
Check both percentage fees and fixed transaction charges. Model these against the way customers actually pay, including individual rides, wallet top-ups and packages.
Software and connectivity
Include the vehicle-sharing platform, IoT connectivity, SIM cards and any additional integrations or services.
Customer support and marketing
Budget for rider enquiries, refunds, acquisition campaigns and retention activities. Account for promotional discounts in revenue so they are not inadvertently counted twice.
Permits, insurance and overhead
Include applicable city fees, insurance, storage, premises, management and administration. The requirements and costs depend on the operating market.
Theft, damage and losses
Allow for unrecovered vehicles and damage beyond normal maintenance. Avoid counting the same losses again within another cost category.
Seasonality
Forecast each month separately. Lower winter revenue may coincide with ongoing software, storage, insurance and staffing costs, even if part of the fleet is withdrawn.
The following simplified example shows how utilisation changes the result.
Illustrative assumptions - not ATOM customer averages or quoted supplier prices:
The resale assumption uses the midpoint of an estimated €100–€200 per scooter range after three years. Assuming all 100 scooters remain saleable, this gives a residual fleet value of €15,000.
Monthly depreciation is therefore:
(Fleet acquisition cost − residual value) ÷ useful lifespan in months
(€100,000 − €15,000) ÷ 36 ≈ €2,361 per month
Actual resale proceeds depend on vehicle condition, battery health, the number of scooters remaining saleable and selling costs.
The 40% variable-cost assumption provides a simple starting point for forecasting. In practice, charging, maintenance and field-operation costs depend on usage, staffing and local conditions, so they should be itemised as the business plan develops.
Fixed costs cover separate expenses that remain broadly unchanged across these scenarios. Allocate each expense only once to avoid double-counting staff, charging or maintenance.
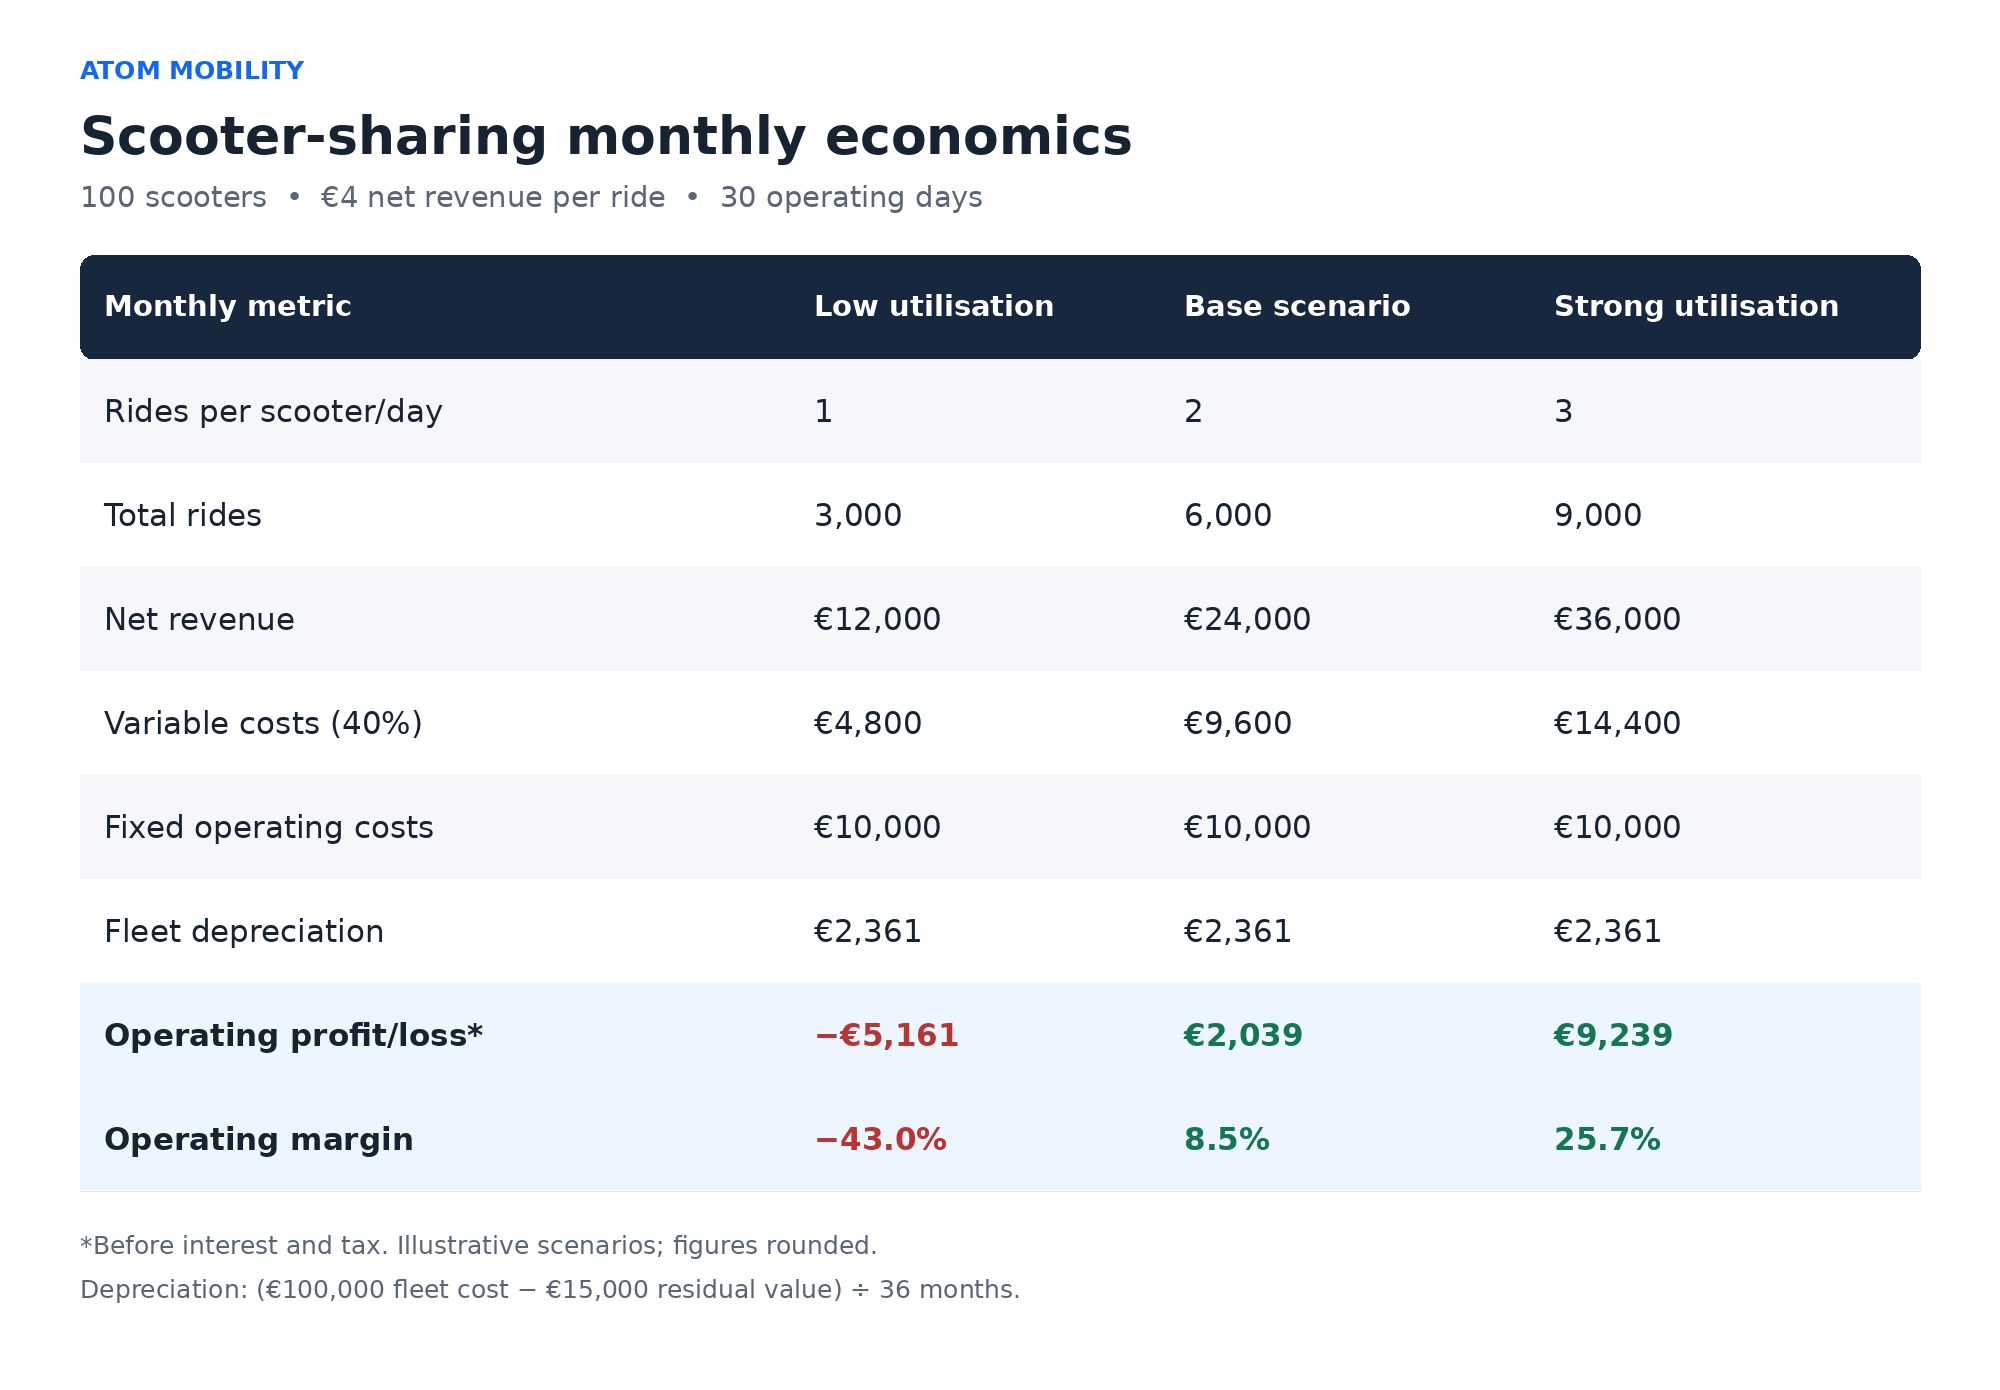
At one ride per scooter per day, the fleet does not generate enough revenue to cover its costs. At two rides, the business produces approximately €2,039 in monthly operating profit. At three rides, operating profit reaches approximately €9,239 per month before interest and tax.
The difference illustrates why utilisation matters: fixed expenses and depreciation continue even when scooters receive fewer rides. However, these monthly results should not be treated as annual forecasts without accounting for seasonality.
First, calculate the contribution from each ride:
Net revenue per ride − variable cost per ride = contribution per ride
In this example:
€4 − €1.60 = €2.40
Then calculate monthly operating break-even, including depreciation:
(Monthly fixed operating costs + depreciation) ÷ contribution per ride
(€10,000 + €2,361.11) ÷ €2.40 ≈ 5,151 rides per month
Across 100 scooters and 30 operating days, that equals approximately 1.72 rides per deployed scooter per day.
This threshold applies only to the assumptions above. Lower realised revenue, higher operating costs or fewer operating days would raise it. Additional staff or equipment needed to support higher utilisation would also change the calculation.
When testing a different ride price, reassess the underlying costs rather than automatically holding them at 40% of revenue. A price increase does not necessarily increase charging or maintenance expenses, and it may affect customer demand.
Profitability and investment payback are different measures. Operating profit accounts for depreciation, while payback measures how long it takes to recover the cash invested.
In the base scenario, monthly operating cash generation before capital expenditure, working-capital changes, financing and tax is:
€24,000 − €9,600 − €10,000 = €4,400
At that constant level, recovering the €100,000 fleet purchase alone would take approximately 23 months. This is a simplified illustration, not a complete investment payback forecast.
The estimated €15,000 fleet resale proceeds would be received when the scooters are sold at the end of year three. They reduce depreciation in the profitability calculation but do not provide cash during the preceding operating months.
An actual forecast should also include setup costs, spare batteries, charging equipment, initial marketing and working capital. It must account for seasonal demand, subsequent vehicle purchases and replacement costs. If the business continues after selling its original fleet, it will also need to fund replacement vehicles.
Model at least a full seasonal cycle and extend the forecast through the expected fleet replacement period. A strong summer month should not simply be multiplied by 12 to estimate annual returns.
Focus on changes that improve revenue or reduce costs while maintaining a reliable service:
Measure the financial effect of each change. More rides improve the business when the additional revenue exceeds the cost of serving them.
ATOM Mobility’s Excel-based financial model provides a starting point for assessing scooter- and bike-sharing profitability. It helps operators explore how pricing, ride duration, utilisation and operating costs affect their financial results.
The model uses percentage-based cost assumptions for an initial comparison. Adjust these inputs to reflect your market, then refine your forecast using supplier quotes, local permit requirements and a detailed operating budget.

Your forecast should help answer:
Build conservative, base and strong-demand scenarios, then update the assumptions as actual operating data becomes available.
Contact the ATOM Mobility team to request the model and discuss the assumptions for your planned operation.
A profitable scooter-sharing business depends on matching fleet size and operating costs to real local demand.
In the illustrative model above, operating break-even occurs at approximately 1.72 rides per scooter per day. This is not a universal industry threshold: each operator’s result depends on pricing, cost structure, vehicle availability, lifespan and seasonality.
Before expanding, validate these fundamentals across a full operating cycle. Improving the performance of an existing fleet may generate better returns than adding more scooters.
The right software supports that work by helping operators manage pricing, monitor fleet activity, organise maintenance and understand usage patterns.
Planning a launch or reviewing an existing operation? Explore ATOM Mobility’s vehicle-sharing software and contact our team to discuss your fleet and request the financial model.
"State of art technology in mobile apps and dashboard, very good SLA!"
"Easy, nice looking, continuously updated and developed every month and most of all very reliable with a extreme high uptime"
"We used to work with a different service provider which wasn't fitting our needs. Switching to ATOM was an improvement on our side"
Use test credentials to log in - Phone number: +1 123123123, Code: 777777
Driver App demo credentials - Email: test@atom.com, Password: driver