Blog
Insights and news from the ATOM Mobility team
We started our blog to share free valuable information about the mobility industry: inspirational stories, financial analysis, marketing ideas, practical tips, new feature announcements and more.
We started our blog to share free valuable information about the mobility industry: inspirational stories, financial analysis, marketing ideas, practical tips, new feature announcements and more.
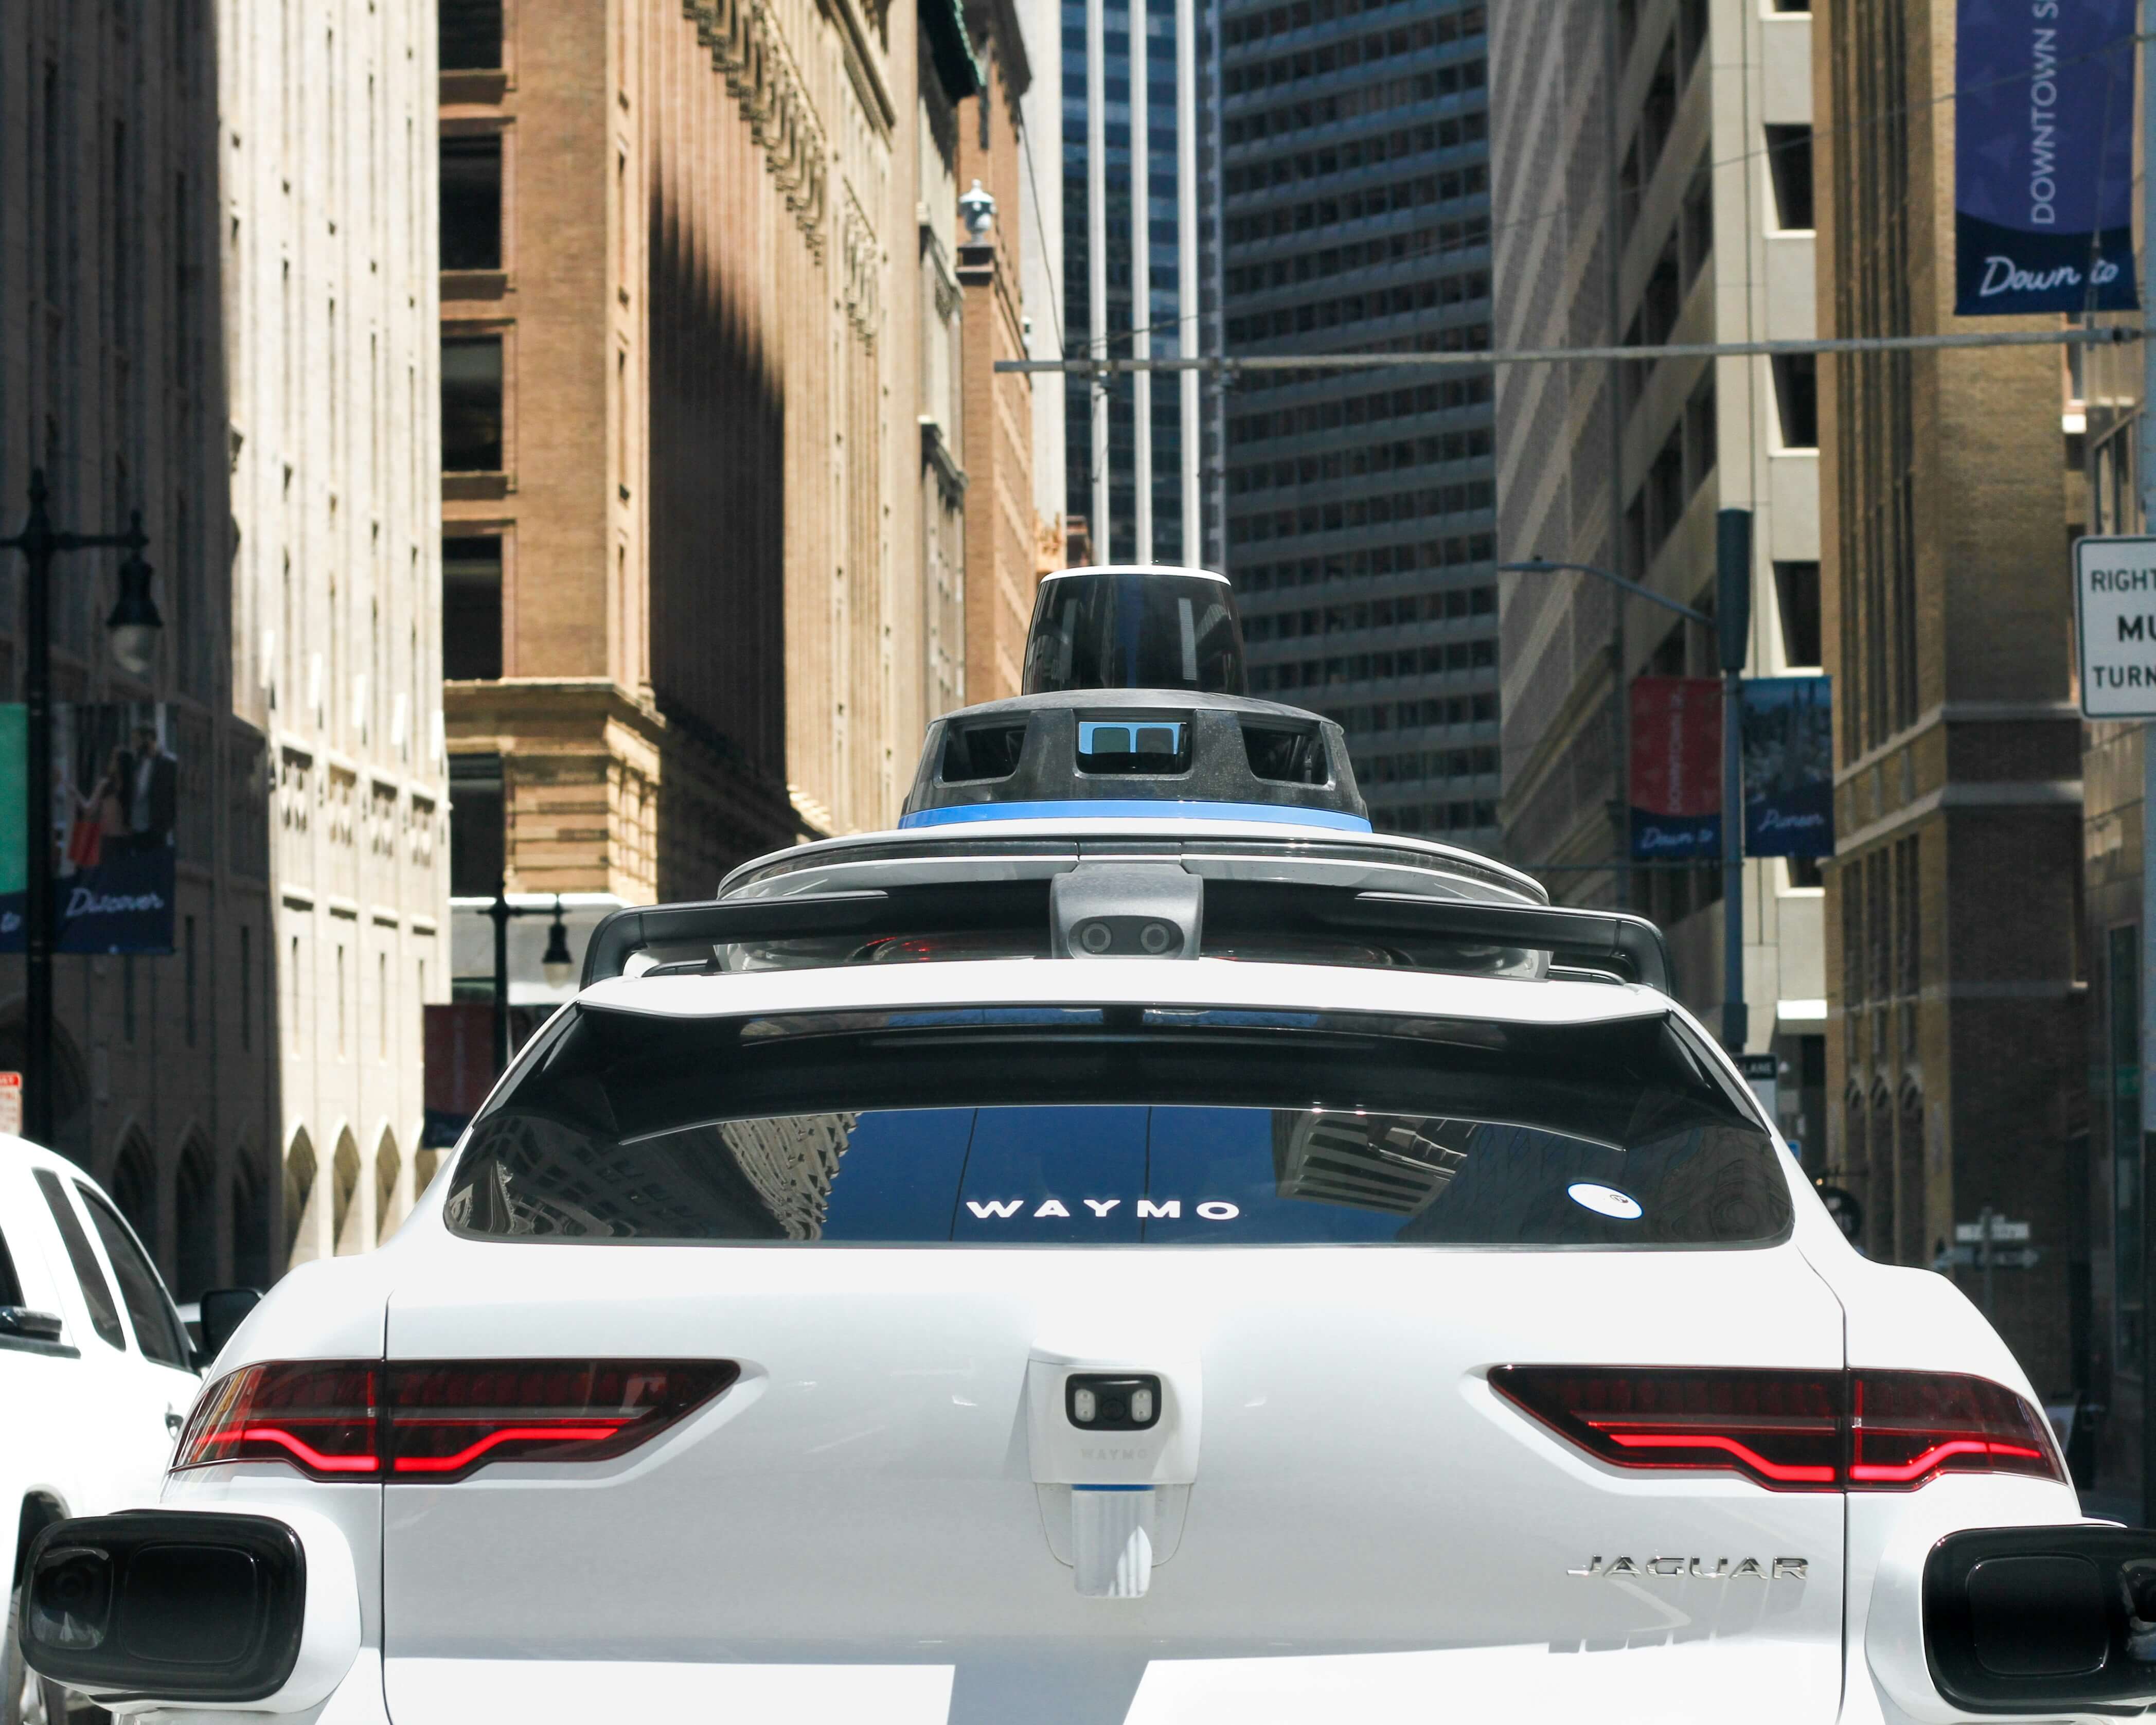
🤖 Who will actually operate Europe’s robotaxi fleets? Autonomous driving may remove the driver, but it doesn’t remove the work behind the car. Robotaxis still need charging, cleaning, maintenance, depots, customer support and someone managing the fleet every day. Early projects in Zagreb, Madrid and London illustrate different stages of deployment and how AV technology providers, fleet operators and booking platforms can work together. Taxi, rental and car-sharing companies already handle many of these tasks. What would it take to turn that experience into an autonomous fleet business?
For a taxi fleet owner, autonomous vehicles may seem to remove the most important part of the current business – the driver. But even without drivers, someone still needs to take care of the cars. They need to be owned or financed, charged, cleaned, inspected and repaired. Someone also needs to manage depots, deal with incidents, help customers and make sure enough cars are available.
The first robotaxi services and tests in Europe are already showing how this could work. The company that develops the autonomous driving technology does not always own or operate the cars. The app where customers book their rides may come from another company too. This could leave an important role for taxi, rental, car-sharing and other fleet companies that already know how to manage vehicles.
A taxi company today manages both cars and drivers. Drivers need to be recruited, scheduled, paid and supported. With a driverless fleet, these tasks would eventually disappear, but most of the work related to the cars would stay.
Autonomous cars still need charging or refuelling, cleaning, tyres, inspections, repairs and insurance. They also need somewhere to park when they are not working. If there is an accident or a technical problem, someone needs to deal with it and get the car back on the road. Customer support is still needed too when there are problems with bookings or payments, or when someone leaves something in the car.
Some of these tasks may even become more important. Robotaxis are expensive, and every hour a car spends charging, being cleaned or waiting for maintenance is an hour when it cannot take passengers. Moove, for example, already provides fleet ownership, depots, charging, maintenance and 24/7 operations for autonomous vehicles.
Drivers also do more than drive: they notice damage, report faults, help passengers and respond when something goes wrong. Without a driver, these responsibilities need clear processes and dedicated support. Existing fleet experience is an advantage, but operators will need to adapt it to vehicles running without someone behind the wheel.
There can be several companies behind one robotaxi ride. One provides autonomous driving technology, another may own the cars, and a local company can take care of the fleet. A platform such as Uber can then connect the cars with passengers. Sometimes one company may do several of these things, but this is not always the case.
Zagreb is one example. Pony.ai provides the autonomous driving system, Verne owns and operates the fleet, and Uber connects it with customers through its app. Autonomous rides became commercially available through Uber in August 2026 with a licensed operator onboard. On 10 September, Pony.ai and Verne also started fully driverless passenger test rides on a 22-kilometre route connecting parts of Zagreb with the airport. These are still limited test rides, not a fully driverless service across the whole city.
A similar model is being tested in Madrid. WeRide, Uber and AVOMO received permission in September 2026 to start testing and mapping under Spain’s ES-AV framework. The first 20 vehicles have an onboard specialist. WeRide provides the autonomous technology, Uber connects the cars with passengers, and AVOMO takes care of fleet operations. Commercial operations are planned for later in 2026, but the current permit is for testing and preparation rather than a general driverless taxi service.
In London, Wayve and Uber launched supervised autonomous passenger rides in September 2026. Customers can be matched with an autonomous vehicle through the Uber app, but there is still a licensed driver in the car.
The plans for the next few years are already much bigger. Pony.ai and Uber announced in August 2026 that they plan to deploy more than 2,000 robotaxis in Europe, starting with Zagreb and later expanding to four more European cities.
Bolt and Lucid announced another partnership in September, with Bolt aiming to deploy at least 25,000 autonomous Lucid vehicles across European cities. This is a future target, not 25,000 cars already operating today.
How these fleets are owned and operated may also be different from one city to another. Local regulations, available vehicles, charging and depot infrastructure and partnerships will all have an effect on how each service is set up.
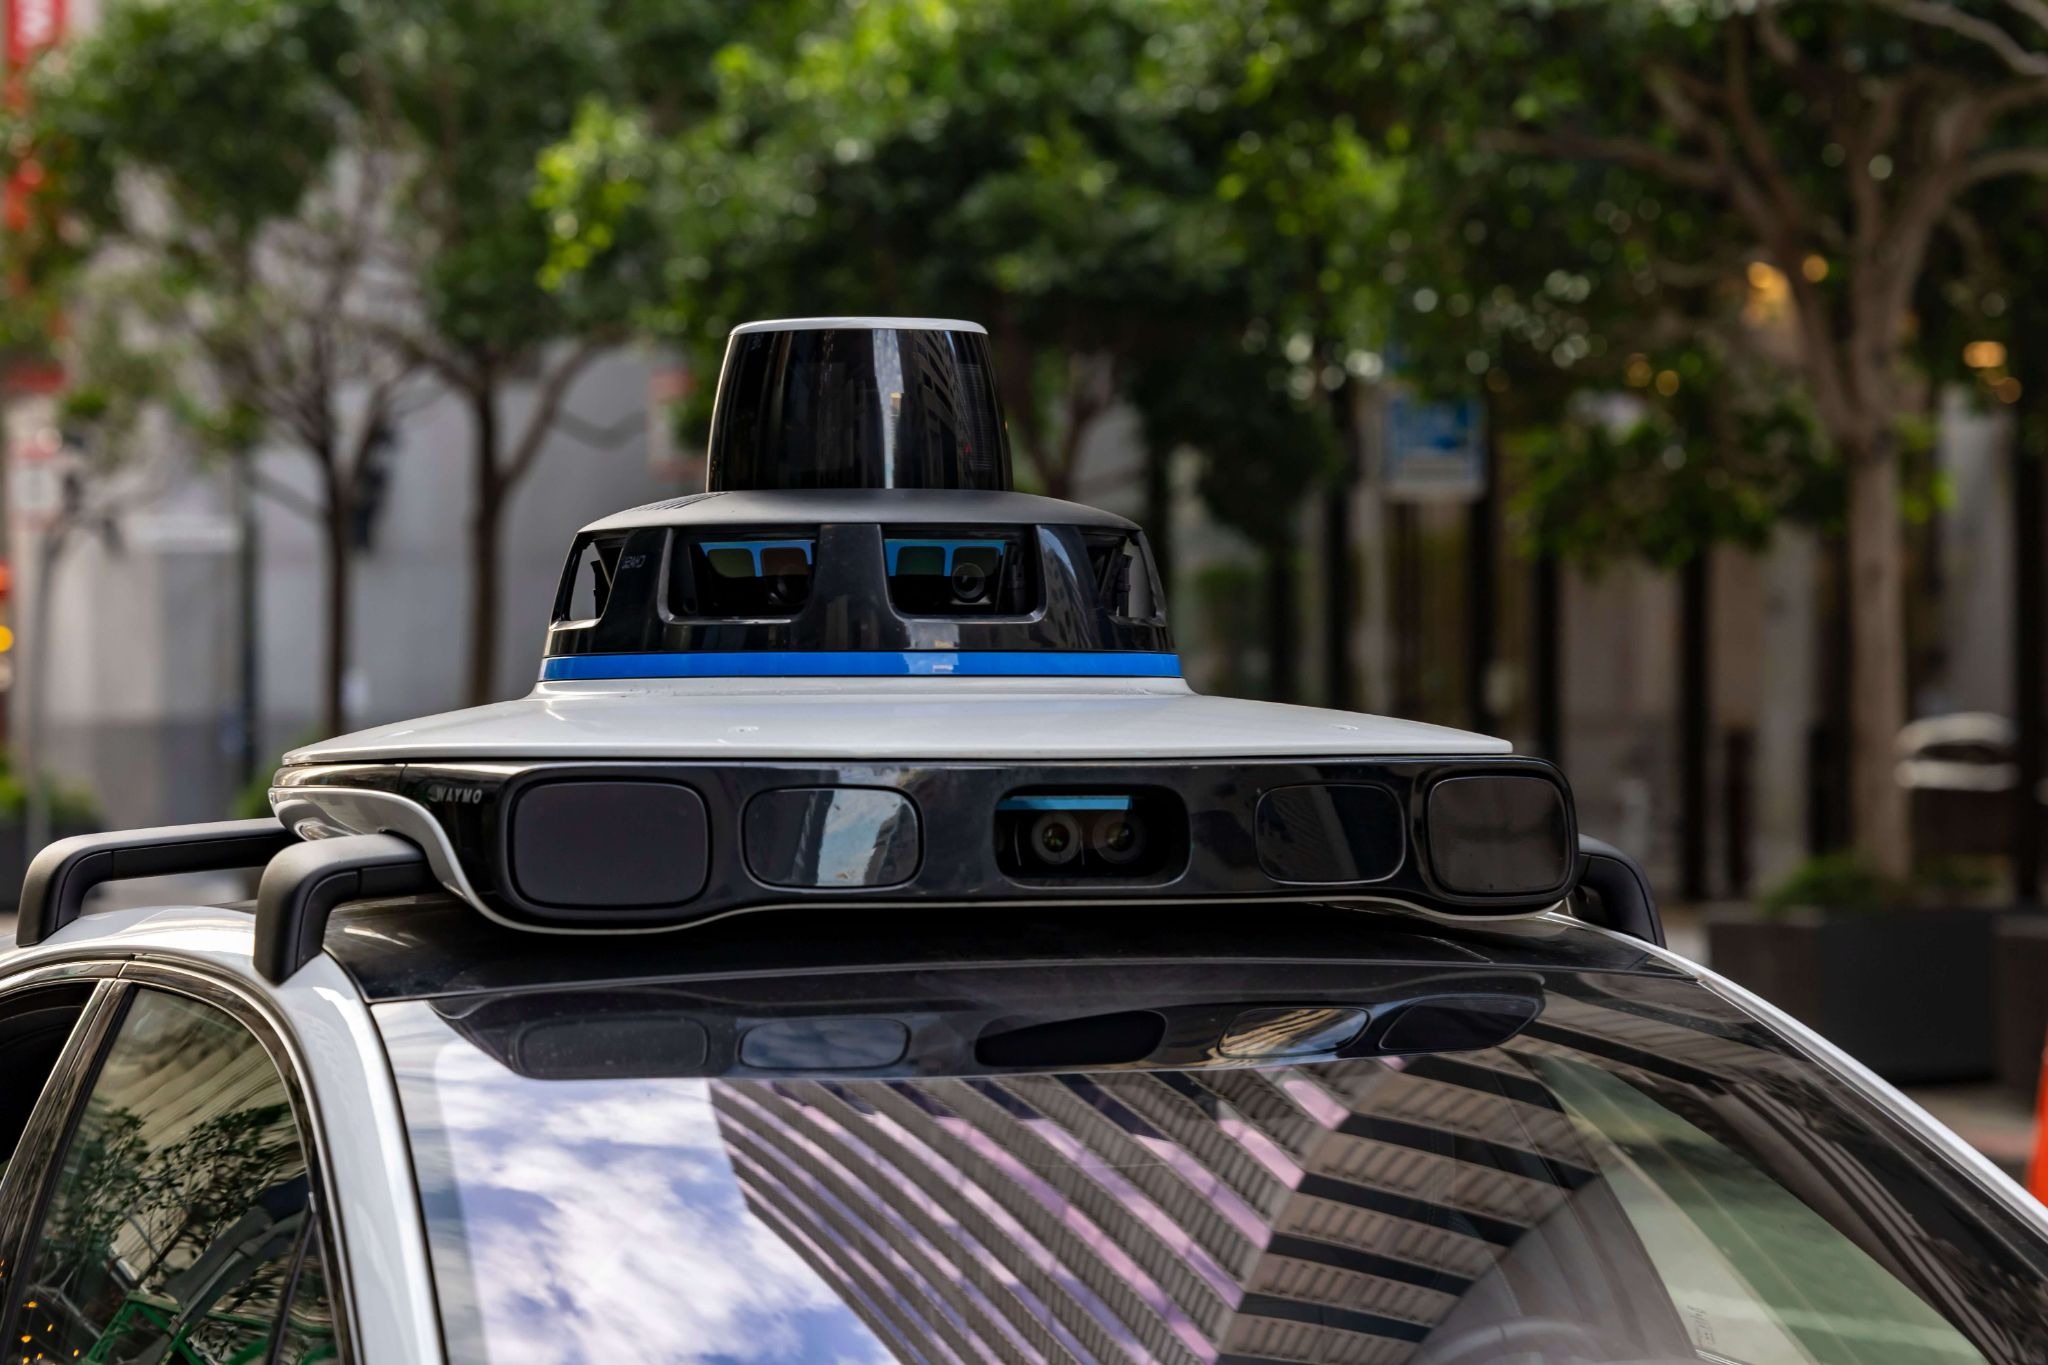
Taxi companies already do many of the things that would still be needed with an autonomous fleet. They maintain cars, deal with insurance and incidents, provide customer support and make sure enough vehicles are available. Some also already have their own depots, charging infrastructure or maintenance partners.
One possible model can already be seen in Zagreb. A local company owns and operates the autonomous fleet, while a larger ride-hailing platform brings customers. In the future, an existing taxi company could potentially have a similar role. Instead of managing cars and drivers, it could manage autonomous cars that receive bookings through a larger platform.
This does not mean platforms such as Uber will always rely on other companies to own the cars. Uber’s 2026 agreement with Rivian includes up to $1.25 billion in milestone-dependent investment and says that Uber or its fleet partners may purchase the autonomous vehicles. Uber is also developing infrastructure for autonomous fleets. Different ownership models are therefore possible.
Autonomous vehicles could also become interesting for rental and car-sharing companies, although this is probably further in the future. These businesses already manage vehicles, maintenance, cleaning, charging, bookings, customer accounts and payments, so much of the practical work is similar.
Autonomous driving could also change how rental and sharing cars are moved. Today, an employee may need to drive a car from one location to another. In the future, the vehicle could potentially do this itself within an area where autonomous driving is approved. It could even become possible for a rental car to drive itself to a customer’s pickup point.
Without drivers, it becomes especially important to understand how much time each vehicle is actually working. Every hour spent charging, being cleaned, waiting for maintenance or simply sitting unused means less time carrying paying passengers.
Some useful KPIs could be available hours per vehicle, paid trips per vehicle each day, revenue per available vehicle/day, empty kilometres, charging and maintenance downtime, cost per trip and incidents that need human help. These are most popular robotaxi industry KPIs of what a company could measure during a pilot.
For example, if cars spend too much time waiting to charge, the charging setup may need to change. A lot of empty kilometres could mean the cars are not in the right places, while too much maintenance downtime could make a vehicle more expensive to operate.
For either model, the business case depends on the partnership terms: who finances the vehicles, who carries the risk when demand is low, and how revenue and operating costs are shared. Operators should assess what remains after vehicle financing, insurance, charging, maintenance and partner fees. Depots, local service teams and reliable fleet availability could make an operator a valuable partner, but profitability still needs to be demonstrated.
One option for taxi fleets would be to work with an autonomous driving company and a larger ride-hailing platform. The local company could own or manage the cars and take care of the fleet, while customers book their rides through the larger platform.
Another option could be possible in cities where large ride-hailing platforms are not present or have limited coverage. A local company could work with an approved AV provider while using its own app, bookings, payments, customer support and fleet management.
In both cases, a company cannot simply buy autonomous cars and start offering rides. The technology needs to be approved, and local rules have to allow the service. These rules will also be different across Europe. Great Britain, for example, introduced its Automated Passenger Services permitting framework in 2026. Services similar to taxis or private hire vehicles need consent from the relevant local authority, while responsibility for the autonomous driving technology and the passenger service are treated separately.
A company does not need to have autonomous cars today to start preparing. A good first step is understanding the current fleet in detail – what each vehicle costs, how many hours it is available, how much time it spends charging or being repaired, and when cars are used the most.
Charging, cleaning, maintenance and depot processes are also worth looking at because all of these will still be needed with autonomous vehicles. A company interested in an AV pilot can then choose a location and use case, look at the local permit process and start talking to autonomous driving technology providers.
The software will also need some preparation. Customers still need to book and pay for rides, while the company needs fleet information, customer support, reporting and connections between its own systems and the AV technology. Starting with a small pilot makes it possible to test all of this before trying to build a larger service.
ATOM Mobility already provides many of the software functions used by taxi, ride-hailing, rental and sharing companies, including customer apps, bookings, payments, fleet management, maintenance tasks, analytics and APIs. Its ride-hailing software includes passenger and driver apps, dispatch, payments, fleet data, analytics and integrations. The ATOM Mobility API can also exchange data about vehicles, bookings, rides, payments, telemetry and maintenance tasks.
ATOM Mobility does not provide autonomous driving technology. This would come from a specialised AV company, and each project would have its own technical requirements and local approvals. For an AV pilot, ATOM Mobility could work with the fleet company and AV provider on the rider experience, integrations, fleet management and the data needed to measure how the pilot is working.
If you operate a taxi, rental or sharing fleet and want to explore an AV pilot, ATOM Mobility can help plan the booking and fleet-management setup, integrations and metrics you would need to test together with an AV technology partner.
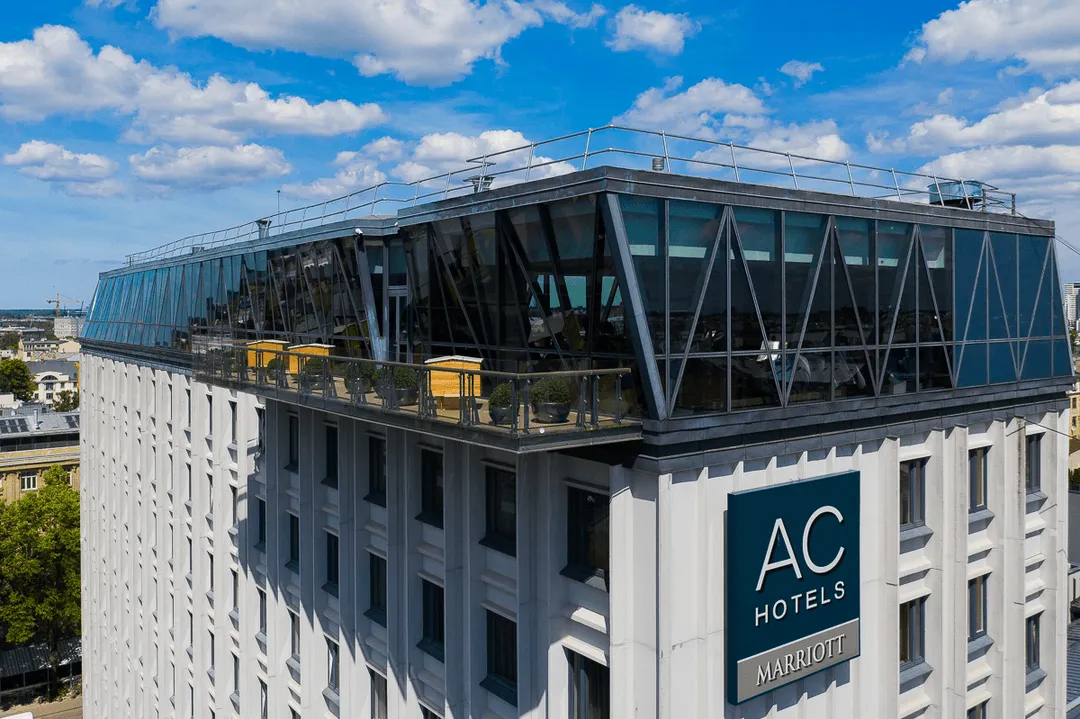
👉 ATOM Connect 2025 is an exclusive shared mobility networking event hosted by ATOM Mobility in collaboration with INVERS. This focused gathering will bring together industry leaders, innovators, and decision-makers from Europe's car-sharing and car-rental sectors to explore the future of shared mobility.
What happens when professionals from Europe’s car sharing and car rental industries gather under one roof? You get a day filled with fresh ideas, insightful discussions, and valuable connections that help shape the future of mobility. That’s what awaits at ATOM Connect 2025 - a dedicated industry event hosted by ATOM Mobility in partnership with INVERS.
This year’s gathering takes place on October 30, 2025, in Riga, Latvia, at the panoramic top floor of the AC Hotel by Marriott. With views stretching across Riga’s historic Art Nouveau district, the setting offers an inspiring backdrop for meaningful conversations about the next steps in shared mobility.
Date & Time: October 30, 2025, from 15:00 onwards
Location: AC Hotel by Marriott, Riga (top floor with panoramic views)
Hosts: ATOM Mobility & INVERS
Format: Expert talks, interactive Q&A, networking sessions, and evening drinks
Topics covered:
- Market insights from INVERS
- Scaling car sharing businesses
- Digital transformation in rentals
- Corporate mobility opportunities
- Eastern Europe’s shared mobility landscape
Learn from industry experts
The agenda is designed to address today’s most relevant mobility challenges. Expect data-driven insights from INVERS, practical strategies for scaling car sharing operations, discussions on digital rental solutions and corporate mobility, plus a closer look at the unique opportunities and challenges in Eastern Europe.
The event will also be joined by BYD, one of the world’s fastest-growing electric vehicle makers, who will showcase their innovative, affordable EVs at our event.
Build valuable connections
ATOM Connect 2025 is a focused gathering that brings together operators, rental businesses, and mobility experts from across Europe. With a mix of talks, networking breaks, and an evening reception, the event offers the perfect setting to exchange experiences, discuss challenges, and explore future partnerships.
If you’re active in car sharing or rental industry and want to stay ahead in a rapidly evolving market, ATOM Connect 2025 is a must-attend event. Together with INVERS, we’re creating a space where the European shared mobility community can connect, learn, and look toward the future.
👉 Save the date and request your spot today*: https://www.atommobility.com/atom-connect-2025
*Please note: ATOM Connect 2025 is intended for shared car mobility and car rental industry professionals. Registration requests will be reviewed before confirmation.
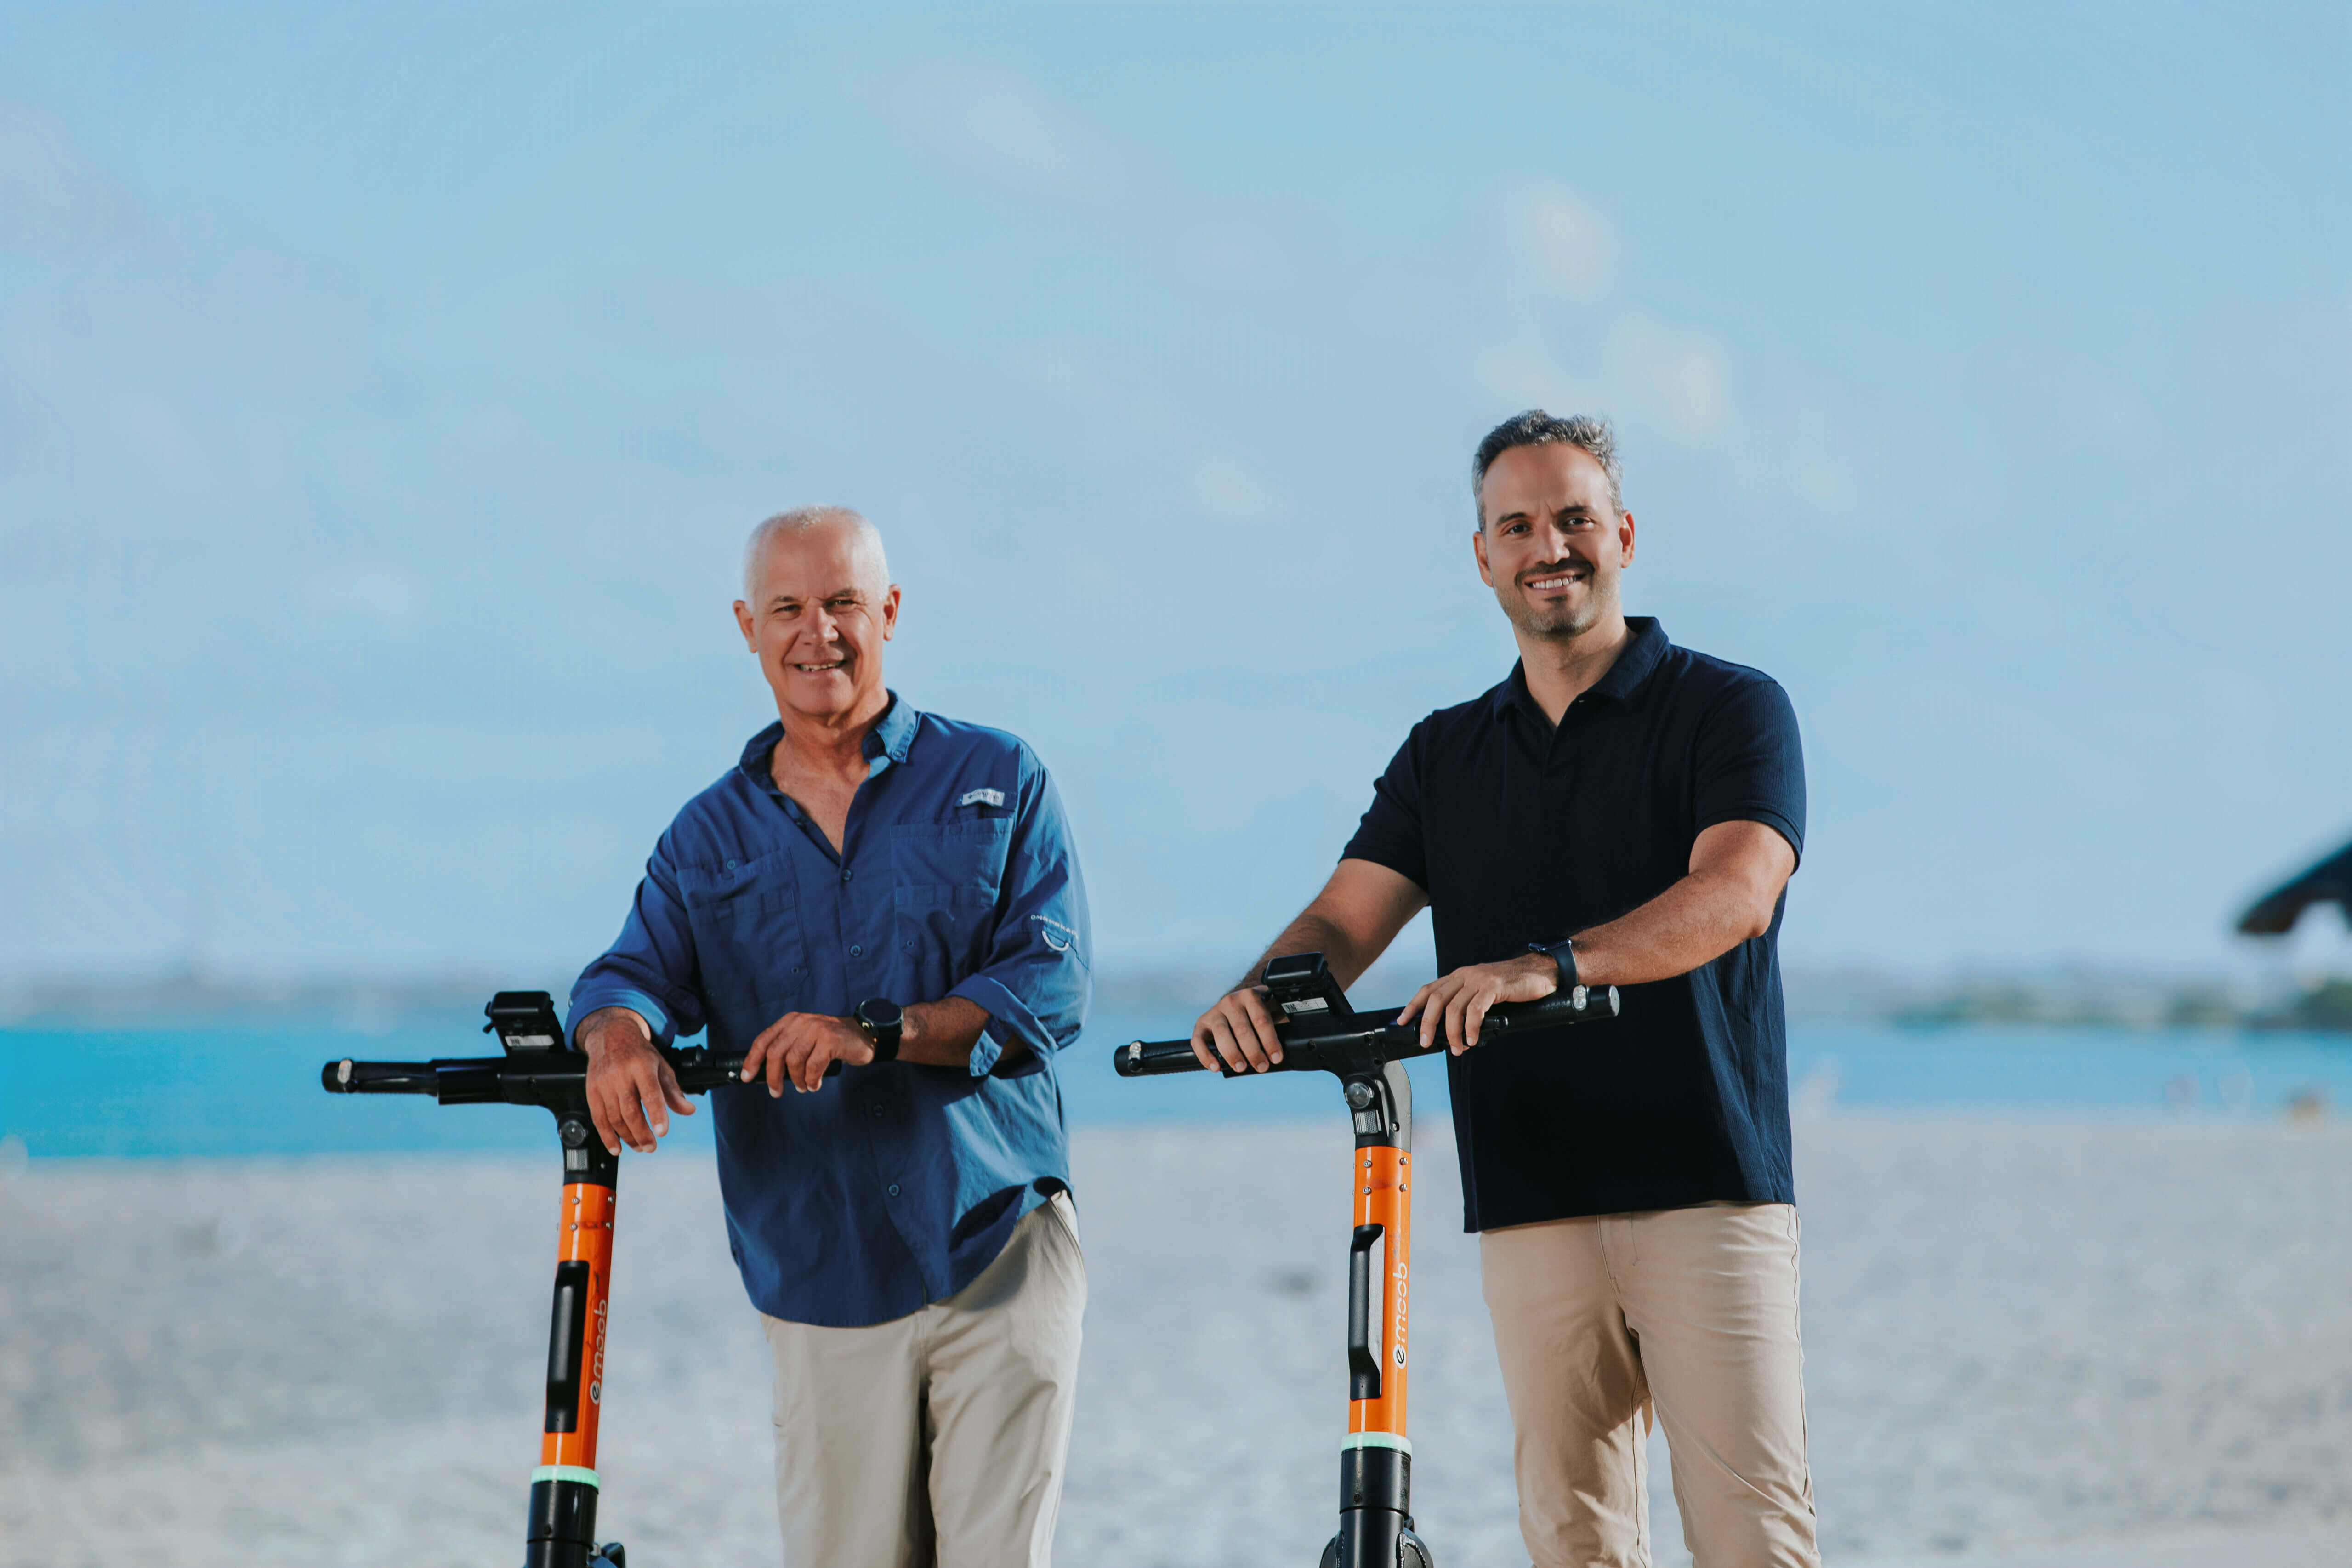
🌴 How e-moob became Aruba’s leading scooter operator 🚲⚡ From a Bird partnership in 2020 → to full independence with ATOM Mobility in 2023. Today: 150+ scooters in Aruba + fleet in Costa Rica. ⭐ 4.9/5 ranking on iOS & 4.8/5 on Android.
🌴 How e-moob became Aruba’s leading scooter operator 🚲⚡ From a Bird partnership in 2020 → to full independence with ATOM Mobility in 2023. Today: 150+ scooters in Aruba + fleet in Costa Rica. ⭐ 4.9/5 ranking on iOS & 4.8/5 on Android.
What began as a local partnership with Bird in 2020 has since grown into a fully independent scooter-sharing business with operations in Aruba and Costa Rica – and soon, mopeds in Spain. At the heart of this shift is e-moob’s decision to take full control of its fleet, its brand, and its technology. That control, Santos says, came with switching to ATOM Mobility.
Launch date: 2020 (with Bird), independent launch with ATOM Mobility in December 2024
Country: Aruba and Costa Rica
App Store: 4.9 / 5 ⭐
Google Play: 4.8 / 5 ⭐
Fleet: 150+ scooters in Aruba, smaller fleet in Costa Rica
Web page: https://e-moob.com
App Store: https://apps.apple.com/us/app/e-moob/id6642640340
Google Play: https://play.google.com/store/apps/details?id=e.moob.app
In a market as compact and tourism-driven as Aruba, micromobility is a unique challenge. There’s limited space, high operational costs, and intense competition for visitor attention. But for Luis Santos, co-founder of e-moob, it was also the perfect opportunity.
Starting in a market built for tourism
e-moob launched in Aruba, where the economy relies heavily on tourism - over 3 million visitors per year. Almost all of e-moob’s users are tourists, with 99% of rides coming from short-term visitors. The island’s layout and mild weather make it ideal for short scooter trips along the coastline, especially in popular resort areas.
“Aruba is a super small market, and it can get flooded quickly,” says Santos. “We learned from experience that we can’t go beyond 1,000 scooters here. So when we wanted to grow, we had to expand outside the island.”
That led to e-moob’s second market: Tamarindo, Costa Rica – another sunny, coastal town with a young, active tourist crowd. The business model remains the same: light, flexible mobility for short-distance use, tailored to tourism patterns.
Long setup, fast scale
Launching operations in Aruba wasn’t quick. “Before we even started, it took almost a year to get everything ready – registering the company, getting licenses, even just opening a bank account,” Santos explains.
The technical launch also had its challenges. When e-moob moved to its own brand using ATOM Mobility in December 2024, there were initial issues with starting rides due to firmware and hardware compatibility. “Some scooters couldn’t be unlocked properly, and we had a few tough days. But the team at ATOM Mobility helped fix it quickly, and within a week we had everything working smoothly.”
Before launching under the name e-moob, the team operated using their own brand called Evikes on the Bird platform. “That’s how Bird was working with partners back then,” says Santos. “It was our brand, but the operations were fully integrated with Bird’s system.” This setup helped them gain visibility among tourists – especially American visitors who already had the Bird app – but also came with limitations.
Switching to ATOM Mobility: Gaining control
Before launching under their own name, e-moob operated under Bird’s platform. While that brought initial visibility and trust – especially from American tourists who already had the Bird app installed – it came with limitations. All changes, pricing, or refunds had to go through Bird’s team. When parts or new scooters were needed, delays became a serious problem.
Eventually, the lack of flexibility pushed e-moob to go independent.
With ATOM Mobility, Santos and his team gained full control. “Now I can change prices, send bonuses, and refund directly. We also choose and buy our own units from Okai, instead of waiting for Bird. We manage customer service in-house. It’s been a major change.”
The result? e-moob is now operating at nearly the same revenue level with their new ATOM-powered fleet of 160 scooters as they were with their much larger Bird fleet of around 300 to 400 units. “We make almost the same amount of money with half the scooters,” says Santos. “That was an unexpected success.”
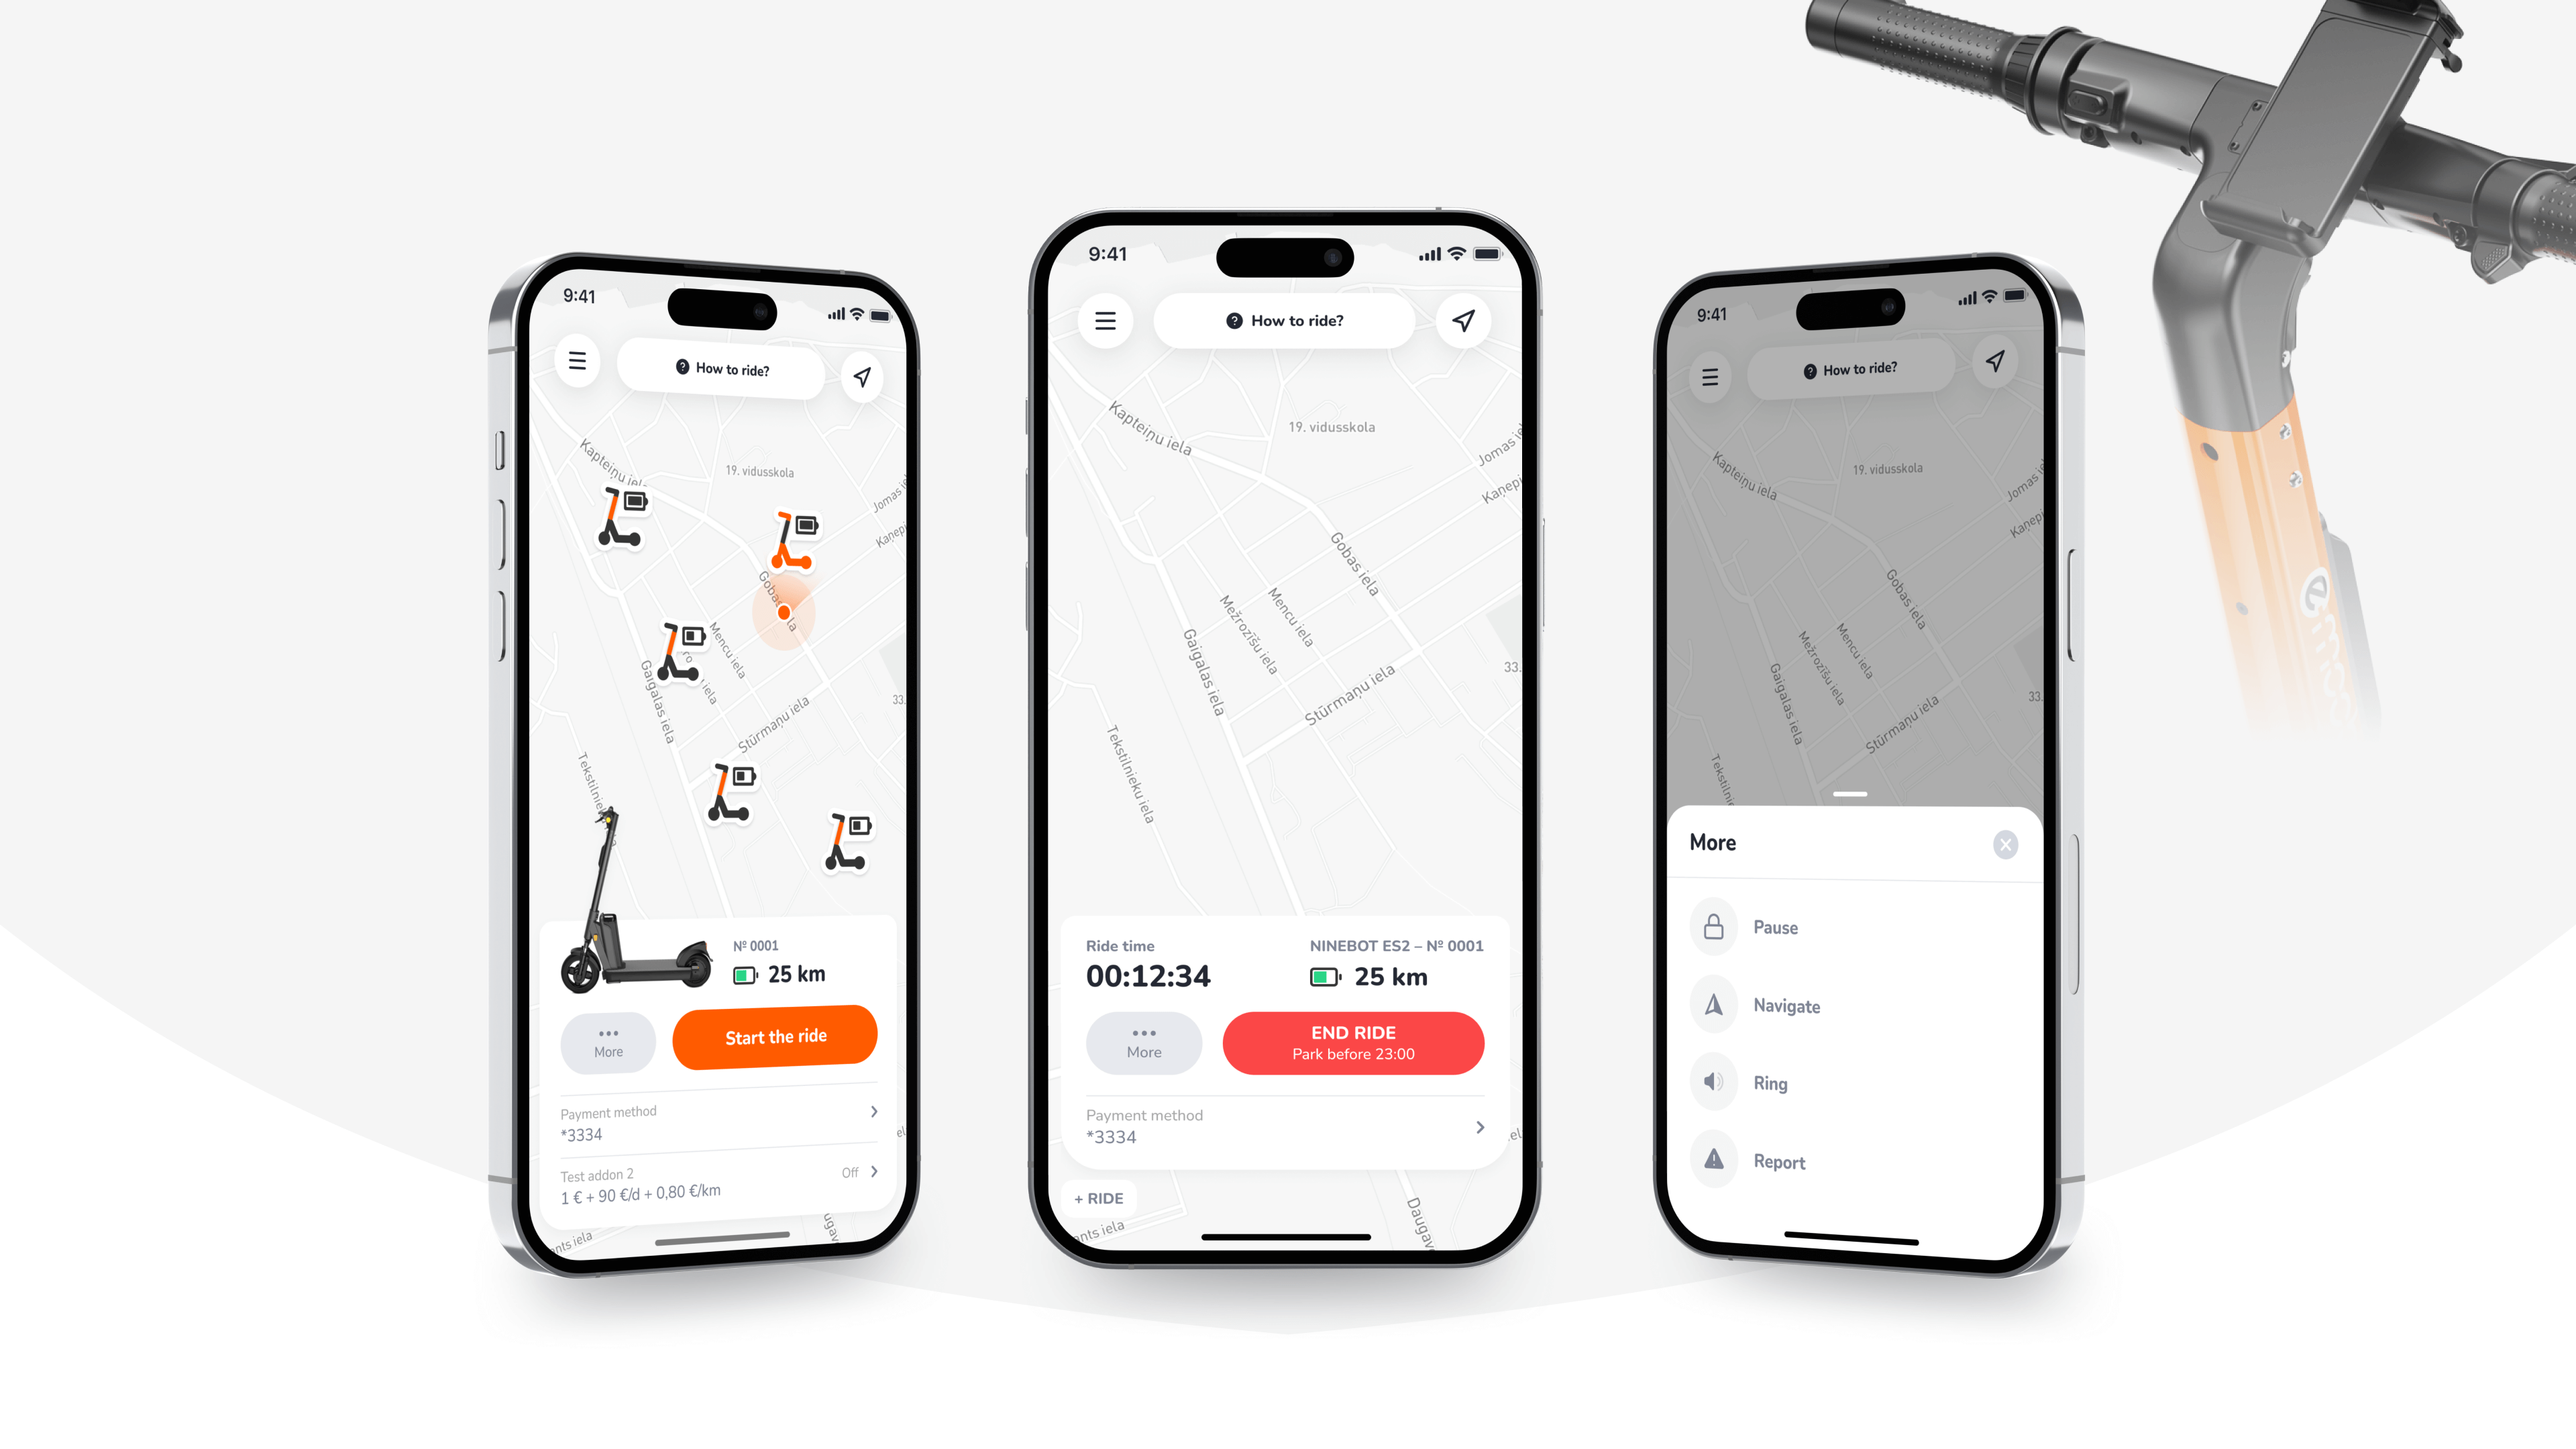
Adapting to the local market
Electricity prices in Aruba are high – around 2.5 times higher than in Miami – which directly impacts scooter charging costs. This shaped e-moob’s pricing strategy. Rides cost about $0.56 per minute and $1.07 to unlock, including the local 7% tax. These prices are slightly higher than in mainland U.S. markets but necessary to maintain profitability.
As for user features, subscriptions and loyalty programs haven’t played a big role yet. “Most of our users are tourists – they come, ride, and leave. There’s no long-term user behavior,” Santos explains.
Running the business day-to-day
Santos still handles customer support personally and uses ATOM’s admin tools daily to manage refunds, view ride history, and track issues. “We get very few support emails – maybe 10 to 15 a month, even with thousands of rides. Most issues come from signal delays when the scooters are in sleep mode.”
While e-moob doesn’t rely heavily on heatmaps or demand analytics (the team already knows exactly where to place the scooters in such a small market), the monthly dashboards and ride data remain useful for tracking performance.
Santos is also looking forward to using upcoming feature that allows tagging locations on the map – restaurants, hotels, or partner businesses – to increase visibility and engagement.
Challenges and strategic pivots
One of the biggest challenges came when Bird stopped supplying new hardware. “Our competitors arrived, and we needed new scooters, but Bird couldn’t deliver. We waited over a year, and that’s when we realized we had to build our own brand.”
Buying directly from Okai and using ATOM Mobility gave e-moob independence. It also opened the door to support multiple vehicle types. That’s essential for their next move: launching moped (Vespa-style) sharing in Spain.
“We’re already negotiating with suppliers,” says Santos. “We’re aiming to start next summer in Spain – our first European market. It’s a big step, especially since mopeds are a new category for us. New parts, new maintenance, new challenges. But we’re ready.”

Looking ahead: Europe and beyond
The moped launch in Spain isn’t just about growth. It’s a way to move into more scalable, tourism-driven markets. Aruba has reached its limit, and Costa Rica has proven slow to scale due to logistics and local bureaucracy. Europe offers a more mature market – and new opportunities.
e-moob is also in discussions with local delivery apps for third-party integrations. While current scooter zones are too limited to justify monthly fees, mopeds will expand the service range and open new B2B possibilities.
Santos is also exploring the potential of building stronger local loyalty by partnering with businesses and hotels. It’s a small use case, but one that could help bridge the gap between tourism and local use.
From hobby to ecosystem
Surprisingly, e-moob is a side business for Santos. His main company provides IT infrastructure for hotels and casinos, while he also manages a real estate firm and a smart home business in the U.S.
That existing network actually helped launch e-moob. “We started by placing scooters in private buildings developed by people I already worked with. Public spaces weren’t available at first, so private locations made it possible,” he recalls. “Now, we even have scooter parking inside the Ritz-Carlton and St. Regis hotels.”
Community, growth, and the power of being present
Santos regularly attends industry events like the Micromobility Conference. “It’s small, but valuable,” he says. “Meeting partners in person helps us move deals forward. Last year we made great connections. This year we’re closing our first moped deal because of those conversations.”
For Santos, success is not about buzzwords or fast scaling. It’s about growing smart, solving real problems, and building sustainable operations. “We’re proud of how far we’ve come. We’ve grown the fleet, expanded the business, and made something that works.”
Advice for new operators?
“Get full control from day one. Don’t depend on someone else’s rules,” Santos says. “The more control you have – over the operations, the pricing, the support – the better you can react to what your market really needs.”
With its strong base in Aruba, growing operations in Costa Rica, and exciting plans for Europe, e-moob is not just a scooter company – it’s a case study in smart, independent micromobility growth.
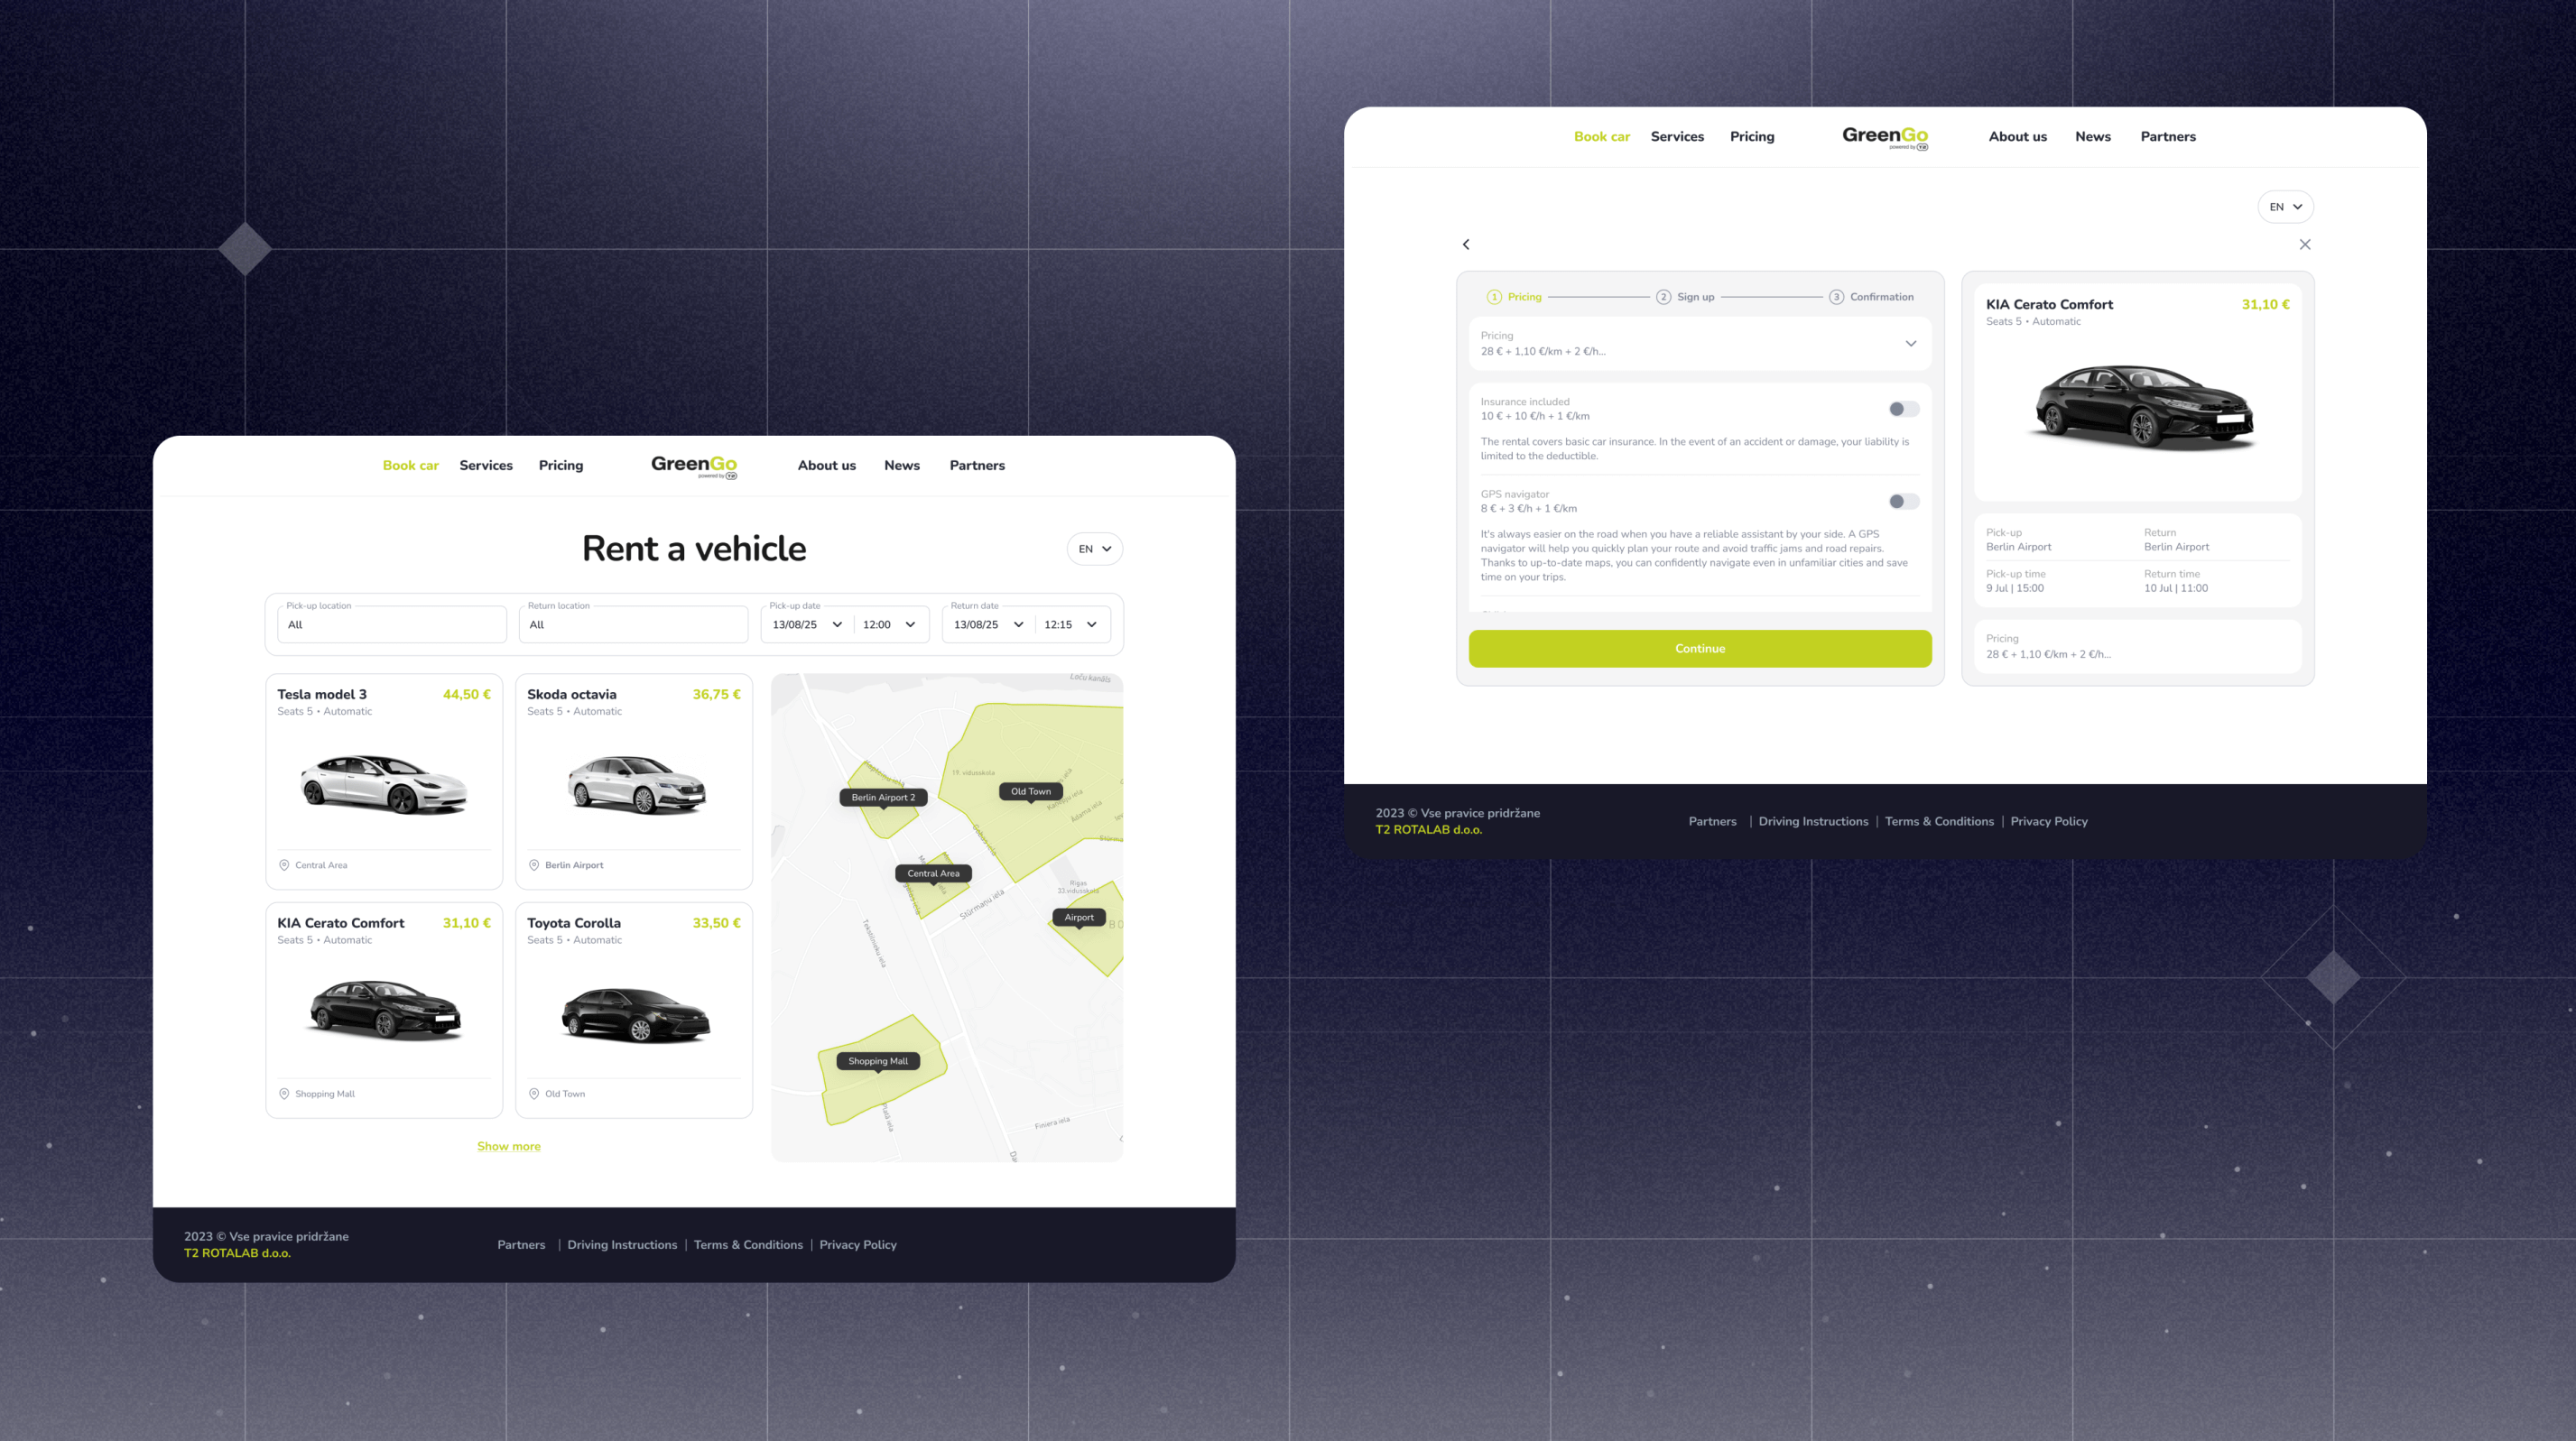
🚗 ATOM Mobility launches a new Web-booker for Digital Rental 🗓️ - letting customers book vehicles directly from the website. Frictionless, branded, and enabled by default for all rental merchants ✅
ATOM Mobility is introducing a new way for users to start their rental journey: the Web-booker widget 🗓️
With this tool, users can book a car (or other vehicle) directly from merchant's website without first downloading the rider app. It creates a smoother entry point for new users while keeping the app central for payments, ID verification, and ride management.
✅ A dedicated booking link for every merchant
✅ Customers choose area, vehicle, and rental period → confirm booking in seconds
✅ Widget syncs bookings into system automatically
✅ After booking, a QR code + App Store / Google Play links are shown so users can continue in the app
✅ In the mobile app, users finalize payment and ID/driver’s license verification before starting the trip
🎨 The widget matches app’s primary color for a seamless, branded look.
📊 Every booking now shows its Source – App, Web-booker, Dashboard, or API.
👉 Demo it here: app.atommobility.com/rental-widget
Many successful digital rental and mobility platforms combine web and app booking flows to maximize conversion.
Take Turo for example:
New ATOM Web-booker works the same way - creating an easy on-ramp from website, while letting the app handle verification and payments.
This feature also aligns with the broader industry evolution we covered in Traditional Car Rental vs Peer-to-Peer Car Sharing vs On-demand Car Sharing artticle. As booking models diversify, offering multiple access points - web + app + api – is becoming a standard expectation from customers.
The global car-sharing market (including peer-to-peer sharing) is projected to reach USD 28.7 billion by 2030, growing from USD 11.5 billion in 2025 at 20% annual growth rate, with digital-first players outpacing traditional operators. One of the biggest success drivers? Reducing onboarding friction and providing automated processes.
The message is clear: giving customers multiple, seamless entry points directly impacts conversion and utilization.
The Web-booker is enabled by default for all ATOM Mobility digital rental merchants for free. Just place the booking button on your website, and your customers are ready to go.
📩 Want to see how the Web-booker can boost your conversion and simplify rentals? Get in touch with our team and let’s set it up for you.
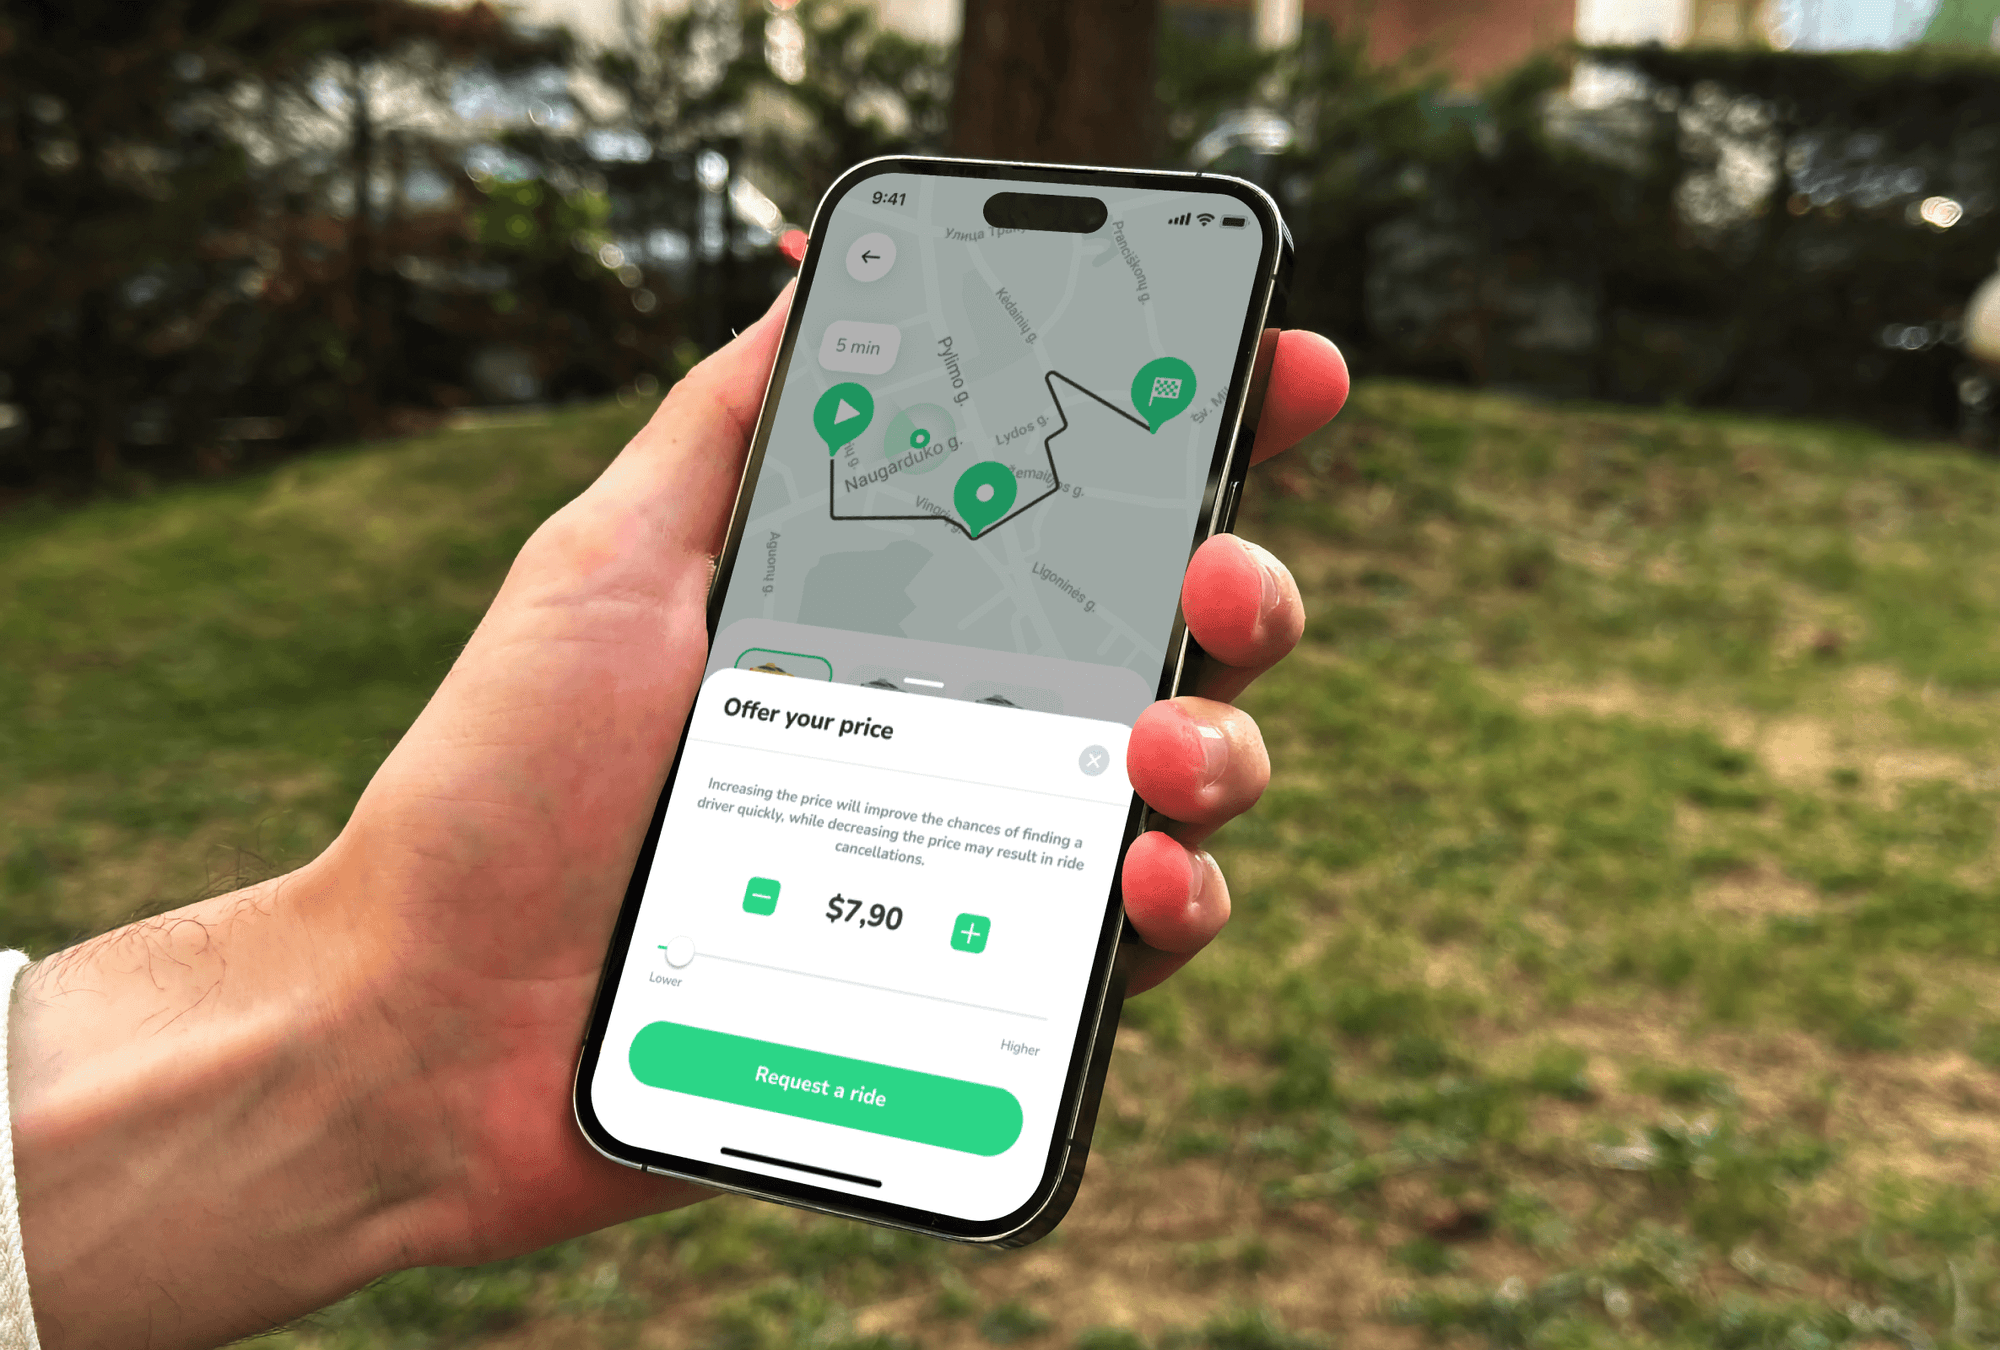
💸 ATOM Mobility launches “Offer your price” - a rider-controlled pricing feature. Riders can suggest higher or lower fares within pre-set limits. Boosts demand & helps stand out in competitive ride-hail markets 🚖🌍
The ride-hailing market is always changing. From Latin America to Eastern Europe, platforms like inDrive have popularized a new norm: letting riders suggest what they want to pay. Now, in response to this growing global trend, ATOM Mobility is proud to introduce: Offer your price – a fully configurable pricing feature built right into your rider app.
Available on all ride-hail projects, this feature lets riders propose a price – higher or lower than the default fare – within operator-set limits. Drivers can then accept or decline based on the offer.
Here’s how it reshapes the experience:
Your admin dashboard defines the limits – say, up to +500% from regular price and down to -30% – and the app calculates step sizes automatically:
Slider position adapts dynamically, depending on your defined range. And yes – the button color and style can be customized to match your brand 🎨.
You’ll find complete control and clarity:
In the driver app:
Real-world companies are already proving that rider-defined pricing works:
🚘 inDrive (LATAM, Africa, Asia)
Now one of the top global ride-hailing players outside the U.S. (over 200M downloads, active in 700+ cities across 45+ countries), inDrive built its brand around rider-negotiated pricing. It helps them stand out in price-sensitive markets and win over both drivers and passengers with more transparent pricing dynamics.
🚖 Comin (France)
A local success story, Comin has embraced flexible rider pricing to gain traction in several French cities (onboarded 6,000+ drivers). The feature gives them an edge against larger platforms, offering more freedom for users and better utilization for drivers.
These examples show that letting riders bid their price isn’t just a gimmick – it’s a growth strategy.
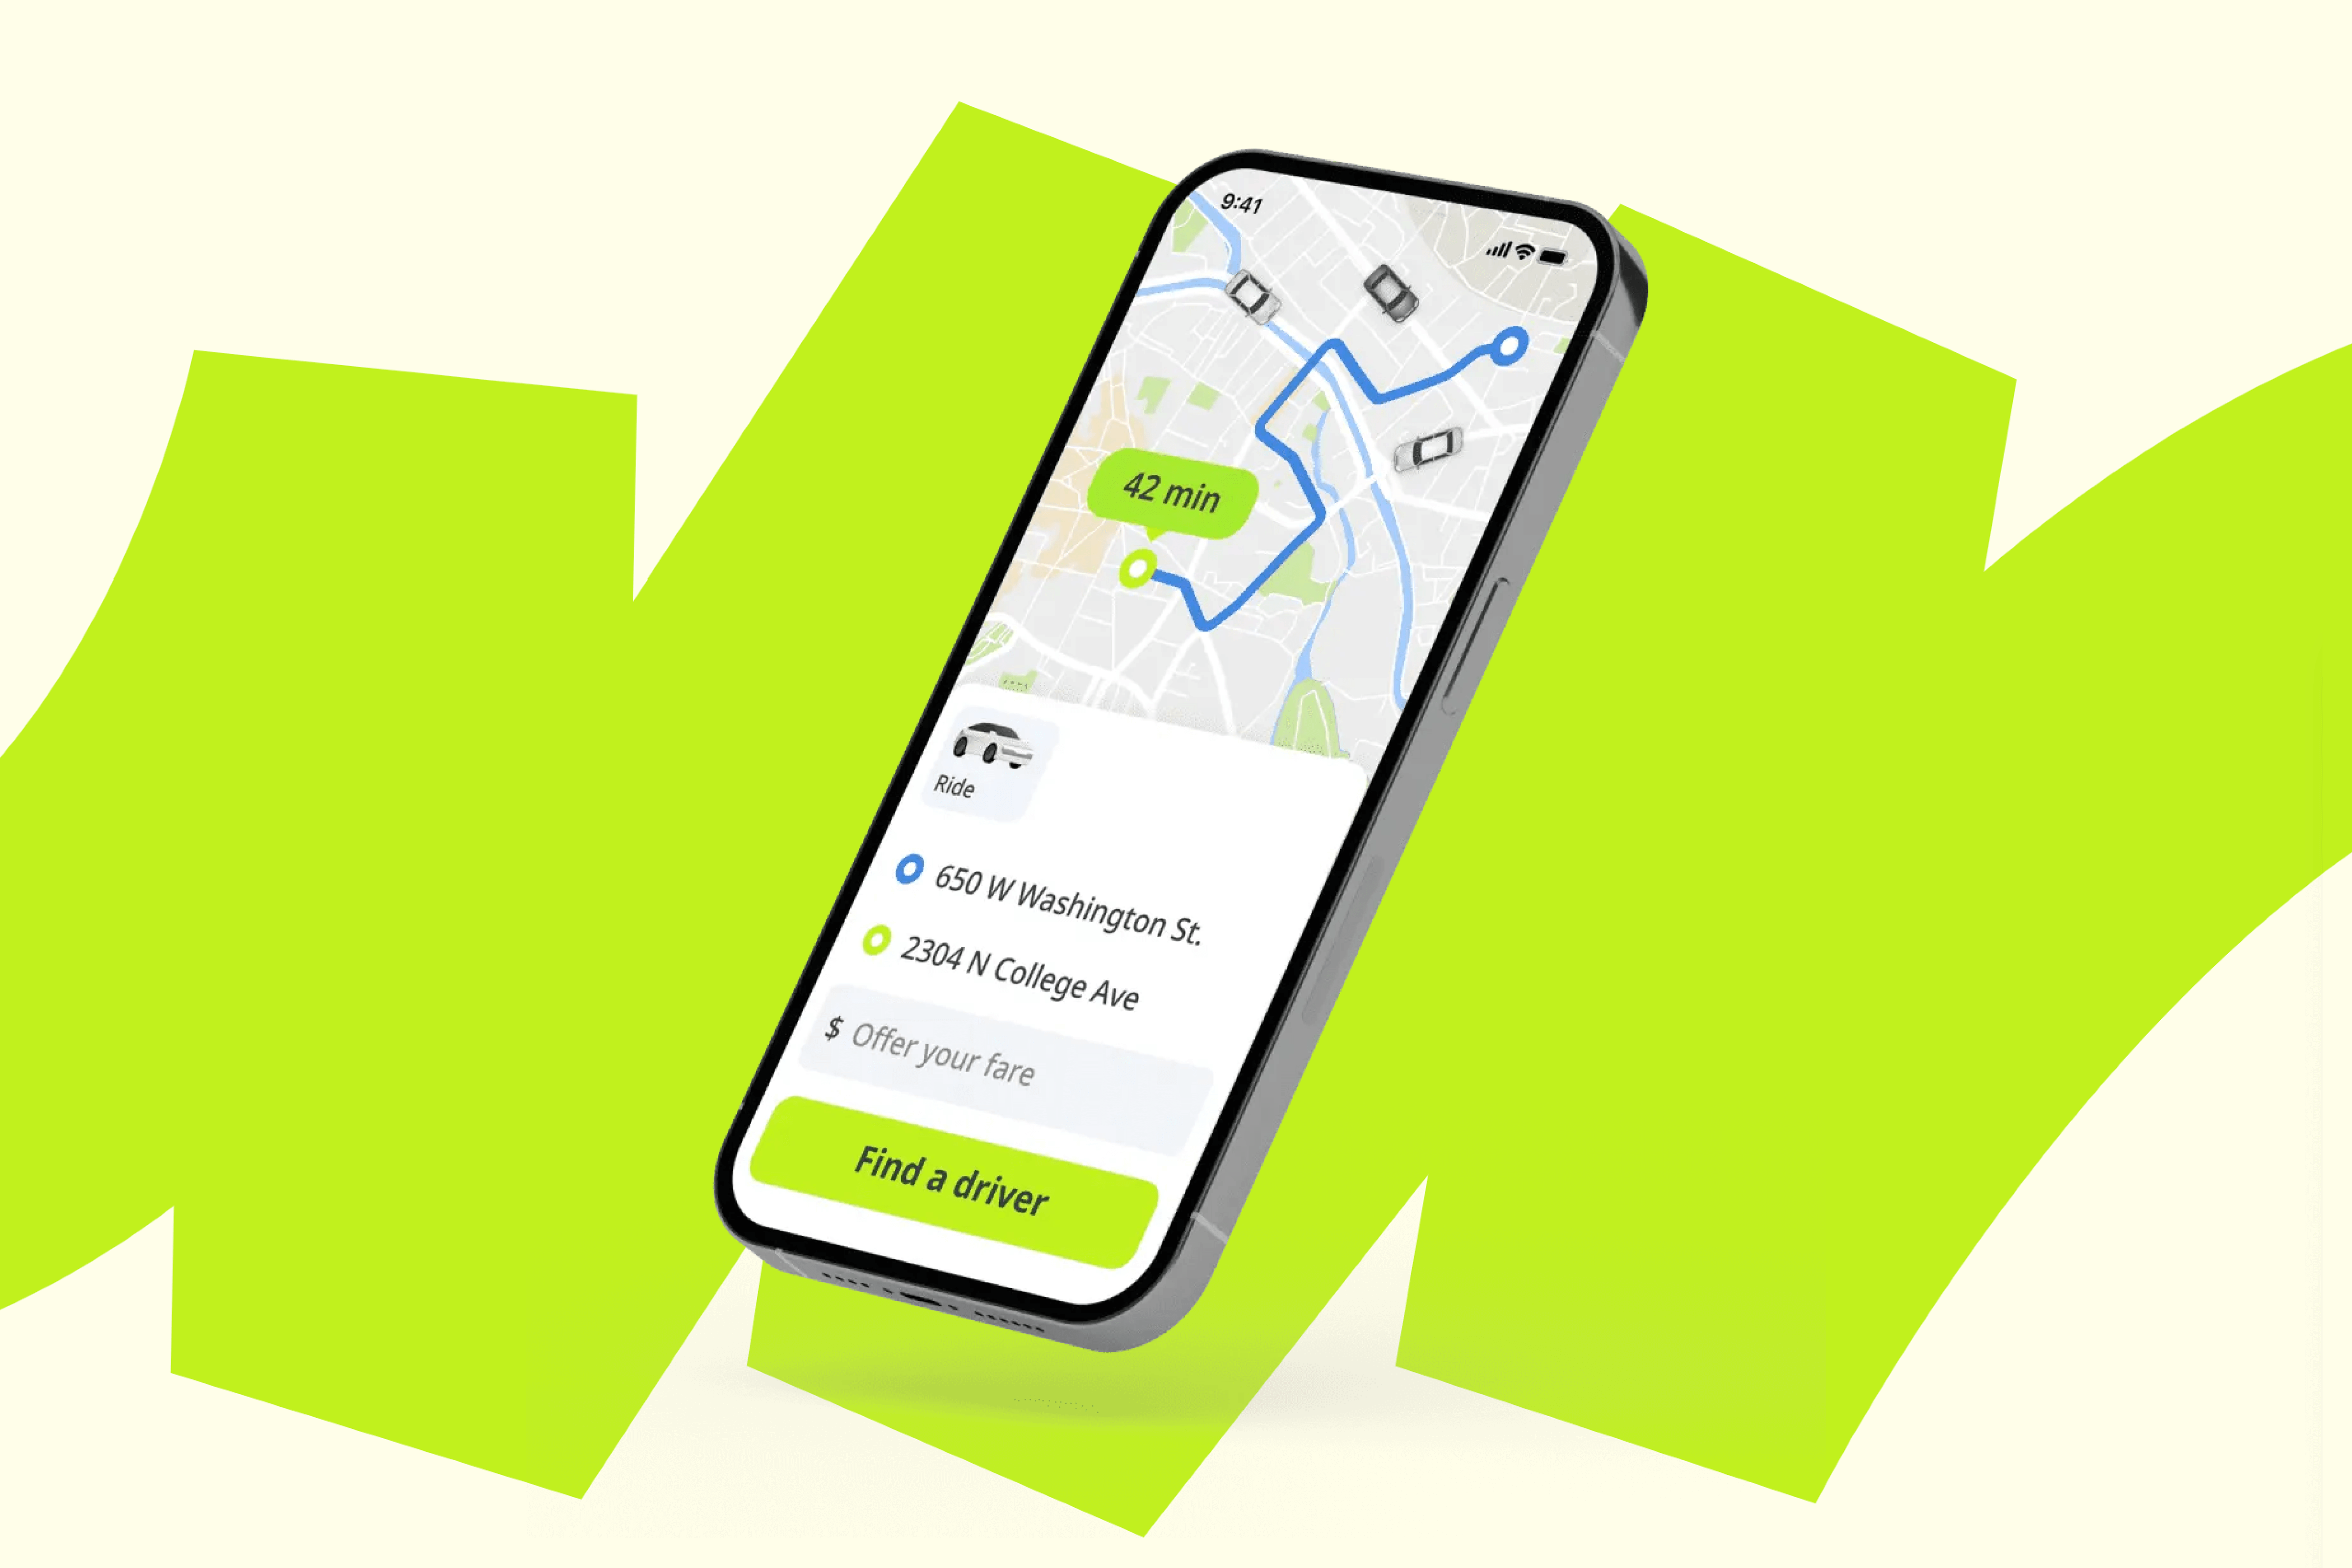
From our previosu blog “How to Find Your Niche in the Ride-Hail Market”, we saw how localisation and user control drive loyalty and conversion.
This new pricing flexibility supports:
This is just one of the 300+ features available in ATOM’s white-label ride-hailing platform.
Let’s talk about how to launch or upgrade your app with “Offer your price”, advanced pricing logic, and more tools to dominate your niche.
👉 Contact our team and explore how to become the market leader: www.atommobility.com
"State of art technology in mobile apps and dashboard, very good SLA!"
"Easy, nice looking, continuously updated and developed every month and most of all very reliable with a extreme high uptime"
"We used to work with a different service provider which wasn't fitting our needs. Switching to ATOM was an improvement on our side"
Use test credentials to log in - Phone number: +1 123123123, Code: 777777
Driver App demo credentials - Email: test@atom.com, Password: driver