Blog
Insights and news from the ATOM Mobility team
We started our blog to share free valuable information about the mobility industry: inspirational stories, financial analysis, marketing ideas, practical tips, new feature announcements and more.
We started our blog to share free valuable information about the mobility industry: inspirational stories, financial analysis, marketing ideas, practical tips, new feature announcements and more.
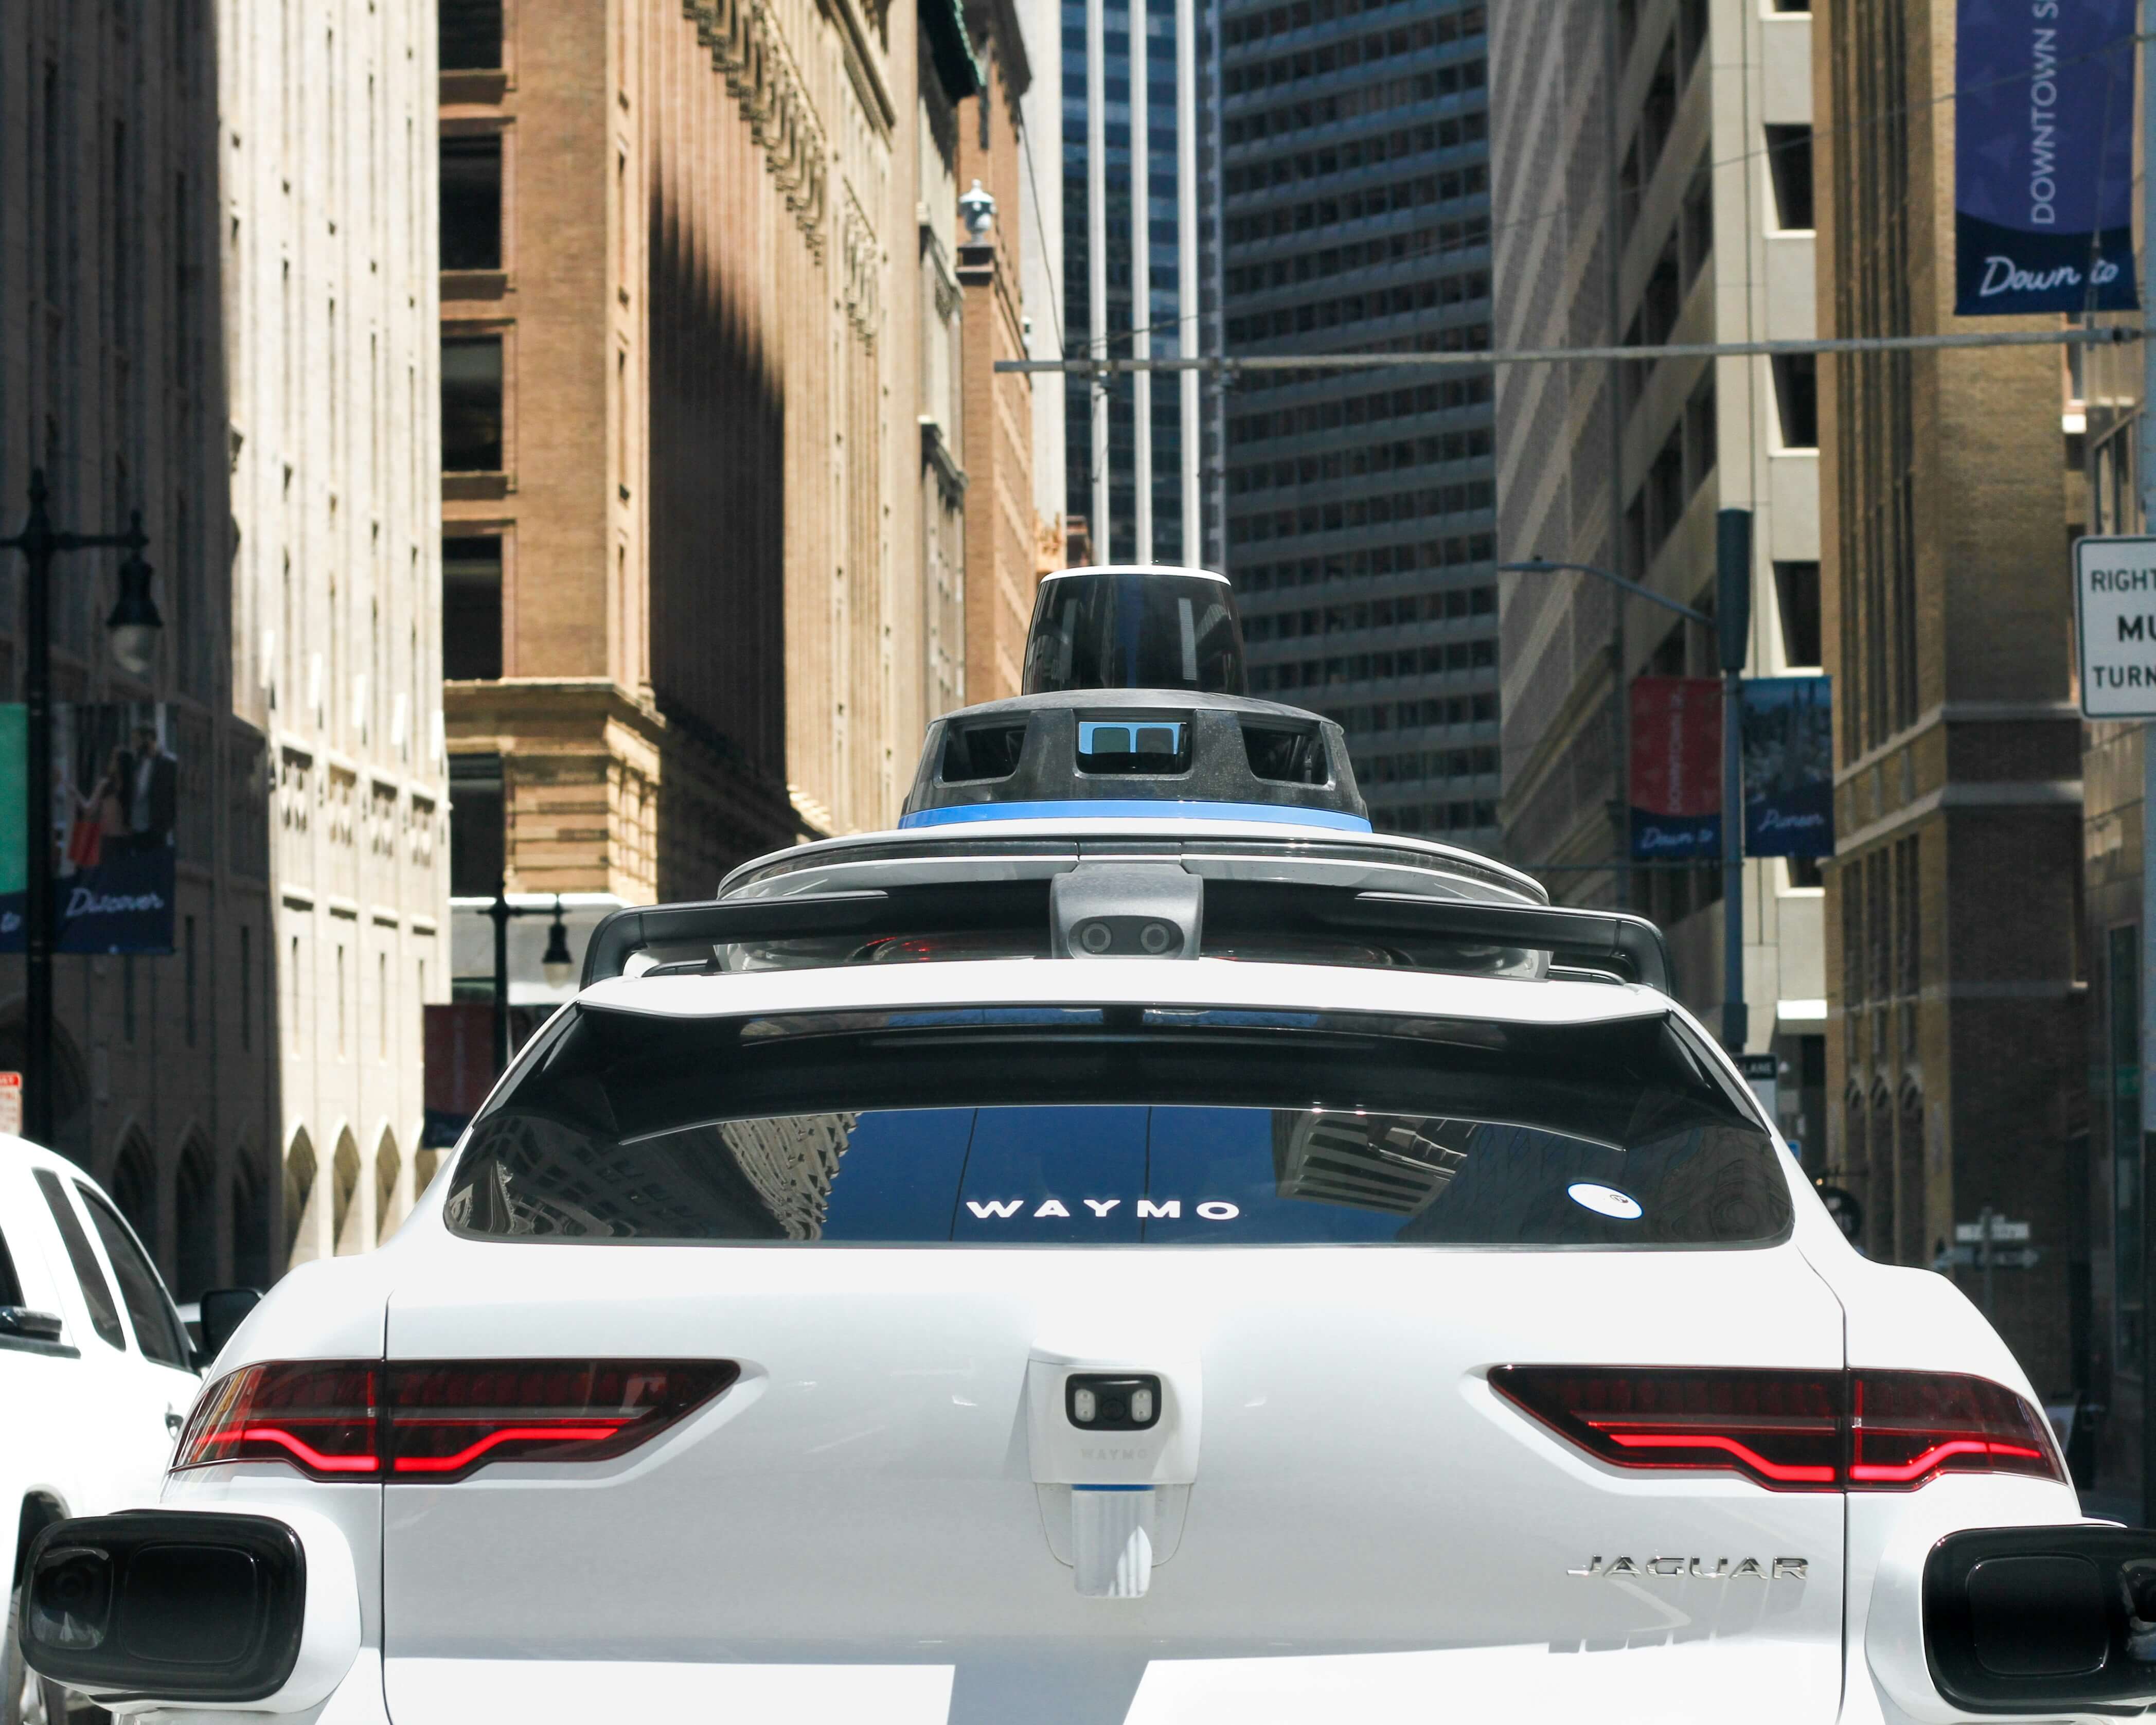
🤖 Who will actually operate Europe’s robotaxi fleets? Autonomous driving may remove the driver, but it doesn’t remove the work behind the car. Robotaxis still need charging, cleaning, maintenance, depots, customer support and someone managing the fleet every day. Early projects in Zagreb, Madrid and London illustrate different stages of deployment and how AV technology providers, fleet operators and booking platforms can work together. Taxi, rental and car-sharing companies already handle many of these tasks. What would it take to turn that experience into an autonomous fleet business?
For a taxi fleet owner, autonomous vehicles may seem to remove the most important part of the current business – the driver. But even without drivers, someone still needs to take care of the cars. They need to be owned or financed, charged, cleaned, inspected and repaired. Someone also needs to manage depots, deal with incidents, help customers and make sure enough cars are available.
The first robotaxi services and tests in Europe are already showing how this could work. The company that develops the autonomous driving technology does not always own or operate the cars. The app where customers book their rides may come from another company too. This could leave an important role for taxi, rental, car-sharing and other fleet companies that already know how to manage vehicles.
A taxi company today manages both cars and drivers. Drivers need to be recruited, scheduled, paid and supported. With a driverless fleet, these tasks would eventually disappear, but most of the work related to the cars would stay.
Autonomous cars still need charging or refuelling, cleaning, tyres, inspections, repairs and insurance. They also need somewhere to park when they are not working. If there is an accident or a technical problem, someone needs to deal with it and get the car back on the road. Customer support is still needed too when there are problems with bookings or payments, or when someone leaves something in the car.
Some of these tasks may even become more important. Robotaxis are expensive, and every hour a car spends charging, being cleaned or waiting for maintenance is an hour when it cannot take passengers. Moove, for example, already provides fleet ownership, depots, charging, maintenance and 24/7 operations for autonomous vehicles.
Drivers also do more than drive: they notice damage, report faults, help passengers and respond when something goes wrong. Without a driver, these responsibilities need clear processes and dedicated support. Existing fleet experience is an advantage, but operators will need to adapt it to vehicles running without someone behind the wheel.
There can be several companies behind one robotaxi ride. One provides autonomous driving technology, another may own the cars, and a local company can take care of the fleet. A platform such as Uber can then connect the cars with passengers. Sometimes one company may do several of these things, but this is not always the case.
Zagreb is one example. Pony.ai provides the autonomous driving system, Verne owns and operates the fleet, and Uber connects it with customers through its app. Autonomous rides became commercially available through Uber in August 2026 with a licensed operator onboard. On 10 September, Pony.ai and Verne also started fully driverless passenger test rides on a 22-kilometre route connecting parts of Zagreb with the airport. These are still limited test rides, not a fully driverless service across the whole city.
A similar model is being tested in Madrid. WeRide, Uber and AVOMO received permission in September 2026 to start testing and mapping under Spain’s ES-AV framework. The first 20 vehicles have an onboard specialist. WeRide provides the autonomous technology, Uber connects the cars with passengers, and AVOMO takes care of fleet operations. Commercial operations are planned for later in 2026, but the current permit is for testing and preparation rather than a general driverless taxi service.
In London, Wayve and Uber launched supervised autonomous passenger rides in September 2026. Customers can be matched with an autonomous vehicle through the Uber app, but there is still a licensed driver in the car.
The plans for the next few years are already much bigger. Pony.ai and Uber announced in August 2026 that they plan to deploy more than 2,000 robotaxis in Europe, starting with Zagreb and later expanding to four more European cities.
Bolt and Lucid announced another partnership in September, with Bolt aiming to deploy at least 25,000 autonomous Lucid vehicles across European cities. This is a future target, not 25,000 cars already operating today.
How these fleets are owned and operated may also be different from one city to another. Local regulations, available vehicles, charging and depot infrastructure and partnerships will all have an effect on how each service is set up.
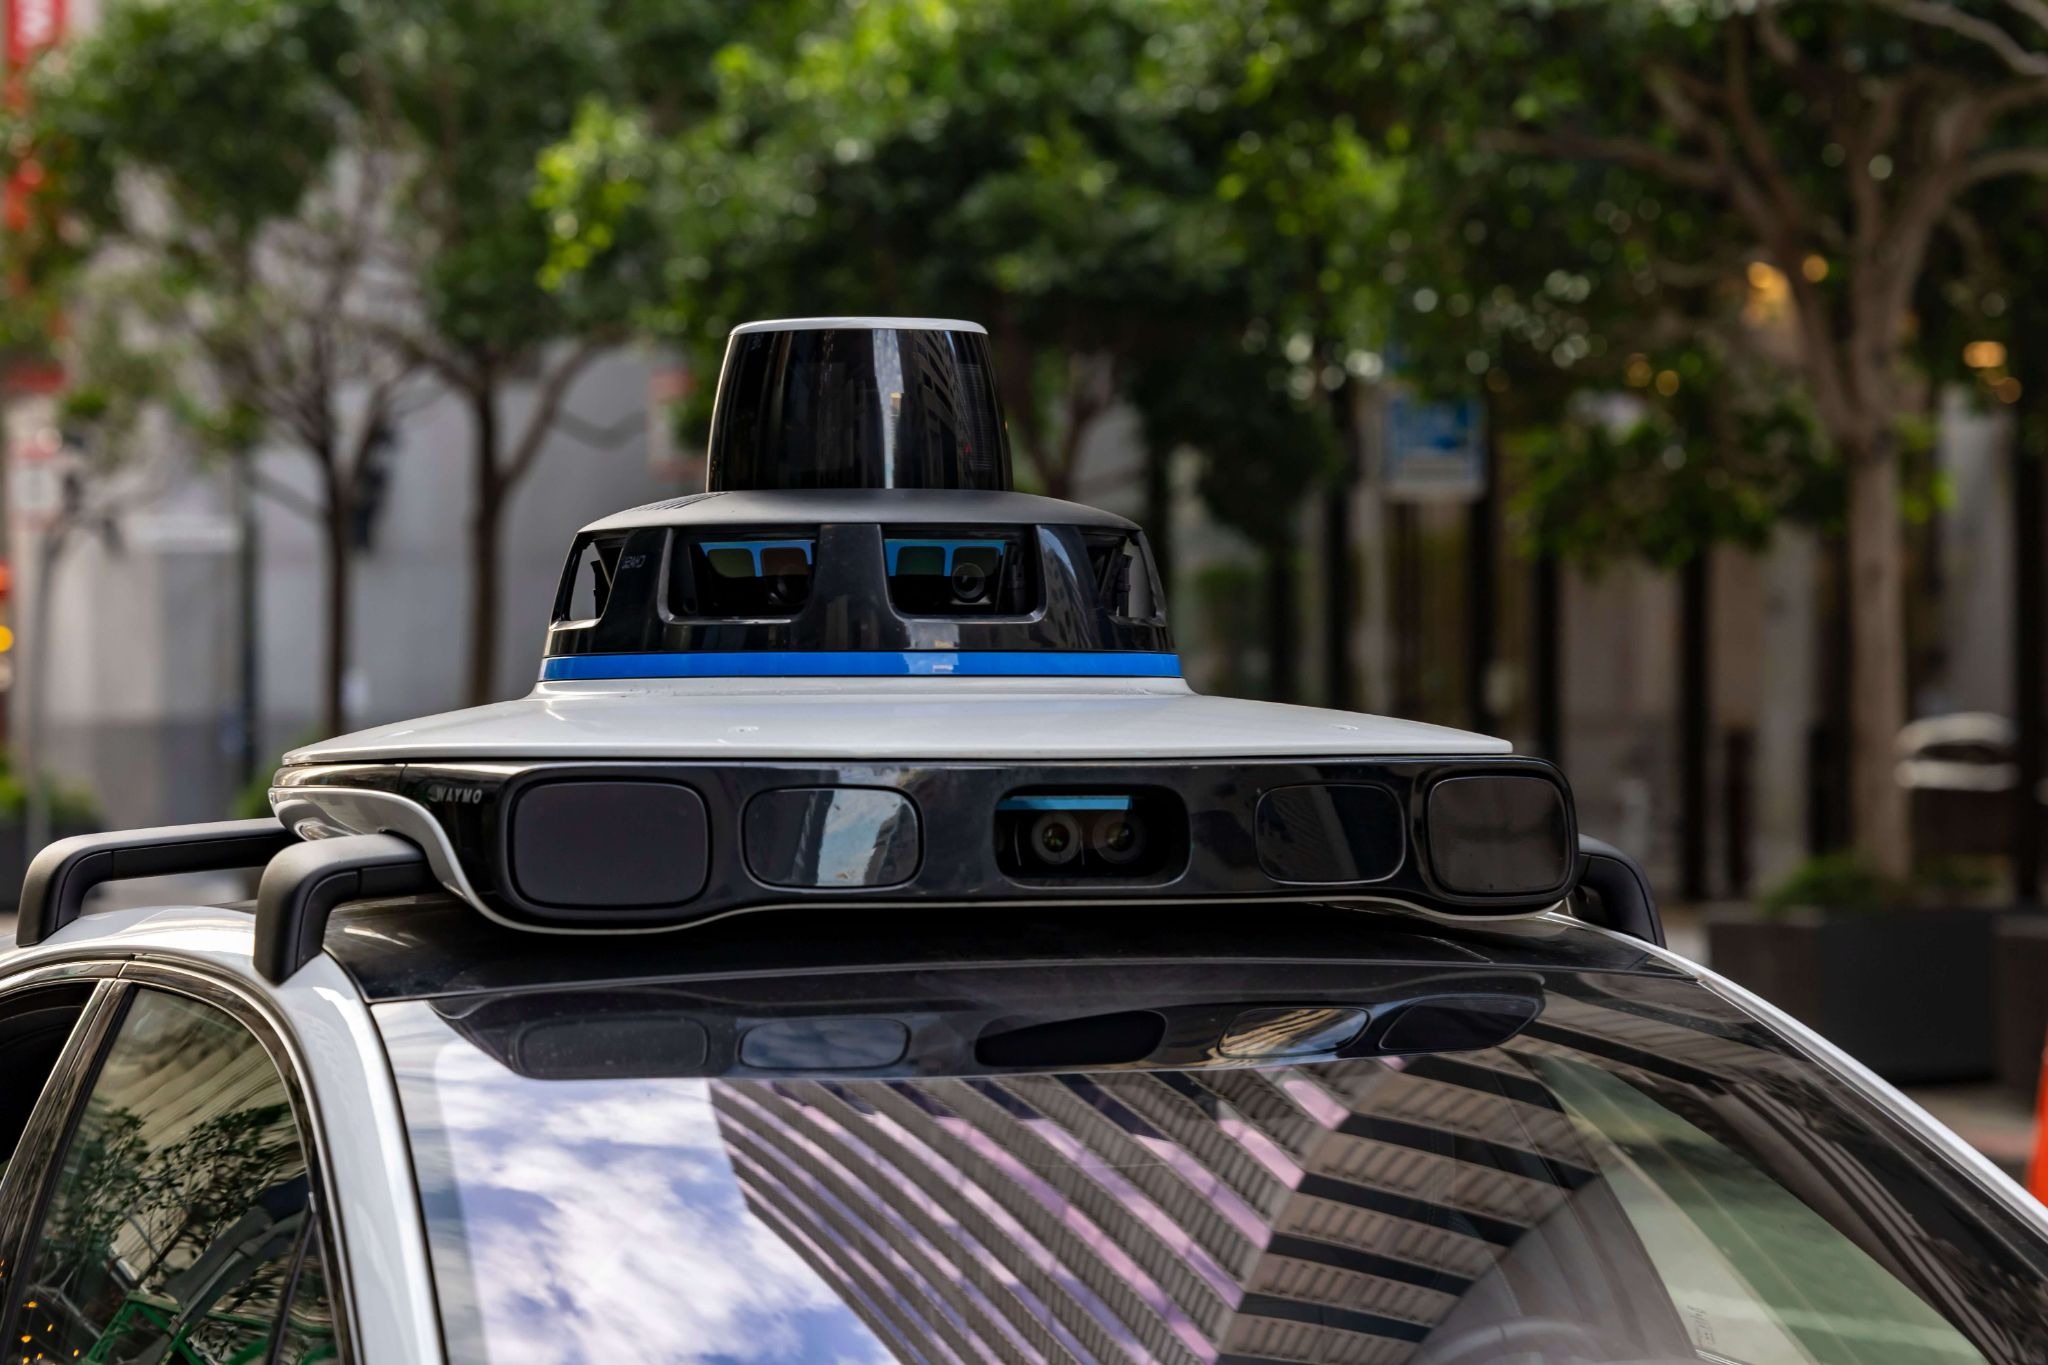
Taxi companies already do many of the things that would still be needed with an autonomous fleet. They maintain cars, deal with insurance and incidents, provide customer support and make sure enough vehicles are available. Some also already have their own depots, charging infrastructure or maintenance partners.
One possible model can already be seen in Zagreb. A local company owns and operates the autonomous fleet, while a larger ride-hailing platform brings customers. In the future, an existing taxi company could potentially have a similar role. Instead of managing cars and drivers, it could manage autonomous cars that receive bookings through a larger platform.
This does not mean platforms such as Uber will always rely on other companies to own the cars. Uber’s 2026 agreement with Rivian includes up to $1.25 billion in milestone-dependent investment and says that Uber or its fleet partners may purchase the autonomous vehicles. Uber is also developing infrastructure for autonomous fleets. Different ownership models are therefore possible.
Autonomous vehicles could also become interesting for rental and car-sharing companies, although this is probably further in the future. These businesses already manage vehicles, maintenance, cleaning, charging, bookings, customer accounts and payments, so much of the practical work is similar.
Autonomous driving could also change how rental and sharing cars are moved. Today, an employee may need to drive a car from one location to another. In the future, the vehicle could potentially do this itself within an area where autonomous driving is approved. It could even become possible for a rental car to drive itself to a customer’s pickup point.
Without drivers, it becomes especially important to understand how much time each vehicle is actually working. Every hour spent charging, being cleaned, waiting for maintenance or simply sitting unused means less time carrying paying passengers.
Some useful KPIs could be available hours per vehicle, paid trips per vehicle each day, revenue per available vehicle/day, empty kilometres, charging and maintenance downtime, cost per trip and incidents that need human help. These are most popular robotaxi industry KPIs of what a company could measure during a pilot.
For example, if cars spend too much time waiting to charge, the charging setup may need to change. A lot of empty kilometres could mean the cars are not in the right places, while too much maintenance downtime could make a vehicle more expensive to operate.
For either model, the business case depends on the partnership terms: who finances the vehicles, who carries the risk when demand is low, and how revenue and operating costs are shared. Operators should assess what remains after vehicle financing, insurance, charging, maintenance and partner fees. Depots, local service teams and reliable fleet availability could make an operator a valuable partner, but profitability still needs to be demonstrated.
One option for taxi fleets would be to work with an autonomous driving company and a larger ride-hailing platform. The local company could own or manage the cars and take care of the fleet, while customers book their rides through the larger platform.
Another option could be possible in cities where large ride-hailing platforms are not present or have limited coverage. A local company could work with an approved AV provider while using its own app, bookings, payments, customer support and fleet management.
In both cases, a company cannot simply buy autonomous cars and start offering rides. The technology needs to be approved, and local rules have to allow the service. These rules will also be different across Europe. Great Britain, for example, introduced its Automated Passenger Services permitting framework in 2026. Services similar to taxis or private hire vehicles need consent from the relevant local authority, while responsibility for the autonomous driving technology and the passenger service are treated separately.
A company does not need to have autonomous cars today to start preparing. A good first step is understanding the current fleet in detail – what each vehicle costs, how many hours it is available, how much time it spends charging or being repaired, and when cars are used the most.
Charging, cleaning, maintenance and depot processes are also worth looking at because all of these will still be needed with autonomous vehicles. A company interested in an AV pilot can then choose a location and use case, look at the local permit process and start talking to autonomous driving technology providers.
The software will also need some preparation. Customers still need to book and pay for rides, while the company needs fleet information, customer support, reporting and connections between its own systems and the AV technology. Starting with a small pilot makes it possible to test all of this before trying to build a larger service.
ATOM Mobility already provides many of the software functions used by taxi, ride-hailing, rental and sharing companies, including customer apps, bookings, payments, fleet management, maintenance tasks, analytics and APIs. Its ride-hailing software includes passenger and driver apps, dispatch, payments, fleet data, analytics and integrations. The ATOM Mobility API can also exchange data about vehicles, bookings, rides, payments, telemetry and maintenance tasks.
ATOM Mobility does not provide autonomous driving technology. This would come from a specialised AV company, and each project would have its own technical requirements and local approvals. For an AV pilot, ATOM Mobility could work with the fleet company and AV provider on the rider experience, integrations, fleet management and the data needed to measure how the pilot is working.
If you operate a taxi, rental or sharing fleet and want to explore an AV pilot, ATOM Mobility can help plan the booking and fleet-management setup, integrations and metrics you would need to test together with an AV technology partner.

At ATOM Mobility, we know there is a lot to consider when starting a mobility company. To help make the process easier, we’ve put together a breakdown of some most frequently recommended manufacturers and vehicle models on the market that are currently integrated with ATOM Mobility. Contact us in case you need a guidance or more information.

At ATOM Mobility, we know there is a lot to consider when starting a mobility company. To help make the process easier, we’ve put together a breakdown of some most frequently recommended manufacturers and vehicle models on the market that are currently integrated with ATOM Mobility. Contact us in case you need a guidance or more information.
What are the most reliable vehicles that are available right now on the market?
Scooters
Acton specializes in electronic scooters specifically designed for fleet operations. The company currently offers two different e-scooter models, as well as one e-bike model.

The Acton M Pro robust design includes industry-leading strength ratings, heavy duty welds, and proprietary aluminum extrusions.
Top speed: 18.6 MPH / 30.9 KMPH
Range: 30 miles / 48 km
Charge: 6 hours
Price: Contact us or ACTON directly

The Acton Topswap is e-scooter designed to include a patented battery swap system (on the same Acton M Pro model basis)
Top speed: 18.6 MPH / 30.9 KMPH
Range: 30 miles / 48 km
Charge: 6 hours
Price: Contact us or ACTON directly
Located in Hangzhou of China. Fitrider is an innovative high-tech company with variety of products: escooters, ebikes, swappable battery solutions, IoT/GPS, smart locks and docking/charging stations.

FitRider Scooter T2S with swappable battery design, 10’inch wheels, solid tyres and drum/disc brakes.
Top speed: 15.5MPH / 25 KMPH
Range: 20 miles / 35 km
Charge: 4-5 hours
Price: Contact us
Freego is the largest manufacturer and the first exporter of self balancing scooters from South China.
Top speed: 15.5MPH / 25 KMPH
Range: 30 miles / 48 km
Charge: 3-5 hours
Price: 600 USD / 556 EUR
Zhejiang Okai Vehicle Co., Ltd. produces professional high quality scooters, both electric and gasoline. Scooters of this company is widely used by largest scooter sharing companies in Europe.

The ES400 model is specifically designed for highly efficient sharing platforms. Swappable battery, very durable and fully hidden cables.
Top speed: 18.6 MPH / 29.9 KMPH
Range: 16Ah = approx. 32 miles / 51.5 km, 9.6Ah = approx. 24 miles / 39 km
Charge: 3-4 hours
Price: ES400 - 700 USD / 650 EUR, ES200 (non swappable battery) - 595 USD / 550 EUR
Segway Inc. is the worldwide leader in personal electric transportation. Almost all major sharing companies using or used scooter manufactured by Segway.

The Segway Ninebot ES4 model was the first model widely used for sharing. It comes with a dual-battery offering and solid design. However, the durability of this model is low comparing to other vehicles in this review.
Top speed: 18.6 MPH / 29.9 KMPH
Range: 28 miles / 45 km
Charge: 6-7 hours
Price: 300-400 USD / 250-350 EUR

The 10-inch pneumatic tires on the Kickscooter MAX can climb slopes that have a 20% incline. Special cable protection. Durable model with option to upgrade to PRO with swappable battery function.
Top speed: 18.6 MPH / 29.9 KMPH
Range: Approx. 23 miles / 37 km
Charge: 6-7 hours
Price: 480 - 580 USD / 440 - 540 EUR
Superpedestrian offers the first micro mobility platform built on intelligent electric vehicles and cloud tools.

The Superdestrian model by US based mobility company of the same name offers a 12+ months vehicle lifetime, real-time safety checks, active protection systems and a robust design offering.
Top speed: 15.5 MPH / 25 KMPH
Range: 56 miles / 90 km
Charge: 7 hours
Price: -
Electric Bikes / Mopeds

Designed specifically for shared fleet services, this electronic bike model will launch in spring 2020 with fully integrated IoT.
Top speed: 21.75 MPH / 35 KMPH
Range: 35 miles / 56 km
Charge: 6 hours
Price: Contact us or ACTON directly
NIU delivers electric vehicle in the two-wheel class powered by a Bosch Electric Motor and Panasonic Lithium Battery.

Designed specifically for shared fleet services, this electronic bike model will launch in spring 2020 with fully integrated IoT.
Top speed: 28 MPH / 45 KMPH
Range: 35-45 miles / 50-70 km
Charge: 6 hours
Price: 2593 USD / 2400 EUR

The Gonbike Pab model is a fully integrated e-bike, with native IoT integration and high battery capacity up to 49.7 m / 80 km.
Top speed: 15.5 MPH / 25 KMPH
Range: 50 miles / 80 km
Charge: 6 hours
Price: 995 USD / 930 EUR
FitRider M2 ebike

Swappable battery design, 14 or 16 ’inch wheels, strong frame, drum brake and build-in IoT/GPS.
Top speed: 15.5 MPH / 25 KMPH
Range: 45 miles / 70 km
Charge: 3-5 hours
Price: Contact us
This is the first part of hardware overview. In next blog post we will cover IoT/GPS devices and then smart locks. Contact ATOM Mobility for any additional questions or inquiries you may have about available products and suppliers.
ATOM Mobility - We empower entrepreneurs to launch vehicle sharing platforms.

The mobility industry is growing at a rapid rate, with innovations happening across cars, bikes and scooter sharing alike. This article explores the most recent advancements in the market and how industry leaders are finding new ways to compete. Learn about the different models for Mobility as a Service and what it means for the future of transportation.
The mobility industry is growing at a rapid rate, with innovations happening across cars, bikes and scooter sharing alike. This article explores the most recent advancements in the market and how industry leaders are finding new ways to compete. Learn about the different models for Mobility as a Service and what it means for the future of transportation.
According to research by the Internet of Things, the number of carsharing service users across the world is expected to grow from 50.4 million people in 2018 to 227.1 million in 2023. The number of cars used for car sharing services is also forecasted to increase from 332,000 at the end of 2018 to 1.2 million by 2023. The rising demand for these services has driven more companies towards developing methods of sharing that go beyond traditional single use cars.

Image source: Internet of Things
Free Floating
A new model of car sharing that has recently grown in popularity is free floating carsharing, which allows users to pick up a car in one location and return it anywhere within a predefined Home Zone. Challenging the idea of ownership, this service currently has 3 million users worldwide, with over 30 thousand vehicles available across more than 50 cities.
there are currently over 30 thousand vehicles equipped with this service across more than 50 cities worldwide
Dailmer and BMW became a leader in the free floating industry when they merged their two car sharing services, Car2Go and DriveNow, in February 2019 to form SHARE NOW. With over four million members, the free floating car rental service is available in 18 major cities across Europe with a fleet of 20,500 vehicles to choose from. Members register through a mobile app, gaining access to the services for the cost of $0.32 per minute. The company covers the fixed costs of car loans, car insurance and car maintenance so users are able to enjoy the freedom of driving without the responsibility of ownership.
The largest benefit of free float car sharing is the higher demand that can be met on average per ride and car each day. However, this model still includes a lot of operational day-to-day tasks such as maintenance, relocating, fueling/charging that can require a larger team.
Station Based
The traditional model of car sharing services is station based, where users can pick-up vehicles from a fixed rental station after filling out paperwork in person or through a mobile app. After signing an agreement, the renter is able to drive the car wherever they would like. The lease ends once the car is returned to a designated rental station that has been approved by the provider. This model does not provide the same flexibility to users that newer offerings have, however, it remains one of the best ways for providers to track the vehicles without developing complex systems.
Enterprise CarShare is an example of traditional station based car sharing services. Offering users three membership levels to choose from, the pricing varies based on hourly, daily and overnight rates as well as kilometers driven. Depending on the membership, hourly rates are around $8, daily rates $75 and overnight rates start at $29. The vehicles are available for pick-up at designated stations or lots and can be returned at the discretion of the user to any Enterprise location at the end of their trip.
Compared to free float services, station based car sharing has lower operational costs since only a few fixed stations need to be monitored and checked each day. Right now this model is most profitable in the market, once free float operators enter on a wider scale it will be harder to keep up with the high demand.
Peer-to-Peer
Peer-to-peer car sharing services have experienced large growth in the past few years. Research found that by 2017, more than 2.9 million people in North America were using these services renting over 131,336 vehicles. Peer-based car-sharing fleets expanded by 80 percent between 2016 and 2017 and memberships doubled.
The peer-to-peer car sharing model allows users to list their own vehicles on a sharing platform, connecting hosts to guests looking to rent. This style of sharing allows users to set their own rental rates, while giving members who are looking to rent a wider selection of vehicles to choose from.
Turo is a leader in the peer-to-peer sharing industry, serving as a marketplace where guests can book any car they want from hosts across the US, Canada, the UK and Germany. The guests are able to choose from a unique selection of cars within their area, while allowing the hosts an opportunity to earn extra money to offset the costs of ownership. The company currently has over 10 million users, with more than 350,000 vehicles listed for rent.

Image source: cnet
The rates for Turo are charged by the hour and are subject to adjustments made either by the company’s own algorithm or the specific daily rates charged by each host.
In this model, the operator acts as an aggregator without ownership over the vehicles, which makes it easier to scale the business without the need for huge capital investments. However, it becomes more difficult to control the quality of the experience since every car cannot be checked on a regular basis. It is important to establish a strong customer support team to help resolve any issues that occur.
Autonomous
The future of car sharing is focused on eliminating the driver all together. Autonomous vehicles are beginning to make their way into the marketplace, with the hope being that fleets of self-driving cars will be able to pick-up users at any given location and return to the designated charging area all on their own.
A leader in this next step of mobility is Waymo, a company that emerged from Google’s self-driving car project. The company launched their first commercial self-driving-car service in December 2018, in Phoenix. The self-driving cars operate in an approximately 100-square-mile radius, serving the towns of Chandler, Gilbert, Mesa and Tempe. Available to a select few pre-approved riders, the hope is that driverless vehicles will be a main part of transportation in the future. There are currently around 1,500 monthly active users helping with the testing program.
In theory, the economics of this model should be great as there is no driver costs or relocating costs, keeping operational requirements to a minimum. These vehicles will however be heavily regulated, with limited access in the near future.
The demand for accessible transportation in cities has expanded beyond traditional motor vehicles. Across the world, urban areas are beginning to adapt bike sharing programs that allow citizens to use both standard bicycles and e-bikes as a form of travel. The bikes are usually selected from one docking station, and later returned to another across the city. There is currently believed to be nearly 900 bike-sharing systems available globally, with continuous advancements being made each year.
The bike sharing market is expected to grow from a $2.7 billion dollar industry to $5 billion by 2025, according to a report by Research and Markets. That in mind, bike sharing companies across the world should approach expansion with caution to avoid over extending their services. In 2018, Chinese bike sharing start-up Ofo experienced financial decline due to their costly global expansion that was not supported by commercial success. The company was unable to maintain the accessibility of its competitors who partnered with mobile app providers, offering them a wider reach for their services. Without support from an investment partner, Ofo could no longer sustain the maintenance of its bike sharing fleets, let alone compete in the market.
We believe you can build a successful bike share company once you have the right strategy in place. It is important to be operationally efficient when starting out, initially launching a smaller fleet and growing organically with the demand. If you start by scaling wide without having the matching demand, your resources will be spread too thin. The most successful bike share programs work with the local municipalities and cities to determine revenue streams and find the best options to connect with riders.
Dockless Bike Sharing
The dockless bike sharing model offers users access to bicycles that do not require a docking station. Dockless systems allow the bikes to be located and unlocked through a mobile app then returned to a designated district at a bike rack or along the sidewalk. This model is designed for short term use, ideal when travelling or visiting somewhere as a tourist. Most dockless sharing services offer single rides for $1 or monthly fees for continuous use.
Lime was one of the first companies to offer dockless bike services. Users access the bikes at designated areas through the company’s mobile app, initially they are charged a fixed rate to unlock the vehicle and then per minute for the duration of their trip. The rates and promotions available vary based on location and time. Program packages are also offered for users who wish to make monthly payments or have the services available to their employees on a regular basis.
This model of bike sharing is ideal for users because it is easily accessible and convenient to employ every day. There are high operational costs that come with this type of service, as well as a larger risk for vandalism or damage to the bikes.
Station Based
Traditional bike share programs include docking stations where the bicycles are locked until a user purchases a ride. The user pays at a nearby pay station before unlocking the vehicle for a short term trip, later returning it to any available docking station when finished. There are typically two types of payment options available, a flat membership fee or pass that allows access to the bikes for a certain period of time and then a usage fee that charges for the amount of time you spend riding.
San Francisco is one of the first cities to create a regulatory and permitting framework around the trend of bike-sharing. In December 2019, 4,000 e-bikes were launched as part of the Bay Area bike sharing program, designed to make mobility easily accessible to citizens. The program provides rides with the option to purchase a single ride, starting at $2, through Lyft’s mobile ride-sharing app. There are over 300 docking stations available throughout the city, allowing users to travel across the Bay Area more efficiently.
The Capital Bikeshare, in Washington D.C. has a membership fee of $85 annually offering lower usage charges throughout the year. For the first 30 minutes a ride, members aren’t charged, they then receive a rate of $1.50 for the next 30, $3 for the third and finally an additional $6 for every other 30 minute period. For non-members, the first 30 minutes also has no charge but they experience higher fees for every 30 minutes after that. The higher usage fees are balanced out by lower costs at the start -- a daily Capital Bikeshare pass is only $8 and a monthly pass comes to $28.
Station based bike sharing can help bring a stable ROI for every bike since operational costs are low, and there is a minimal need for maintenance, relocation or charging. As dockless bikes continue to expand in the market, this model risks losing loyal users in the long-run.
Sponsored by Corporate
Some bike share programs operate in partnership with corporations who sponsor the vehicles. Operating like a standard bike share program, these vehicles operate in conjunction with the local municipalities.
In London, the city offers a public bicycle hire scheme funded by Santander UK. With more than 750 docking stations and 11,500 bikes available for hire around the city, users have easy access to the vehicles. The program operates 24 hours a day, year-round with an initial cost of 2 Euros for a daily trip, charging an additional 2 Euros per half hour after the first 30 minutes. Users have the option to hire a bike using their bank card at the docking station, or through the official mobile app.
This model is great for any operator that can find a reliable partner who is interested in establishing this type of deal, however, you still run the risk of losing that partner later on.
The fastest growing trend in mobility is the advent of e-scooters. They are inexpensive, accessible through mobile apps similar to bike sharing and available in over 100 cities worldwide. According to the US National Association of City Transportation Officials, riders took 38.5 million trips on shared electric scooters in 2018 compared to the 36.5 million trips on docked bikes. The Boston Consulting Group estimates that the global e-scooter market will grow to US$50 billion by 2025, with approximately 50% of the users being located in Europe and the USA. Micro-mobility is quickly becoming the preferred method for short term travel and companies have already begun to emerge as leaders in the market.

Image source: nacto.org
Station Based
Similar to station based bikes, some e-scooter providers offer docking stations where the scooters can be unlocked through a mobile app and then returned later to any available docking station.
DASH Scooters operates out of Nashville, TN, offering docked e-scooters styled like vespas that can be rented at set rates through their mobile app. Starting at $40 for two hours, the rates increase based on time travelled and day of the week. The brand launched after the emergence of other leaders such as Bird, Lime and Spin, who have set the bar for innovation in e-scooters. Their app allows users to locate nearby docking stations where the scooters can be returned to at the end of a trip.
The best way for operators to get a high return on their business is to have a combination of station based and dockless scooters. This will help maintain growth over time, while keeping up the high demand.
Dockless Scooters
Leaders in the mobility industry have begun to focus on the possibilities of dockless scooters. This model involves e-scooters that do not require a docking stations, but instead can be rented from a designated location and then returned anywhere in another.
Spin operates in 62 cities and 20 campuses across the United States, offering fleets of electric scooters for easy, short term travel. Users are able to unlock the scooters through their mobile app, once the ride is complete they can leave the scooter at any designated location and the cost will appear on the app. Charges vary depending on the length of the ride.
This model is currently experiencing high demand due to its convenience and ease of access for users. There are a large amount of maintenance and operational costs required, similar to other dockless mobility services, as well as increasing regulations across cities.
Hotel Services
While the future of e-scooters in cities is an on-going process, the services have begun to expand into the tourism sector. Hotels and resorts have begun to offer scooter sharing services to allow guests to easily travel throughout the location, or explore local surroundings. The options vary between station based and dockless scooters, with pricing packages being dependent on the destination.
Rentskoot is a start-up in Finland that offers small fleets of electric scooters to hotels. Guests are then able to rent the scooters from the hotel premises as a unique way to experience the local neighbourhoods. The company provides operational training to staff, free maintenance and the ability to advertise the hotel’s logo on the scooters. Travelling at a maximum speed of 25 km/h, the compact size and battery life makes this service ideal for short term use within cities.
By focusing on hotels, this model allows businesses to be more innovative with their designs while keeping a consistent demand amongst the growing market. An agreement will need to be made with the hotel in advance regarding guidelines for use and overall costs distribution.
What does this mean for the future of mobility?
The car sharing industry is projected to reach a 16.5 billion USD revenue by 2024, with an annual increase of 34.8% every year. A trend towards electric vehicles is also predicted as the demand for lithium-ion batteries has been predicted to increase by 380% by 2025. In addition, the bike and scooter rental market is expected to grow from USD $2.5 billion in 2019 to USD $10.1 billion by 2027, at a CAGR of 18.9 percent. Dockless systems will most likely continue to dominate the market, as their flexibility and ease has historically made them the more popular option for riders.
Every sector of MaaS has one thing in common: the desire to make transportation easier for riders. Ultimately each service compliments the other by providing different options for mobility that can each work together to get a user from point A to point B and back. If someone arrives in the city by train, they could then travel to work using an e-bike or e-scooter to avoid traffic. When returning home late at night a car sharing service could be used to get them there in one trip. The hope is that the future of mobility will consist of a connected network designed for safe, efficient and easily accessible travel.
With this quickly growing market on the rise, there hasn’t been a better time to become a leader in mobility. Start your journey in 20 days with ATOM!

Technology is helping transform the future of urban transportation by influencing what mobility will look like, and how it will impact the modern city-scape. A recent article by Forbes Technology Council explained that there is a shared consensus around the four key features of future mobility: shared, hybrid, autonomous and electric. The next question becomes, what will mobility services will be available in the coming years? We have done some research to help breakdown the different perspectives on shared mobility as a mode of transportation in the future.
Technology is helping transform the future of urban transportation by influencing what mobility will look like, and how it will impact the modern city-scape. A recent article by Forbes Technology Council explained that there is a shared consensus around the four key features of future mobility: shared, hybrid, autonomous and electric. The next question becomes, what will mobility services will be available in the coming years? We have done some research to help breakdown the different perspectives on shared mobility as a mode of transportation in the future.
Why electric?

By 2040, electric cars will outsell gasoline-powered cars
Recently consumers have shifted their interest towards electric vehicles as a more sustainable and environmentally conscious option for long-distance travel. Predictions expect electric vehicles to surpass traditional combustion cars within the next 20 years, with 57% of passenger vehicles and more than 30% of global passenger vehicle fleet sales being electric by 2040. With this growth also comes a need for additional charging infrastructure to allow the vehicles to travel further over long distances. Currently there are about 13,000 electric vehicle fast charging stations across the US, compared to roughly 332,000 gas stations. Companies such as Volkswagon, GM and Tesla, have announced they are working on creating charging that will help drive sales in the future. Successful expansion into the market will require cities to develop smart plans that accommodate the needs of electric mobility.
Why shared?
Shared mobility has grown extensively since Uber (2009) and Lyft (2012) first entered the market. More and more operators continue to emerge worldwide, offering at least one ridesharing service to people in over 700 cities. These services are expected to expand even further in the future as a result of increased urbanization, as well as growing concerns around sustainability, economic stability and emissions. A report by the Internet of Things’ analyst firm, Berg Insights, found the number of car-sharing service users will grow from 50.4 million people in 2018 to 227.1 million people in 2023. Offering mobility as a service is helping reduce the number of single-use vehicles on the road, lending itself to a more functional form of travel.
Why autonomous?
A major challenge facing urban drivers is the issue of congestion and traffic jams. In some metropolitan cities, such as London, the problem lead to the enforcement of congestion charges in their most heavily populated neighbourhoods. In effect since 2003, these charges have helped reduce traffic by 30%, will simultaneously generating funds for the city. But is that enough? Autonomous vehicles are believed to be the next step in reducing congestion. A study conducted by researchers at the University of Cambridge found that when a fleet of autonomous vehicles are effectively communicating, keeping traffic moving smoothly, congestion rates could be reduced by 35%.
Why hybrid?
Micro-mobility is the use of small mobility devices, designed to carry one or two people, or ‘last-mile’ deliveries. This goes hand-in-hand with the rising interest in e-scooters and e-bikes that have seen exceptional sales growth in recent years. The combination of electric with single-use, lightweight vehicles is expected to surpass traditional modes of transportation. In their annual technology, media and telecommunications predictions, Deloitte predicted more than 130 million e-bikes will be sold between 2020 and 2023. Compared to the 1.8 million sold in Europe and 185,000 in the US during 2013, this significant increase suggests that e-bikes and other technology like it are the future of mobility.
How are city’s supporting?
Cities across the world have begun adapting strategies to assist with the future of urban mobility. Being the leader in reducing traffic, Singapore introduced Area licencing Scheme in 1975, enforcing a daily toll charge of $3 or $60 monthly for cars entering a central zone area during peak hours. The city experienced success resulting in fewer cars entering the zone during peak hours, a 35 percent increase in carpools and a minimum of $500 million saved by the city that could be used towards infrastructure improvements. The system has since been updated to an Electrical Road Pricing system in order to match the changing demands of the city’s core.
San Francisco has yet to enforce congestion pricing for its traffic heavy neighbourhoods, however, research is being conducted to determine the best solutions for the city. The Emerging Mobility Evaluation Report by the San Francisco Transportation Authority found 90 percent of all motor vehicle collisions are caused by human error, with approximately 80 percent involving some level of inattention. This has lead to a shift towards alternative modes of mobility and potential pilot projects within the city core. San Francisco has become known for its low income bike share programs. Launching in 2013 the Bay Area Bike Share Pilot requires at least 20% of stations be located in low-income communities, with an estimated 320 stations and 4,500 in 2017. Data collected by the Bike-sharing Blog estimates there are twice as many bike-sharing programs in the world as there were in 2014, with nearly 20 times more bikes available for public use.
The doors have opened for industry leaders to start making innovations within auto-mobility, influencing the modern city-scape. In addition to placing restrictions on heavily congested areas, the city of Helsinki has focused its efforts on improving the existing infrastructure and transportation options to encourage people to utilize other modes of mobility. A leader in mobility-as-a-service (MaaS) platforms, the city plans to replace 2.3 billion urban private car journeys annually by 2023. One of the ways it’s begun to accomplish this is through the app Whim. An app developed specifically for Helsinki, Whim provides access to all of the city’s mobility options through a monthly subscription. The future of mobility is at people’s fingertips.
What’s next?
Cities around the world are beginning to explore the possibilities of e-scooters as a means to travel short distances too far to comfortably walk, as well as a potential solution towards reducing the reliance on cars. The city of Tallahassee launched a pilot program in partnership with five major e-scooter companies: Bird, Lime, VeoRide, Spin and Gotch. The purpose is to determine solutions for the major problems being faced, but to also help develop good ridership habits. The companies deployed 200 e-scooters, each capable of travelling 15 mph, under new legislation that allows them to be treated the same as bicycles. With the success of programs such as this, and companies making pledging to maintain social responsibility for user safety, e-scooters as a primary mode of mobility are on the rise.
Nuro, a self-driving start-up, is one of the few companies to currently have a fleet of fully driverless vehicles operating on public roads. In February 2019, the company secured roughly $1 billion in additional funding from SoftBank allowing them to partner with the grocery-store chain Kroeger’s for a pilot project. The pilot service has been delivering groceries in Houston, Texas since March 2019, with expansions to include other goods like Domino's Pizza and Walmart products. As of right now the fleet stands at about 75 vehicles, with plans to go public in 2020. By introducing fully automated vehicles into the market, the number of people on the road will be reduced, optimizing efficiency and offering greater protection from potential collisions or incidents.

Nuro self-driving vehicle
In addition to reducing traffic in major cities, mobility companies are also focusing their resources on addressing concerns of energy consumption and emissions. The smart scooter mobility company, Gogoro, aims to leverage the power of technology in order to change the way technology is consumed and transform how cities operate to improve sustainability. Their first fleet of smart scooters launched in 2015, delivering a high performance electric riding experience to uses in Taiwan. The company also established a network known as the Gogoro Energy Network in Taipei offers more than 1,581 battery swap stations and supports over 199,478 battery exchanges every day. In Europe, a fleet of 3,500 emissionless smart scooters were released across three major countries in 2018, helping reduce CO2 emissions by 123,655 tons and displacing more than 58,731,863 liters of gasoline. By leveraging technological progress and innovations in modern infrastructure, Gogoro is becoming a leader in transportation solutions.

Electric scooter Gogoro with swappable batteries
Companies, like Tortoise, are looking to expand the capabilities of scooters even further by introducing fleets that can move autonomously across a city and reposition themselves, without a rider. The goal is to tackle the biggest challenge currently facing operators: relocating scooters. Tortoise plans to use autonomous technology combined with teleoperation to reposition and rebalance dockless, shared e-scooters in cities. The initial deployment will include between 50 to 100 scooters per operator in each market with the intention to equip every fleet with the ability to autonomously reposition themselves. Autonomous micro-mobility like e-scooters and e-bikes are believed to be the start for creating smarter, more technologically advanced cities.
How can we help?
As both industry leaders and cities around the world are finding new ways to support the rising trend of micro-mobility, we at ATOM Mobility want to help entrepreneurs looking to enter the market. We believe that shared mobility is the future of transportation, offering assistance with integrating industry-leading vehicles ready for shared mobility, including kick scooters, scooters, bikes, mopeds, cars and more. Our customers have an excellent grasp on the current needs of local markets, and we allow them to focus on marketing and operations, while taking care of the technology.
Sources:
https://www.bbc.com/news/technology-33183031
https://www.corporateknights.com/channels/transportation/sharing-road-canadian-cities-driving-progress-shared-mobility-15593076/
https://www.forbes.com/sites/forbestechcouncil/2019/11/22/four-keys-to-future-mobility-shared-hybrid-integrated-and-electric/#3feea979339d
https://edition.cnn.com/2019/07/18/cars/electric-car-market-sales/index.html
https://about.bnef.com/electric-vehicle-outlook/
https://www.businessinsider.com/ubers-history#june-2016-kalanick-proclaims-that-uber-was-profitable-in-hundreds-of-cities-globally-but-that-the-money-was-being-reinvested-in-its-war-against-chinese-rival-didi-the-company-said-at-the-time-that-it-was-losing-1-billion-each-year-in-its-fight-against-didi-34
https://www.cnbc.com/2019/11/08/top-ride-sharing-apps-in-europe-asia-south-america-africa-and-usa.html
https://iotbusinessnews.com/2019/11/14/60333-the-public-carsharing-fleet-reached-332000-vehicles-worldwide-in-2018/
https://www.bbc.com/news/world-us-canada-47874725
https://www.sciencedaily.com/releases/2019/05/190519191641.htm
https://assets.publishing.service.gov.uk/government/uploads/system/uploads/attachment_data/file/846593/future-of-mobility-strategy.pdf
https://www2.deloitte.com/content/dam/insights/us/articles/722835_tmt-predictions-2020/DI_TMT-Prediction-2020.pdf
https://eresources.nlb.gov.sg/infopedia/articles/SIP_777_2004-12-13.html
https://eresources.nlb.gov.sg/infopedia/articles/SIP_832__2009-01-05.html
http://sfcta.org/sites/default/files/2019-03/Emerging%20Mobility%20Studies_11.pdf
https://www.sfmta.com/getting-around/bike/bike-share
https://www.businessinsider.com/bike-sharing-programs-doubled-since-2014-public-bikes-charts-2018-7?IR=T
https://www.smartcitiesworld.net/news/news/helsinki-leads-in-mobility-as-a-service-3308
https://whimapp.com/
https://eu.tallahassee.com/story/news/2019/07/15/electric-scooters-tallahassee-florida-bird-scooters-rental-gotcha-lime-spin-veoride-escooters/1708270001/
https://www.wctv.tv/content/news/Five-companies-launch-e-scooters-in-Tallahassee-during-pilot-program-512748851.html
https://nuro.ai/product
https://www.wired.com/story/softbank-nuro-self-driving-investment/
https://qz.com/1644476/nuro-will-deliver-dominos-pizza-with-its-robots-in-houston/
https://www.theverge.com/2019/12/10/21004678/nuros-driverless-delivery-robots-walmart-houston
https://medium.com/nuro/new-rules-of-the-road-for-california-and-autonomous-vehicles-2fa26a1159cb
https://www.gogoro.com/about/
https://www.tortoise.dev/
https://www.theverge.com/2019/10/15/20910083/tortoise-autonomous-electric-scooters-self-driving-robotics
https://www.fastcompany.com/90417611/it-was-inevitable-the-scooters-are-now-driving-themselves

ATOM representative attended the MadCity (https://madcity.lv/) conference and shared some results of ATOM's scooter sharing operations and presented few trends in sharing industry.
ATOM representative attended the MadCity (https://madcity.lv/) conference and shared some results of ATOM's scooter sharing operations and presented few trends in sharing industry.

ATOM Mobiity CEO on MadCity conference stage
Key takeaways:
- with good technological solution is relatively easy to attract first users;
- speed to market does matter;
- average ride is somewhere between 2 - 3.5km and 15-20 minutes;
- rides are way longer on sunny weekends;
- about 20% of riders are tourists;
- scooter sharing audience is very broad (does not matter if you are 18 or 60);
- user experience is critical to grow user base with low marketing budgets;
- analytics will help you maximize revenue by showing where demand will be higher;
- sharing is not an easy business, there are a lot of operations involved to make it profitable. ATOM team can help you avoid core problems;
- more types of vehicles - different, more robust and self-driving are coming.
You can watch the conference recording here:
http://straume.lmt.lv/lv/konferences/konferences/electric-scooter/1041683
Interested in e-vehicle sharing business? ATOM Mobility can help you with both technology and operational knowledge. Email us: support@atommobility.com
#rideatom #sharing #atommobility
"State of art technology in mobile apps and dashboard, very good SLA!"
"Easy, nice looking, continuously updated and developed every month and most of all very reliable with a extreme high uptime"
"We used to work with a different service provider which wasn't fitting our needs. Switching to ATOM was an improvement on our side"
Use test credentials to log in - Phone number: +1 123123123, Code: 777777
Driver App demo credentials - Email: test@atom.com, Password: driver